The best credit control software for UK SMEs is Paidnice, which applies UK statutory interest per customer group and posts it to Xero or QuickBooks Online, from £49 (US$69) a month.
Chaser, Credit Hound, Kolleno, Satago and Upflow complete the six, compared on whether the software works out the statutory charge itself and on published price, from £20 per user a month.
| Tool | Fits |
|---|---|
| Paidnice | a UK business on Xero or QuickBooks Online that wants statutory interest applied per customer group |
| Chaser | a UK team that wants Creditsafe credit checks in the same tool as the chasing, under £4m on Compact |
| Credit Hound | a Sage-first UK team that wants a dispute and promise-to-pay worklist, priced per user |
| Kolleno | an order-to-cash team on NetSuite or SAP |
| Satago | a Sage 50 or Xero team that wants bureau credit data with its chasing, no revenue band published |
| Upflow | an analytics-led finance team, five gross invoice value tiers from up to $10m to above $100m |
Take one overdue invoice for £12,000, paid 104 days after its due date. At the mid-2026 statutory rate of 11.75% the interest on it comes to about £402, and the fixed sum on a debt that size is another £100.
What is credit control software for UK SMEs?
Credit control software for UK SMEs reads overdue invoices from the ledger and works them: reminder sequences by email and SMS, statements, payment plans, a customer payment portal and, on the better tools, the statutory interest and fixed sum the 1998 Act allows.
It sits on top of Xero, QuickBooks Online, Sage or another ledger. The invoice is still raised there, and a charge the software computes either goes back onto the ledger as a document or is quoted in a chasing email, which reaches nobody's payables system.
What it is not:
- Not the ledger. Xero, QuickBooks Online or Sage stays the record of what is owed.
- Not a debt collection agency, which takes over a debt and keeps a percentage of what it recovers. Chaser hands debts to a collections partner, but the software itself chases your own customers on your own terms.
- Not invoice finance, although Satago sells finance alongside its chasing.
- Not a credit bureau. Chaser carries Creditsafe reports and Satago credit scores. Paidnice runs native credit checks from each customer's payment behaviour, and Creditsafe bureau checks through the API on the Custom plan.
Reminders and statements alone are a full use case, and the statutory charge is optional.
How this list was put together
This list helps a UK SME choose credit control software that raises statutory interest and the fixed sum itself.
| What we checked | Where the evidence came from |
|---|---|
| Does the tool work out the statutory rate under the Late Payment of Commercial Debts (Interest) Act 1998 on its own? | Vendor help pages on interest settings: a field you type 11.75% into is a different product from a toggle that reads the base rate and adds your percentage |
| Does it use the right rate for each six-month period the invoice spans? | Vendor documentation on how the rate is stored and updated |
| Can the rule differ between two customer groups? | Vendor help pages on fee and interest settings |
| Does the charge land on the ledger as a document? | Vendor help pages and Xero or QuickBooks Online integration notes |
| Is the entry price published, in pounds? | The vendor's own pricing page; two of the six print figures a UK buyer cannot plan with |
| Rating and review count | The Xero App Store, the Sage UK Marketplace or G2; two scores a tenth apart count as level, and the larger base carries more weight |
What does UK law let you charge on a late invoice?
The Late Payment of Commercial Debts (Interest) Act 1998 lets a UK supplier charge interest at 8% a year above the Bank of England base rate, a fixed sum of £40, £70 or £100, and reasonable recovery costs on an overdue B2B invoice.
The entitlement arrives on its own. It holds where the contract says nothing at all about late payment, so a customer gains nothing by keeping the subject out of the terms. The fixed sum attaches to the invoice rather than to the account, which means a customer sitting on nine overdue invoices has run up nine fixed sums.
With the base rate at 3.75% in mid-2026 the statutory rate is 11.75%. The base rate rose to 4% on 5 November 2026. Confirm the current number on GOV.UK before you charge.
Two charges you can raise today, and one that is only proposed
- Statutory interest
- 8% a year above the Bank of England base rate, so 11.75% at the mid-2026 base rate. Prorated across the days the invoice was actually late. GOV.UK
- Fixed compensation
- £40 on a debt under £1,000, £70 to £9,999.99 and £100 at £10,000 and above, per invoice, on top of the interest. GOV.UK
- Mandatory interest
- Proposed, not law. The Commercial Payments Bill would stop commercial contracts from contracting out of statutory interest. Check the bill's stage before you rely on it.
On £5,000 overdue for 45 days at 11.75%, statutory interest is £72.43 and the fixed sum is £70, so £142.43 is claimable in total.
How do the six UK credit control tools compare?
 |
 |
 |
 |
 |
 |
|
|---|---|---|---|---|---|---|
| Best for | Statutory interest per customer group on Xero or QuickBooks Online | Creditsafe checks and multi-channel chasing, under £4m on entry | Sage-first teams wanting a dispute and promise-to-pay worklist | Order-to-cash teams on NetSuite or SAP | Sage 50 or Xero teams wanting credit data and finance | Analytics-led teams that manage collections by metric |
| Revenue fit | Any size up to 50,000 invoices a year | Compact under £4m, Core from £4m, Complete to £100m | Not published | Under £1m on BusinessPay, tiers to £1bn and above | Not published | Gross invoice value tiers, up to $10m through above $100m |
| From (monthly) | £49 | £199 | £20 per user (Sage Accounting) | $650 per user | £45 (£25 inside Sage 50) | Hidden now; last published $440 (Grow), $880 (Scale) |
| Ledger integrations | Xero, QuickBooks Online and newer ledgers such as Rillet and Campfire (closed testing) on every plan; Sage Accounting and other ERPs on Custom | Xero, QuickBooks, Sage, NetSuite, Dynamics 365 Business Central | Sage 50, Sage 200, Sage Intacct, Xero | NetSuite, SAP, Sage Intacct, Business Central, Xero, QuickBooks Online | Xero, Sage, Sage 50, QuickBooks, KashFlow, FreeAgent | Xero, QuickBooks Online, NetSuite, Sage Intacct, Stripe Billing, Chargebee, Zuora |
| Late fee grain | Yes (per customer group) | Yes (one set of late-fee rules, not tied to schedules) | None found | None found | Not documented | No (via your ERP only) |
| Statements | Yes (any schedule) | Yes (monthly, fixed day) | None found | Yes (in the portal) | Yes | Portal PDF statement, no scheduled send |
| Payment plans | Yes (on Pro) | Yes | None found | Yes | Not documented | No |
| Portal | Yes | Yes | No (PayThem payment links only) | Yes | Not documented | Yes |
| Credit checks | Yes: native checks from payment behaviour, plus Creditsafe via API on the Custom plan | Yes (Creditsafe) | No (limits read from your ledger) | Yes (AI scores, bureau integrations) | Yes (credit reports and limits) | Yes (light scoring) |
| AI | Advanced Reads customer replies, drafts answers and follow-up actions (like PO updates) for your approval; MCP server for Claude, ChatGPT and other agents | None No named AI feature | Advanced AI agent support from Business Plus (Insights, Copilot drafts and an autonomous Agent); fully automated agent runs and AP portal features are billed separately by token use | None No AI feature found | Advanced Collections and cash application agents, from suggest-only to autonomous (Collections Agent from Scale, Cash Application Agent from Accelerate) | |
| Rated (source, count) | 5.0 (84, Xero App Store) | 4.98 (374, Xero App Store) | 5.0 (12, Sage UK Marketplace) | 4.9 (117, G2) | 4.93 (92, Xero App Store) | 4.8 (235, G2) |
"Not documented" means the vendor does not document it. "Not published" means no price is printed. "None found" means no evidence either way. Prices are the vendor's published from-price.
Five of the six tools on this page in five checked facts
- Four of the five print a monthly price: Satago from £45, Paidnice from £49 (US$69), Chaser from £199 and Kolleno from US$650. Upflow's current prices are hidden; its last published prices were $440 a month for Grow and $880 for Scale.
- Each published price grows with something different: a flat tier (Satago), invoice volume (Paidnice), revenue band (Chaser) and users (Kolleno).
- Three of the five apply a late fee themselves: Paidnice (per customer group), Chaser (one set of late-fee rules) and Satago (an optional fee in its reminder emails).
- All five connect to both Xero and QuickBooks Online.
- AI that handles collections work or customer replies: Paidnice, Upflow and Kolleno. No AI in receivables: Satago.
We checked each tool's own pricing, integration and help pages on October 26, 2026. "None found" in the data means the vendor's pages do not show the feature. Credit Hound: not in our checked dataset yet.
1. Paidnice, best for UK statutory interest
Best for: UK statutory interest per customer group.
Paidnice is a reminder and statutory interest tool for UK businesses on Xero or QuickBooks Online, up to 50,000 invoices a year, from £49 (US$69) a month on Essentials.
Who should choose Paidnice?
Choose Paidnice if you run a UK business on Xero or QuickBooks Online and want statutory interest applied per customer group without anyone doing the base-rate maths manually.
- Fits
- UK businesses on Xero or QuickBooks Online of any size up to $50m a year, or 50,000 invoices a year, with or without a credit controller
- Regions
- United Kingdom, Australia, New Zealand, United States, Canada, South Africa
- Entry cost
- £49 (US$69) a month on Essentials, covering 150 invoices, 600 emails and up to 2 team members; Pro from £74 (US$99) a month with unlimited users and no per-seat fee
- Rated
- 5.0 from 84 Xero App Store reviews; 4.9 from 14 on Capterra
- Awards
- Xero Global Small Business App of the Year 2025 and NZ Small Business App of the Year 2026
- Runs on
- Xero, QuickBooks Online, Stripe, Pinch Payments, CloudDepot, HubSpot, Pipedrive, Zapier. Newer ledgers such as Rillet, Campfire, Digits, DualEntry, Puzzle, Accounting Seed and Odoo are available on every plan through Paidnice's closed testing program. Sage Accounting, NetSuite, Sage Intacct, MYOB and Dynamics 365 Business Central connect on the Custom plan
- Statutory late fees
- Yes. A Bank of England base rate toggle applies the base rate plus your own percentage, using the correct base rate for each period an invoice spans, and policies sit under customer groups so different groups run different rules at once
- Does best
- Two charge types on the same customer group, an invoice late fee and a statement interest charge, both posted to the ledger
Paidnice is the enforcement layer on top of Xero and QuickBooks Online: reminder sequences per customer group, statements on the schedule you set including consolidated parent accounts, payment plans, and a customer payment portal. Reminders send by email and SMS from outbound@paidnice.com on Essentials. Payment plans and sending from your own domain start on Pro.
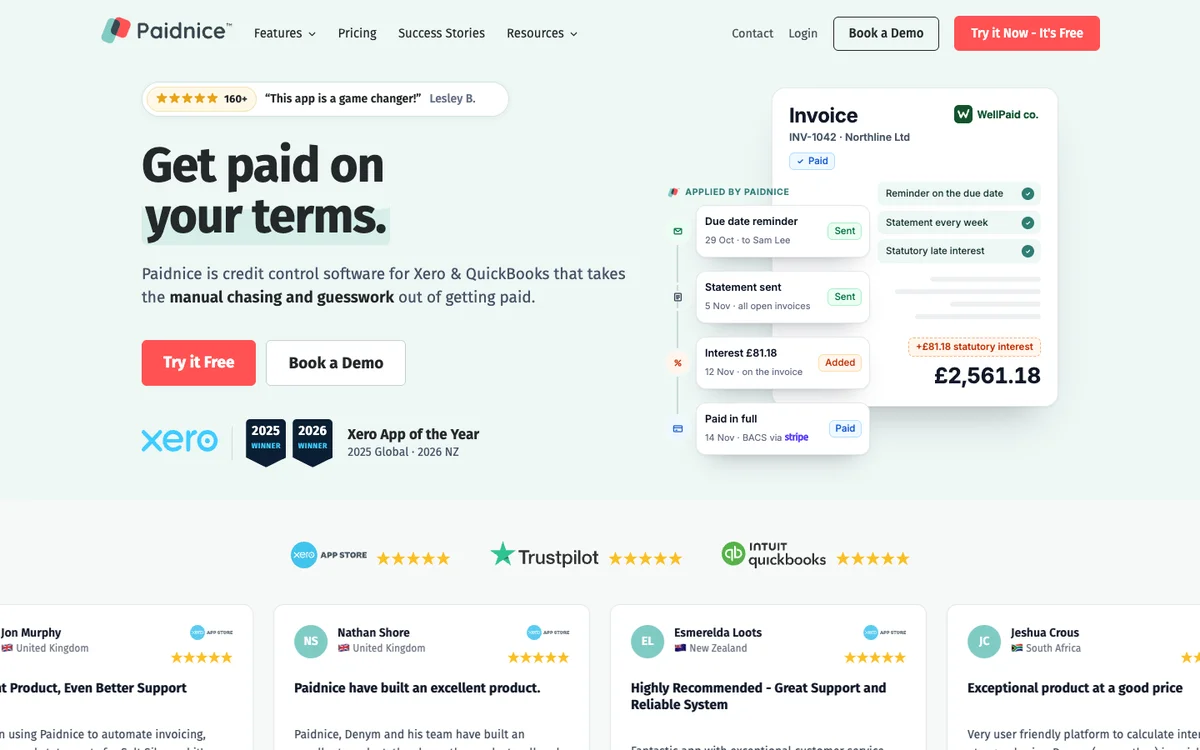
The charge is raised on the ledger as Draft or Approved, calculated on the balance net of any credit on the account, with compounding on by default and simple interest available as a deliberate choice.
Statement interest recalculates at the moment the statement sends rather than at the last policy run, so the figure a customer opens is accurate that morning.
Limitations with Paidnice. A Sage 50 or Sage 200 company cannot use it, because Paidnice connects to cloud ledgers only.
- NetSuite, Sage Intacct, MYOB and Dynamics 365 Business Central connect through a custom implementation on the Custom plan rather than a standard connector; the base rate toggle works on every plan and ledger.
- Some payment features differ between Xero and QuickBooks Online, and the entry tier covers two team members.
- Its review base is smaller than Chaser’s, 84 reviews against 374.
Credit control software for UK SMEs, compared (4:58)
2. Chaser, best for a named credit controller
Best for: UK teams with a named credit controller.
Chaser is a UK credit control tool with Creditsafe credit checks and multi-channel chasing, from £199 a month for turnover under £4m.
Who should choose Chaser?
Choose Chaser if you run a UK finance team with a named credit controller and want Creditsafe credit checks and multi-channel chasing running from one system.
- Fits
- UK-centred businesses with a named credit controller; Compact is priced for turnover under £4m, Core from £4m, Complete to £100m
- Regions
- UK-registered, trading since 2014, sells worldwide
- Entry cost
- £199/mo on Compact for turnover under £4m with 4 users; Core £599/mo under £10m; Complete £899/mo to £100m.
- Rated
- 4.98 from 374 Xero App Store reviews; 4.3 from 71 on G2
- Awards
- Finalist, UK Small Business App Partner of the Year, Xero Awards 2023
- Runs on
- Xero, QuickBooks, Sage 50, Sage 200, Sage Intacct, Sage Business Cloud Accounting, NetSuite, Dynamics 365 Business Central, AccountsIQ, SAP, HubSpot, Gmail, Outlook
- Statutory late fees
- Yes. Four calculation types including a Bank of England base rate type, recalculated daily, but one set of late-fee rules, across the account or for selected debtors, not tied to schedules, with no documented way to run different rules per group; no fee is raised on payment-plan invoices, and Chaser's help says a late fee cannot be added or updated after a part payment when written to Xero
- Does best
- Creditsafe credit checking and monitoring in the same tool as email, SMS and letter chasing. Credit checks are sold by credit on any plan and need Chaser billing, not Xero App Store billing; monitoring is not offered in Australia
- Customers
- Named on its website: Pact Coffee, Huttie and TaxAssist. Huttie's case study reports £15,000 of old debt recovered.
Chaser has been in the market since 2014 and sends reminders from the team's own Gmail or Outlook mailbox, adding SMS, letters, a payer portal and integrated collections through a partner.
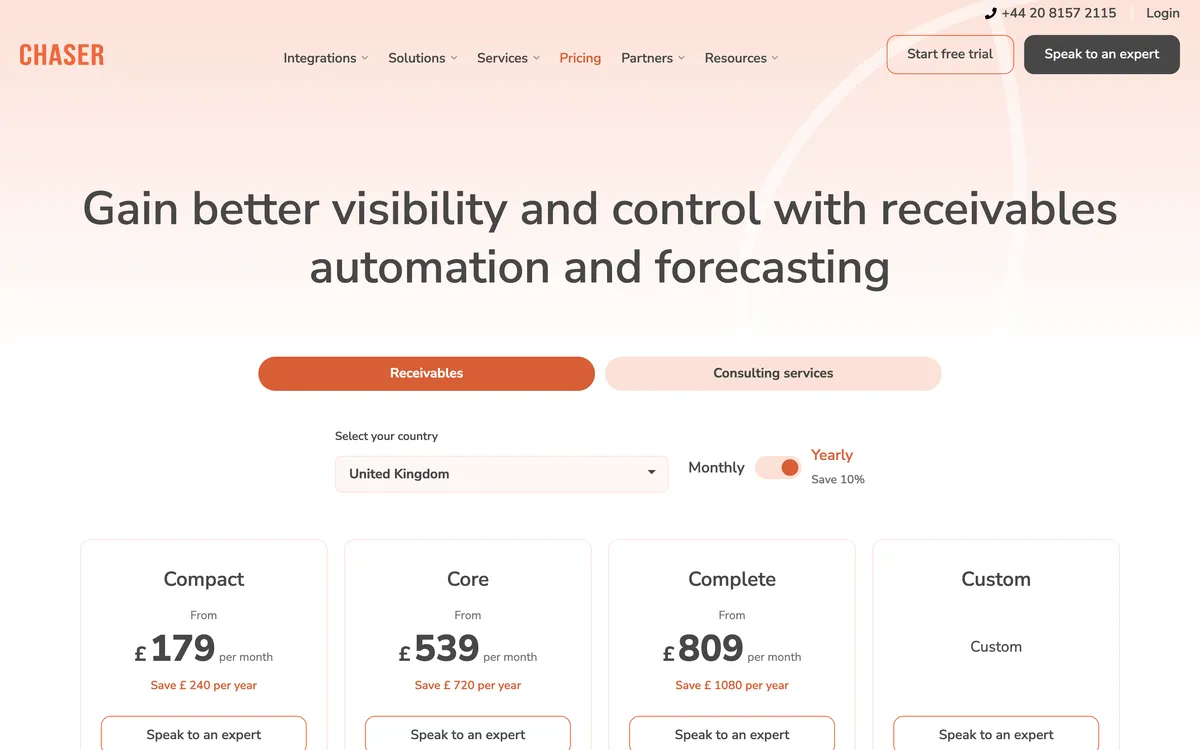
It also carries a Creditsafe report in the app, which is covered in full in the review of the best credit control software.
Limitations with Chaser. One set of rules means one statutory figure for every debtor it covers, so an export account on longer terms and a domestic account on 30 days are charged identically, though a disputed customer can be left out.
- Chaser raises no fee on a payment-plan invoice, and its help says a late fee cannot be added or updated after a part payment when written to Xero; both are invoices likely to need one.
- Statements go monthly only, on a fixed day, Compact caps the team at four users, and the entry price is tiered by company turnover rather than invoice volume.
3. Credit Hound, best for Sage-first worklists
Best for: Sage-first UK teams that chase by worklist.
Credit Hound is a credit control worklist with dispute and promise-to-pay tracking for Sage-first UK teams, from £20 per user a month on Sage Accounting.
Who should choose Credit Hound?
Choose Credit Hound if you run a Sage-first UK team that has decided the chasing matters more than the charge, and you are content to raise any statutory figure manually.
- Fits
- Sage-first UK finance teams. No revenue band published; the product is priced per user
- Regions
- Core market is the UK Sage channel, with Sage 50 connectors for UK and Ireland, the US and Canada, and pricing published in GBP, EUR, USD, CAD, AUD and ZAR
- Entry cost
- £20 per user a month on Sage Accounting; £51 for the first user then £35 each on Sage 50 and Xero; £82 then £50 each on Sage 200; the PayThem payment module is £38/mo on top.
- Rated
- 5.0 from 12 reviews on the Sage UK Marketplace; 4.5 from a single review on G2, which is too small a base to read as a quality signal
- Awards
- Not published
- Runs on
- Sage Accounting, Sage 50cloud, Sage 100cloud, Sage 200 Standard and Professional, Sage Intacct, Infor SunSystems Cloud and Xero. No QuickBooks Online connector
- Statutory late fees
- None found. No interest, late fee, surcharge or fixed-sum function appears in the vendor's product pages, cloud feature list, FAQs, product guide or Sage-hosted brochure
- Does best
- Structured dispute management with automated follow-ups, and promise-to-pay tracking with a promised-cash view
Credit Hound is a worklist for the Sage channel: nothing in its documentation computes interest, applies a fixed sum or writes a charge back to the ledger. Its strength is the controller's day rather than the charge, and that case is made on the debtor management comparison.
Limitations with Credit Hound. It documents no interest function and no ledger write-back, so a UK business using it raises every statutory figure manually.
- There is no QuickBooks Online connector, payments are a separate £38 a month module, the per-user price on Sage 200 and Xero climbs with the team, and the whole public review base is 12 reviews.
4. Kolleno, best for UK group reconciliation
Best for: UK arms of groups whose problem is reconciliation.
Kolleno is an order-to-cash platform from $650 per user a month on BusinessPay (Xero, QuickBooks, Sage Intacct); NetSuite and SAP start on Enterprise, by quote.
Who should choose Kolleno?
Choose Kolleno if you run the UK arm of a group whose real problem is reconciliation rather than enforcement, and whose budget is quoted in dollars.
- Fits
- Order-to-cash teams: BusinessPay for turnover under £1m, Business Plus £1m to £100m, Enterprise £100m to £1bn
- Regions
- London head office, founded 2020, selling internationally
- Entry cost
- $650 per user a month on BusinessPay, $545 on annual billing, minimum one user, for turnover under £1m; Business Plus $1,245 per user.
- Rated
- 4.9 from 117 G2 reviews; 5.0 from 18 Xero App Store reviews; 5.0 from 8 on Capterra
- Awards
- G2 Best Software Awards 2024
- Runs on
- NetSuite, SAP S/4HANA and Business One, Sage Intacct, Business Central, Workday, Oracle JD Edwards, Epicor, Infor, Odoo, Zuora, Xero, QuickBooks Online. Xero and QuickBooks connect on BusinessPay and Business Plus; NetSuite and SAP start on Enterprise
- Statutory late fees
- None found. No feature page or help article documents a late fee or interest calculation
- Does best
- Cash application (auto-reconciliation on Enterprise only, by quote; BusinessPay at $650 per user a month does not include it), with email remittance parsing, BAI2, NACHA and ISO 20022 bank files, match scoring and NetSuite multi-currency journal entries
- Customers
- Named on its website: Wise, Marshmallow and Laundryheap. Laundryheap's case study reports 94% of payments collected on time.
Kolleno is an order-to-cash platform whose depth sits in cash application and reconciliation, treated at length on the credit control software comparison.
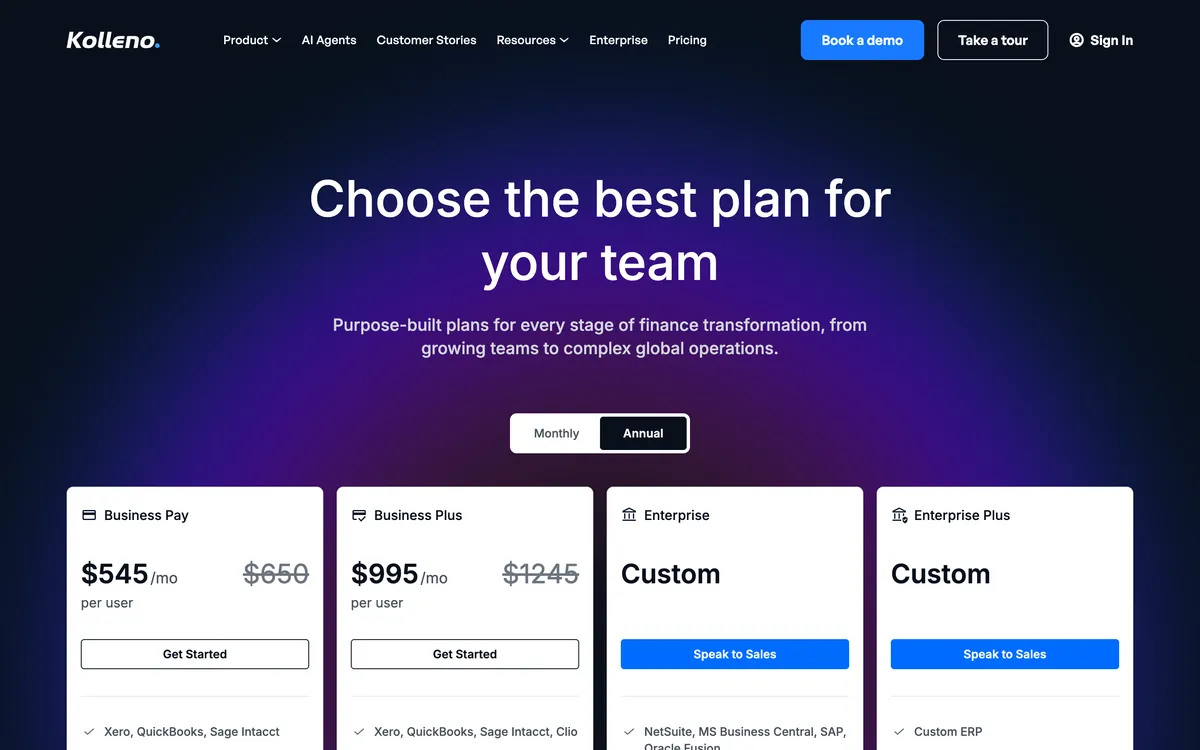
Limitations with Kolleno. Nothing in its materials computes a charge, so on a UK ledger the interest, the fixed sums and the two-block arithmetic all stay with a person however sophisticated the reconciliation gets.
- The price is the other barrier: $650 per user a month on BusinessPay without workflow automation, doubling on the second tier, in dollars rather than pounds.
- Reviewers name navigation and reporting depth as the recurring weak points.
- Kolleno's terms set a default 24-month term, renewing for 12 months with 90 days' notice, and fees are non-refundable.
5. Satago, best for credit reports and finance
Best for: Credit reports and invoice finance from one provider.
Satago is a credit reporting and chasing tool with optional invoice finance for Sage 50 and Xero teams, from £45 a month (£25 inside Sage 50).
Who should choose Satago?
Choose Satago if you run Sage 50 or Xero and want credit reports and invoice finance from the same provider that runs your chasing.
- Fits
- UK businesses in the Sage and Xero ecosystem. No revenue band published
- Regions
- United Kingdom only
- Entry cost
- £25/mo Standard and £45/mo Plus inside Sage 50, with Plus included on selected Sage 50 subscriptions; standalone £45/mo Basic, £80 Premium, £200 Platinum.
- Rated
- 4.93 from 92 Xero App Store reviews, UK listing
- Awards
- Not published
- Runs on
- Xero, Sage, Sage 50, QuickBooks, KashFlow, FreeAgent
- Statutory late fees
- Optional. Satago adds an optional late fee to reminder emails, calculated in line with statutory limits, and does not document posting it to the ledger
- Does best
- Credit reports, customer credit scores and suggested credit limits bundled into the same subscription as the chasing, with invoice finance from the same provider
Satago sells chasing and credit reports on one side and invoice finance on the other, and the £25 a month sterling figure attached to it belongs to the edition embedded in Sage 50 rather than to the app you can buy on its own.
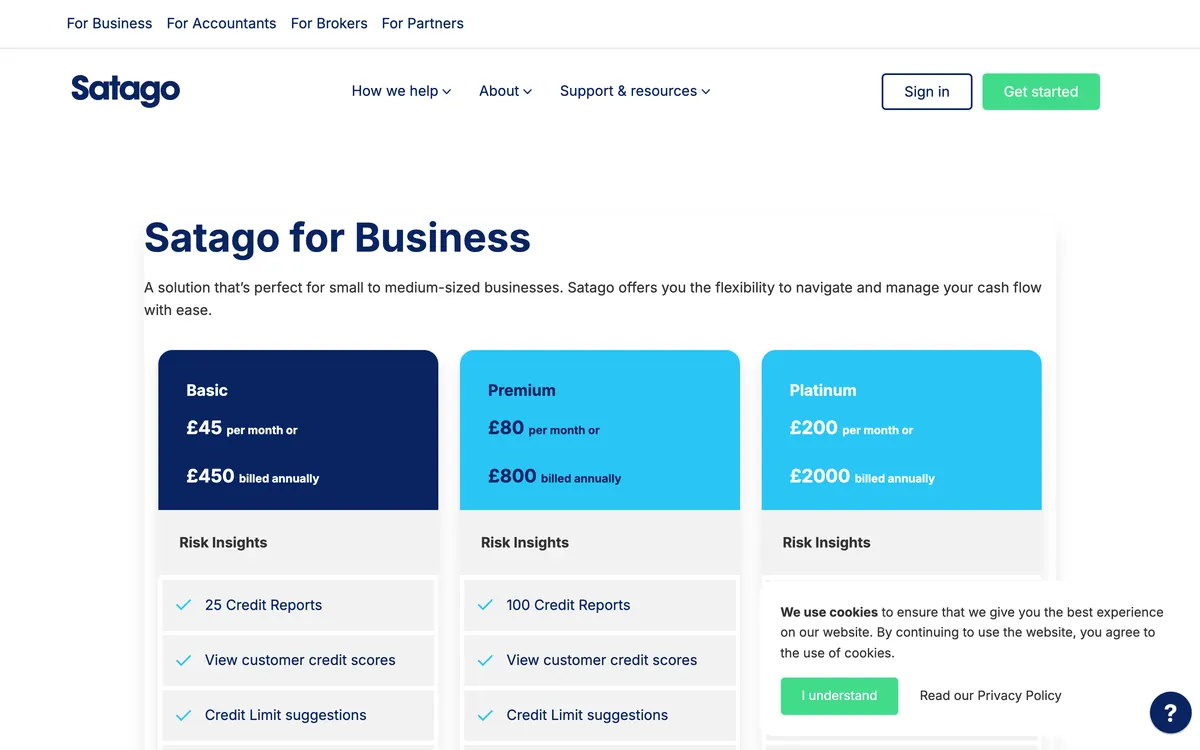
The pricing and finance sides are covered on the credit control software comparison.
Limitations with Satago. Its optional late fee is added to reminder emails, calculated in line with statutory limits, and posting it to the ledger is not documented; it holds 4.93 from 92 reviews on the UK Xero App Store.
The standalone Basic plan caps email reminders at 100 a month and does not list own-inbox sending, with your own inbox starting at the £80 Premium tier, and the whole footprint is UK-only on both the software and the lending side.
6. Upflow, best for measuring performance first
Best for: UK teams measuring collections performance first.
Upflow is a collections analytics platform for analytics-led finance teams, quoted in five tiers by gross invoice value, from up to $10m to above $100m, last published at $440 a month for Grow and $880 for Scale; current prices are hidden and must be requested.
Who should choose Upflow?
Choose Upflow if you run a UK finance team and want to know what your collections performance actually is before you decide whether a statutory charge is the lever to pull.
- Fits
- B2B finance teams that manage by metric, quoted in five tiers by gross invoice value, from up to $10m on Starter to above $100m on Enterprise
- Regions
- New York head office, Paris origin, customers in 30-plus countries
- Entry cost
- Not published. Upflow prints no figures and quotes five tiers by gross invoice value; Upflow offers a free Discover dashboard tier and a 14-day free trial on its Xero App Store listing; its pricing page lists no trial. Upflow's last published prices were $440 a month for Grow and $880 for Scale; current prices are hidden and must be requested
- Rated
- 4.8 from 235 G2 reviews; 4.5 from 15 on Capterra · Xero App Store listing
- Awards
- Not published
- Runs on
- Xero, QuickBooks Online, NetSuite, Sage Intacct, Stripe Billing, Chargebee, Zuora
- Statutory late fees
- No, via your ERP only. Upflow's own documentation points the job back to the ERP and there is no native computation
- Does best
- Collections analytics, with countback DSO against best possible DSO, collection effectiveness and an at-risk rate above 90 days
- Customers
- Named on its website: Lattice, Vercel and Front. Lattice's case study reports 99% collection with one person in AR.
Upflow measures collections rather than enforcing them, and its metric set is the reason to buy it; the Xero buying guide works through what those numbers are for.
Limitations with Upflow. Nothing here computes a base rate, prorates a period or raises a fixed sum.
- Instalment plans are absent too, leaving customer-initiated part payments and promises.
- Automatic actions run once a day on business days, sending through your own SMTP costs you open and click tracking, and its last published price ($440 a month for Grow) is now hidden and must be requested.
What happens when the statutory rate changes inside one invoice?
Statutory interest is set in six-month blocks, and an invoice that runs longer than a few months can sit in two blocks at two different rates. Applying the current rate to the whole period gives the wrong number.
Take the £12,000 invoice from the top of this page, due on 20 May and settled on 1 September, 104 days late. Forty-one of those days fall in the block that closes on 30 June and sixty-three fall in the block that opens on 1 July. Suppose the earlier block carried 12.25% and the current one carries 11.75%.
at 12.25%
at 11.75%
Charging the current rate across the whole 104 days understates the entitlement by £6.74 here, and overstates it when the rate has moved the other way.
Across a hundred invoices in the same position the gap is £674, and a charge computed on the wrong rate is a charge a customer's finance team can pick apart line by line, which is the outcome that actually costs you the money.
Paidnice and Chaser deal with this without a person. Chaser recalculates its fee daily against a Bank of England base rate type, which keeps a moving rate current, though every customer sits under the same set of late-fee rules.
Paidnice's base rate toggle applies the base rate plus your own percentage and uses the correct base rate for each period an invoice spans. Credit Hound and Kolleno document no interest mechanic at all, Upflow points the job back to your ERP, and Satago adds its fee only to the reminder email.
What must a late-fee record look like if anyone audits it?
A statutory charge is worth what you can evidence, which means a document on the ledger rather than a sentence in a chasing email.
An email says a customer owes £402. It does not enter their accounts payable, it does not appear in their payment run, and it leaves no dated record on your side of what was charged, on which balance, at which rate.
A charge raised as an invoice does all four, and it can be aged, reported and reconciled like anything else on the ledger.
The waiver matters as much as the charge. A fee you can point to is a fee you can drop deliberately, in writing, in exchange for payment this week.
Of the six, Chaser syncs the fee as a line item, which is Xero-only. Paidnice raises the charge on the ledger as Draft or Approved, so a controller can review the document before the customer sees it.
Credit Hound's documentation describes no route for writing a charge back to the ledger, and Upflow's points the job to your ERP, so on both the record is whatever your accountant builds manually.
How much does UK credit control software cost, in pounds?
Four of the six print a sterling entry price: Paidnice at £49 (US$69), Chaser at £199, Credit Hound at £20 per user a month on Sage Accounting and Satago from £45 (£25 inside Sage 50). Kolleno prints $650 per user. Upflow prints nothing at any tier.
The metric decides the bill more often than the headline does. Credit Hound and Kolleno charge per seat, so a three-person credit control function triples the invoice before anything is chased. Chaser steps by company turnover, so growth moves you up a tier whether or not your ledger got harder. Paidnice steps by invoice volume on a flat tier.
Satago's £25 sterling figure belongs to a product a Xero business cannot buy. The £25 tier is the edition embedded in Sage 50, and Sage says Plus is included with selected Sage 50 subscriptions without publishing which ones, so the real cost sits somewhere between nothing and £45 until an account manager tells you.
Set any of those figures against the £502 of statutory entitlement on the single £12,000 invoice at the top of this page, and the arithmetic on the subscription stops being the hard part of the decision.
Which UK credit control software fits your use case?
| Use case | Start with | Why |
|---|---|---|
| Xero or QuickBooks Online, statutory interest per customer group | Paidnice | The base rate toggle uses the correct rate for each period and posts the charge to the ledger |
| Reminders and statements only, no charge | Paidnice or Chaser | Both send reminders and statements; Paidnice on any schedule, Chaser monthly on a fixed day |
| Creditsafe credit checks in the same tool as the chasing | Chaser | Creditsafe report and monitoring inside the app; credit checks sold by credit on any plan; plans from £199 a month |
| Sage 50 or Sage 200 team that wants a worklist | Credit Hound | Dispute and promise-to-pay tracking from £51 for the first user on Sage 50 and £82 on Sage 200 (£20 per user on Sage Accounting), with no statutory charge |
| Invoice finance alongside the chasing | Satago | Credit reports and finance from one provider, from £45 a month (£25 inside Sage 50) |
| Collections reporting for a larger finance team | Upflow | Countback DSO and collection effectiveness, with no price published |
What do UK buyers ask before they shortlist?
What can I charge on a late invoice in the UK?
On a B2B invoice, interest at 8% a year above the Bank of England base rate, which is 11.75% at the mid-2026 base rate of 3.75%, plus a fixed sum of £40, £70 or £100 set by the size of the debt, plus reasonable recovery costs above that fixed sum.
Does my contract have to mention late payment interest?
No, a contract does not have to mention late payment interest. The entitlement under the 1998 Act applies where the contract is silent, so a supplier who never wrote a late payment clause can still charge.
Can the statutory rate change while one invoice is overdue?
Yes. The rate is set in six-month blocks, so an invoice overdue for several months can span two blocks at two rates, with the charge prorated across each. Chaser recalculates daily against its base rate type; Paidnice applies the correct base rate for each period, and the other four leave that split to you.
Is the fixed sum charged once per customer or once per invoice?
The fixed sum is charged once per invoice. Twelve overdue invoices of £4,000 each carry twelve fixed sums of £70, which is £840, against a single £100 on one invoice for the same £48,000.
Which of these six computes UK statutory interest without a person?
Paidnice and Chaser compute it. Chaser runs one set of late-fee rules, across the account or for selected debtors, not tied to schedules, raises no fee on payment-plan invoices, and its help says a late fee cannot be added or updated after a part payment when written to Xero; Paidnice runs it as a policy under a customer group and raises the charge on the ledger as Draft or Approved.
Credit Hound and Kolleno document no interest function, Upflow points the job back to your ERP, and Satago adds an optional late fee to its reminder emails without documenting a ledger charge.
What do these six cost in pounds?
Chaser £199 for turnover under £4m; Credit Hound £20 per user a month on Sage Accounting and £51 plus £35 per extra user on Sage 50 and Xero; Kolleno $650 per user; Paidnice £49 (US$69); Satago from £45 a month (£25 inside Sage 50); Upflow's last published prices were $440 a month for Grow and $880 for Scale; current prices are hidden and must be requested.
Check current pricing with the vendor.
Is statutory interest about to become mandatory?
Statutory interest may become mandatory. The Commercial Payments Bill, introduced to the House of Lords in May 2026, would stop commercial contracts from contracting out of statutory interest. It is not law, implementation is not expected before 2027, and the bill's stage is worth checking before you build a policy around it.
For the wider shortlist across markets, the credit management software comparison sets out six tools by size, ledger and price.
Next in this guide
Buyer's guide
Credit control software for Xero
The five decisions that produce a shortlist, in the order they should be taken.
Debtor management
Best debtor management software UK
The debtor workspace, statutory interest and credit risk, compared.
UK law
Late payment fees in the UK
The complete guide to the law, the rate and what is changing.
Alternatives
Best Chaser alternatives
What else raises a charge, if Chaser's one set of late-fee rules is the sticking point.
Sources
15 sources, checked by Julie Turnbridge on November 6, 2026
- Late Payment of Commercial Debts (Interest) Act 1998 legislation.gov.uk/ukpga/1998/20/contents
- Bank of England base rate bankofengland.co.uk/monetary-policy/the-interest-rate-ban...
- GOV.UK gov.uk/late-commercial-payments-interest-debt-recovery/ch...
- GOV.UK gov.uk/late-commercial-payments-interest-debt-recovery/cl...
- Xero App Store apps.xero.com/uk/app/paidnice
- Capterra capterra.co.uk/software/254868/paidnice
- Xero App Store apps.xero.com/uk/app/chaser
- G2 g2.com/products/chaser/reviews
- G2 g2.com/products/credit-hound
- G2 g2.com/products/kolleno/reviews
- Xero App Store apps.xero.com/uk/app/kolleno
- Capterra capterra.co.uk/software/227932/Kolleno
- G2 g2.com/products/upflow-upflow/reviews
- Capterra capterra.co.uk/software/193097/Upflow
- Xero App Store listing apps.xero.com/uk/app/upflow

