The best payment gateways for MSPs in 2026 are compared on the published cost of moving a dollar. Paidnice is first as the reminder and late-fee layer that works with the MSP's gateway through Stripe, Pinch Payments or CloudDepot, from £49 (US$69) a month. Alternative Payments prints the fullest rate card, from US$199 a month, then FlexPoint and ConnectBooster.
| Tool | Best for |
|---|---|
| Paidnice | an MSP that has chosen a gateway and wants the late fee and reminder layer on top, from £49 (US$69) a month |
| Alternative Payments | an MSP that wants the full monthly cost calculated before a sales call, from US$199 a month up to $50,000 of monthly processing |
| FlexPoint | an ACH-heavy MSP that wants per-state card surcharging, with ACH from $0.25 a transaction |
| ConnectBooster | an MSP already inside the ConnectWise and Kaseya stack, on a quoted price |
Every figure here was read off the vendor's own pricing page.
What a payment gateway for MSPs is (and what it is not)
A payment gateway for MSPs takes a client's card or ACH payment against an invoice the PSA raised, settles it through a processor and writes the payment back to the PSA and the ledger, so the invoice closes in both systems.
- Takes the payment: card and ACH, often through a branded client portal with autopay.
- Prices each dollar:
- Recovers card cost: surcharging where state law and card network rules permit, never on debit.
- Writes back: the payment posts to ConnectWise, Autotask, HaloPSA, SuperOps or Kaseya BMS, and to QuickBooks or Xero.
It is not the merchant processor. At ConnectBooster the BNG gateway and the merchant processor bill separately.
It is not a collections tool. None of the three gateways here computes a late fee or interest, so the clause in your agreement goes unenforced unless a separate layer such as Paidnice posts the charge to the ledger.
It is not a payment plan scheduler either. Alternative Payments sells installments as financing, with a 3.0% to 7.0% fee paid by the client and the MSP funded in full upfront.
It is not the PSA or the ledger. The PSA raises the invoice and writes it into the accounting system; the gateway moves the money between them.
How this list was put together
This list helps an MSP compare what each gateway publishes about the cost of moving a dollar from client to bank.
| What we checked | Where the evidence came from |
|---|---|
| Subscription, and what it is banded on | Each vendor's pricing page |
| Card, AMEX and ACH rates | Vendor rate cards, in USD, without conversion |
| Gateway and card dispute fees | Vendor rate cards and order forms |
| Card surcharging | Vendor surcharging documentation |
| PSA path: ConnectWise, Autotask, HaloPSA, SuperOps or Kaseya | Vendor integration pages |
| Rating and review count | The Xero App Store or G2 |
What does an MSP pay to get paid?
The subscription is the smallest number on this page. An MSP moving $80,000 a month at the published card rates below pays more in card margin in a single month than the most expensive software here costs in a year.
Six line items make up the real price of taking a payment: the software subscription, the card rate as interchange plus a margin, the ACH cost per transaction, the gateway fee, the dispute cost when a client charges back, and the contract term that decides how long you carry the other five.
Every product here will move money. What separates them is how much of your money each one keeps on the way through, and how much of that you can establish before you book a call.
The other MSP receivables question, what to do about a client who does not pay, is a different problem with a different shortlist, and it is covered on the AR software guide for MSPs.
What to look for on a rate card:
- Four numbers you can add up: the subscription, the card rate, the ACH cost per transaction and the contract term, all four before signature.
- The ACH path, priced. ACH is the cheapest rail an MSP has, and the per-transaction cost plus the same-day allowance decide how much of the book can be moved onto it.
- A surcharging position in writing: whether the platform surcharges at all, whether the compliance logic is per state, and whether it refuses on debit.
- Write-back into the PSA and the ledger, so a payment closes the invoice in both systems without anybody keying it twice.
- A portal a client will use, because a rate card only applies to money that actually moves.
How do the four rate cards compare?
 |
 |
 |
 |
|
|---|---|---|---|---|
| Best for | The late fee and reminder layer after a gateway | US and Canadian MSPs wanting a fully published rate card | ACH-heavy MSPs on HaloPSA or SuperOps wanting surcharging | MSPs already inside the ConnectWise and Kaseya stack |
| Subscription from | US$69/mo | US$199/mo | US$249/mo | Not published |
| Subscription banded on | Invoice volume and team size | Monthly processing, to $50k then to $100k, custom above | Monthly processing, to $50k, to $100k, then unlimited | Not published |
| Card rate | Set by Stripe or Pinch Payments | 2.9% + $0.30 | 3.0% or Interchange+, margin not published | Not published, billed by your merchant processor |
| AMEX | Set by your processor | 3.5% + $0.30 | Not published | Not published |
| ACH per transaction | Set by your processor | None on the pricing page | $1.00 on Starter, $0.50 on Growth; Plus custom ($0.25 last seen in a FlexPoint blog) | Invoiced separately |
| Same-Day ACH | Set by your processor | Not published | Included monthly allowance on every tier | Not published |
| Gateway fee | None; processing runs on Stripe or Pinch Payments | None separate | Not published | BNG gateway fee, billed on its own |
| Card dispute | Set by your processor | $25 | Not published | Not published |
| Card surcharging | None found | Yes, where state law permits, never on debit | Yes, per-state compliance logic | Not documented |
| Bills a month | Two: this, and your processor | One | Not published | Three, plus merchant processing |
| Contract term | Not published | Not published | No long-term contracts per FlexPoint; Order Form sets the term | Not published |
| AI | Advanced Reads customer replies, drafts answers and follow-up actions (like PO updates) for your approval; MCP server for Claude, ChatGPT and other agents | None No shipped AI feature found | Basic AR Agents run reminder sequences and pause when a client replies | None No AI in the billing product |
| Rated (source, count) | 5.0 (84, Xero App Store) | 4.7 (11, G2) | 4.8 (6, G2) | 4.4 (28, G2) |
"Not published" means the vendor prints no figure for that line. "Not documented" means the vendor does not document the behavior. "None found" means nothing in the vendor's published material addresses that line. Rates are the vendor's own published figures, in USD, without conversion.
The four tools in five checked facts
- Three of the four print a monthly price: Paidnice from £49 (US$69), Alternative Payments from US$199 and FlexPoint from US$249. ConnectBooster quotes.
- The published prices grow with different things: invoice volume (Paidnice) and payment volume (Alternative Payments and FlexPoint).
- One of the four applies a late fee itself: Paidnice (per customer group).
- All four connect to both Xero and QuickBooks Online.
- AI that handles collections work or customer replies: Paidnice. AI that does not handle replies: FlexPoint. No AI in receivables: Alternative Payments and ConnectBooster.
We checked each tool's own pricing, integration and help pages. "None found" in the data means the vendor's pages do not show the feature.
1. Paidnice, best for fees on any gateway
Best for: An MSP that has chosen a gateway and wants the reminder and late-fee layer on top, working with Stripe, Pinch Payments or CloudDepot, from £49 (US$69) a month.
What is Paidnice best for?
For an MSP that has already chosen a gateway and still has a book of invoices nobody is paying, where the money is lost to unbilled staff time rather than to card margin.
- Fits
- MSPs on Xero or QuickBooks Online of any size up to $50m a year, or 50,000 invoices a year, with or without a dedicated bookkeeper
- Regions
- United States, Canada, United Kingdom, Australia, New Zealand, South Africa
- Entry cost
- £49 (US$69) a month on Essentials, priced on invoice volume rather than money processed: 150 invoices, 600 emails and up to 2 team members. Pro from £74 (US$99) a month, unlimited users, no per-seat fee. Card and ACH costs are your processor's and sit outside this figure
- Rated
- The deepest verified base on this page: 5.0 across 84 Xero App Store reviews, plus 4.9 from 14 on Capterra
- Awards
- Xero Global Small Business App of the Year 2025 and NZ Small Business App of the Year 2026
- Runs on
- Xero, QuickBooks Online, Stripe, Pinch Payments, CloudDepot, HubSpot, Pipedrive, Zapier. Newer ledgers such as Rillet, Campfire, Digits, DualEntry, Puzzle, Accounting Seed and Odoo on every plan through the closed testing program. NetSuite, Sage Intacct, MYOB, Sage Accounting and Dynamics 365 Business Central on the Custom plan. No PSA connector of its own
- Late fees and interest
- Yes. Two charge types on the same customer group, an invoice late fee and a statement interest charge, both raised on the ledger as Draft or Approved. Policies sit under customer groups, so several rules run at once
- Does best
- Enforcement that lands on the ledger: reminders, late fees, interest, statements, payment plans (on Pro) and escalation, all routed per customer group
Paidnice moves no money of its own: cards and ACH run on Stripe or Pinch Payments, so whatever rate card you negotiated with a processor is the rate card you keep. What it adds is the part a gateway leaves alone, which is the invoice nobody has paid yet.
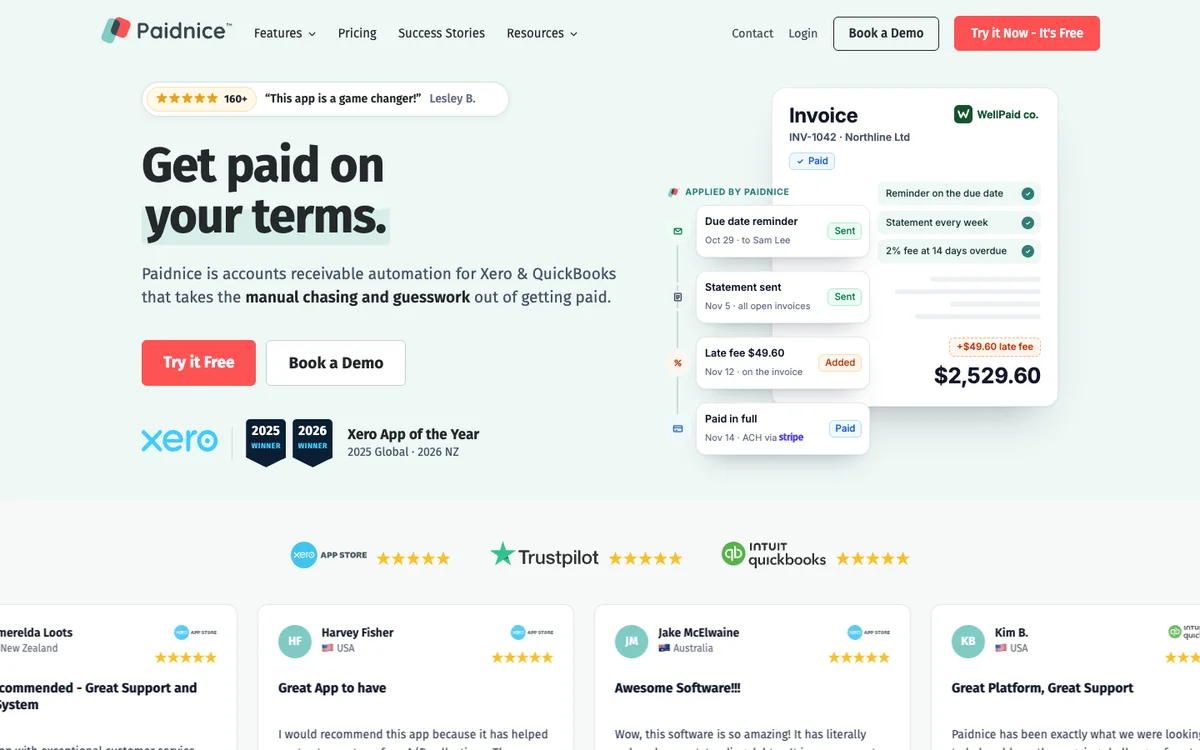
Reminders run per customer group by email and SMS from the MSP's own authenticated domain on Pro and above, statements go on any schedule including consolidated parent accounts, and a late fee or interest charge is posted onto the QuickBooks Online or Xero ledger rather than shown in a portal.
The wider MSP field is compared in the AR software guide for MSPs.
Limitations with Paidnice. It moves no money itself, so nothing on the rate card above belongs to it: an MSP that wants one vendor for processing and chasing is buying two products and paying two bills.
No card surcharging function is documented, which on this page is the expensive omission. There is no PSA-native invoice view, Xero, QuickBooks Online and newer ledgers such as Rillet and Campfire (closed testing) are on every plan while Sage Accounting and other ERPs need the Custom plan, and the entry tier covers two team members.
2. Alternative Payments, best for PSA gateway
Best for: US and Canadian MSPs that want a native PSA gateway with a published price and a published fee schedule.
What is Alternative Payments best for?
For a US or Canadian MSP that wants invoicing, card, ACH and reconciliation as one native product wired straight into ConnectWise, Autotask, HaloPSA or SuperOps.
- Fits
- US and Canadian service businesses, MSPs among four named verticals. The entry tier is priced for up to $50,000 of monthly processing and the second tier to $100,000
- Regions
- United States and Canada only. Canada is a reduced product: Quebec is excluded, and financing and collections are unavailable
- Entry cost
- US$199/mo up to $50,000 of monthly processing, $499/mo up to $100,000, custom above. Cards 2.9% + $0.30, AMEX 3.5% + $0.30, no ACH fees on the pricing page, card dispute $25
- Rated
- 4.7 from 11 G2 reviews. No Capterra listing found
- Awards
- None found
- Runs on
- ConnectWise PSA, Datto Autotask, HaloPSA, SuperOps. QuickBooks Online and Desktop, Xero, Sage Intacct, NetSuite, Dynamics 365 and Business Central, Zoho Books, FreshBooks. ConnectWise CPQ, ScalePad Quoter, QuoteWerks, Datagate. Kaseya BMS and Syncro absent
- Late fees and interest
- None found. Nothing in the help center or on the receivables page calculates, posts or accrues a late fee or interest. The design is autopay and reminders first, then a person
- Does best
- Collections Assist: submit an overdue invoice from the dashboard and their team contacts the client by email and by phone, on success-based pricing with no retainer, escalating to a partner agency if it fails
- Customers
- Named on its website: TeamLogic IT, Sage IT and CMIT Solutions Idaho. TeamLogic IT Utah Valley North's case study reports 40% of invoices paid on creation.
Alternative Payments is the only vendor on this page whose monthly bill can be calculated in full before a sales call: a subscription banded by processing volume, a card rate, an AMEX rate, no ACH fees on the pricing page and a $25 card dispute cost, all printed.
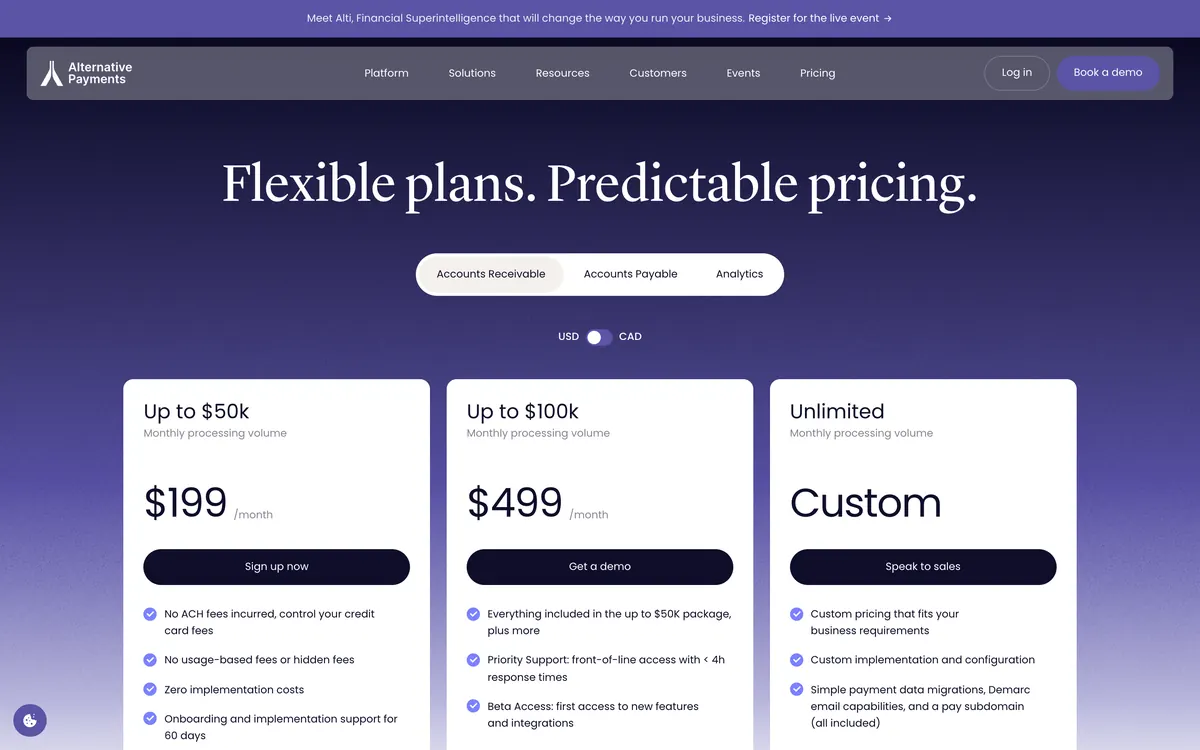
Its answer to an unpaid invoice is people rather than penalties. Autopay rules can trigger on days past due, days before due, days past creation, agreement or amount, and customers self-enrol. When those fail, Collections Assist puts a human on the phone.
Installments are a financing product: 30 to 150 days in equal steps, with the credit risk carried by the vendor.
Limitations with Alternative Payments. Contract length is the one number missing from an otherwise complete rate card. North America only, with Quebec, financing and collections all absent from the Canadian product.
No late-fee or interest engine, so nothing here enforces the 1.5% a month clause your agreement already carries. Statements are undocumented. Eleven G2 reviews is a thin base, and one of them reports payouts marked paid against transactions that had failed, which lands directly on the reconciliation claim.
3. FlexPoint, best for published ACH pricing
Best for: US MSPs on HaloPSA or SuperOps that want published ACH pricing and card surcharging.
What is FlexPoint best for?
For a US MSP that wants the broadest PSA coverage here, compliant card surcharging, and a per-transaction ACH cost it can compare before booking a call.
- Fits
- US MSPs. Tiers are banded by monthly processing: up to $50,000, up to $100,000, then unlimited
- Regions
- United States. No published support for the United Kingdom, Canada, Australia, New Zealand or South Africa, and every price and rail on the site is a US one
- Entry cost
- Starter $249 a month up to $50,000 of monthly processing, Growth $550 up to $100,000, Plus quoted. ACH at $1.00 on Starter and $0.50 on Growth, cards at 3.0% or Interchange+ with no published margin over interchange
- Rated
- 4.8 from 6 G2 reviews, which is too small a base to read as a quality signal; the Capterra listing carries no reviews at all
- Awards
- None found
- Runs on
- ConnectWise PSA, Autotask, HaloPSA, SuperOps. QuickBooks Online and Desktop and Xero as standard; Sage Intacct, NetSuite and Dynamics 365 Business Central on a paid tier. Rewst, Quoter, QuoteWerks, ConnectWise CPQ, Datagate. Kaseya BMS and Syncro absent
- Late fees and interest
- No, via your ledger only. FlexPoint's own guide states that QuickBooks late fee settings sync automatically, so the ledger calculates the charge and FlexPoint displays and collects it
- Does best
- Compliant US card surcharging with per-state logic, plus Same-Day ACH with a published monthly allowance on every tier
- Customers
- Named on its website: CharTec, Mainstay Technologies and tekRESCUE. tekRESCUE's case study reports 20 hours a month saved.
FlexPoint publishes the number that matters most to an MSP with a large book of recurring invoices: ACH at $1.00 per transaction on Starter and $0.50 on Growth (Plus ACH is Custom priced; the $0.25 rate was last seen in a FlexPoint blog), with a Same-Day ACH allowance included at every tier.
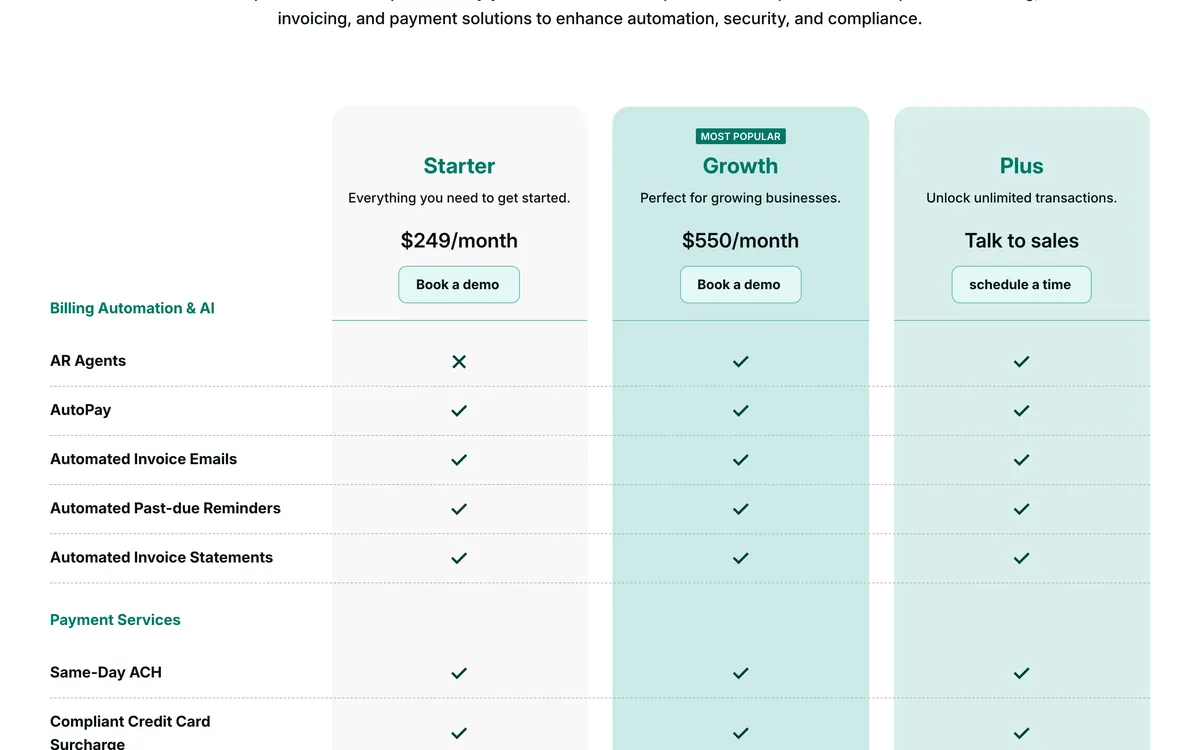
It also reaches the HaloPSA and SuperOps shops the incumbent cannot, and its Rewst integration puts billing inside the automation layer many MSPs already orchestrate everything else with.
Surcharging is where it separates itself, and it is built as compliance logic rather than a flat toggle: the platform applies the fee against current state regulations and card network rules per transaction.
Its 2026 shipment is AR Agents, drafting collection emails from each account's history and balance and placing AI voice calls only after email has run, each capability opt-in behind a pending-approvals queue.
Limitations with FlexPoint. Interchange+ hides the card margin, so the published subscription and ACH rates tell only part of the cost story. An MSP with no late-fee logic in QuickBooks or Xero gets none from FlexPoint.
Payment plans are a financing product with unpublished partner terms rather than an installment scheduler. Custom portal domain and GL Connect are add-ons, premium ledgers are tier-gated, and FlexPoint says it has no long-term contracts while its Order Form sets the term.
4. ConnectBooster, best for ConnectWise and Kaseya
Best for: MSPs already inside the ConnectWise and Kaseya stack.
On a quoted price
What is ConnectBooster best for?
For an MSP on ConnectWise or Kaseya BMS that wants a mature client payment portal from a vendor it already buys from, and can live with a quoted price.
- Fits
- MSPs already inside the ConnectWise and Kaseya ecosystem. No revenue band and no processing band published
- Regions
- US-based support is stated on the current product page. The vendor's own country page listing the UK, Ireland, Australia, New Zealand and the Nordics was deleted when the site moved onto Kaseya, so current coverage outside North America is unconfirmed
- Entry cost
- Not published, quote only. The cost arrives as three separate bills: the software, the BNG gateway fee and merchant card processing, each on its own timetable
- Rated
- 4.4 from 28 G2 reviews; 3.8 from 12 on Capterra
- Awards
- G2 Leader in Small Business and High Performer
- Runs on
- ConnectWise Manage and PSA, Datto Autotask, Kaseya BMS. QuickBooks Desktop and Online, Xero, Sage Intacct, Dynamics GP. Quoter, ConnectWise Sell, Zomentum, QuoteWerks QuoteValet, GreatAmerica, Datagate, CloudRadial. HaloPSA, SuperOps, Syncro and NetSuite absent
- Late fees and interest
- None found. No late fee, interest or surcharge function appears anywhere across the product help documentation, whose own blog treats late penalties as an agreement drafting exercise
- Does best
- Autopay depth: organization-level rules, an automatic approval process, expiring-card handling, and the deepest reporting suite in this comparison
- Customers
- Named on its website: Blackline IT, Astute Technology Management and NEXTGen IT.
ConnectBooster is the one vendor here whose cost case is a bundle rather than a rate card. It has been in the category since 2010, was acquired by Kaseya in 2022, and now ships as a component of Kaseya 365 Ops, so for an MSP already buying that bundle the marginal software cost can be close to nothing.
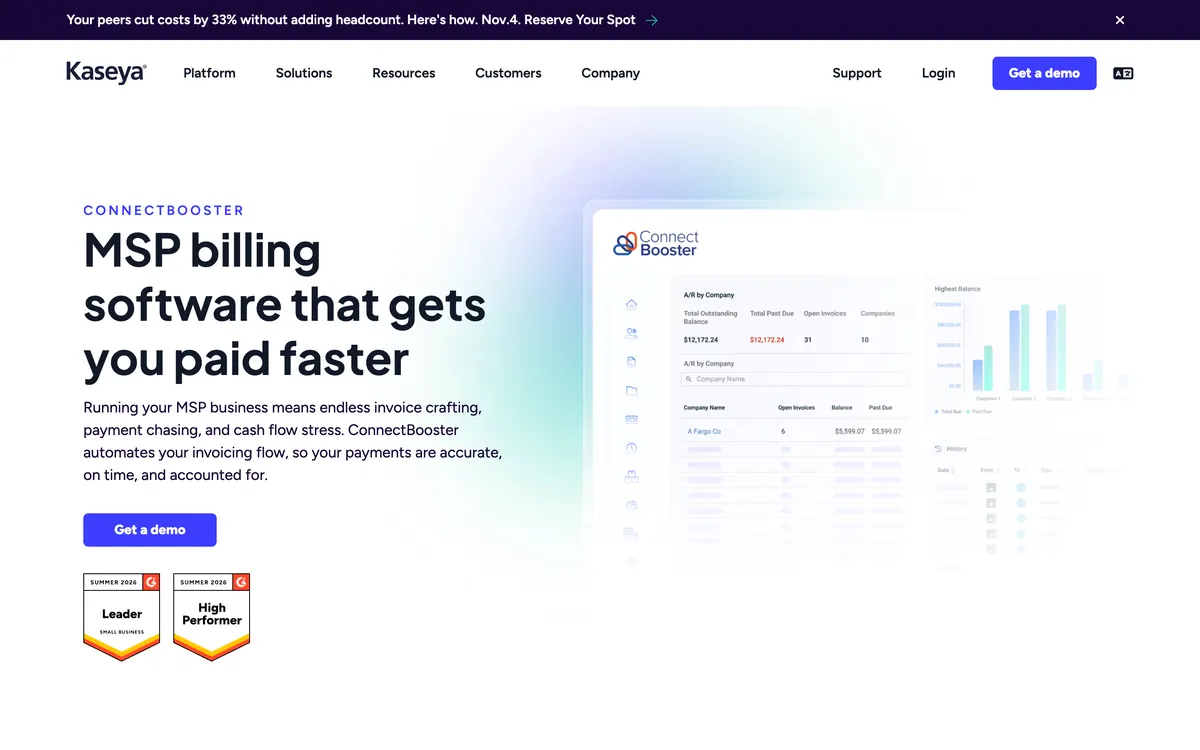
The portal is branded and mature: clients view and pay around the clock, see billing history, and organizations can be put behind two-factor authentication.
Limitations with ConnectBooster. The cost is genuinely opaque: an unpublished subscription and three separate invoices. The reviews are the weakest here and the complaints are structural rather than cosmetic, naming portal usability, sync duplicates creating duplicate entities, gateway timeouts and a transaction limit that blocked a payment.
No late fees, no interest, no installment plans and no credit data. Every ConnectBooster URL redirects to a single Kaseya product page, so the geographic evidence, the reminder mechanics and the roadmap are all unverifiable from public sources.
What does $80k a month cost through each gateway?
The same book of business is priced through each vendor, with every unpublished figure left as Not published rather than estimated.
The assumptions. $80,000 collected a month across 40 invoices averaging $2,000. Sixty per cent of the value arrives by card, so 24 card transactions worth $48,000, and forty per cent by ACH, so 16 ACH transactions worth $32,000. No surcharging, no disputes, no same-day requests.
| At $80,000 a month | Paidnice | Alternative Payments | FlexPoint | ConnectBooster |
|---|---|---|---|---|
| Subscription tier | $69.00 | $499.00 | $550.00 | Not published |
| Card cost on $48,000 | Set by your processor | $1,399.20 | Not published | Not published |
| ACH cost on $32,000 | Set by your processor | $0.00 | $8.00 | Not published |
| Monthly total | $69.00 plus processing | $1,898.20 | Not published | Not published |
Card cost is 2.9% of $48,000 plus $0.30 on each of 24 transactions. FlexPoint's ACH line is $0.50 on each of 16 transactions, the published rate for the $50,000 to $100,000 tier.
Run the same mix at two other volumes and the shape becomes clearer. At $30,000 a month, 15 invoices, Alternative Payments drops to the $199 tier and the card cost on $18,000 falls to $524.70, for $723.70 in total.
At $150,000 a month, 75 invoices, the Alternative Payments subscription moves to a custom quote and stops being publishable, while the card cost on $90,000 at the published rate reaches $2,623.50.
FlexPoint's ACH line moves in the other direction, and it is the most useful figure on this page. Six transactions at $1.00 is $6.00 at $30,000. Sixteen at $0.50 is $8.00 at $80,000.
Thirty at $0.25, the rate last seen in a FlexPoint blog, is $7.50 at $150,000, and Plus ACH is Custom priced. Multiply your collections by five and the ACH cost stays inside two dollars of where it started, because the per-transaction rate steps down by tier faster than the transaction count climbs.
First, at the published rates the card margin on $80,000 a month is roughly $1,400, near enough $16,800 a year, against a subscription of $499 a month.
Second, the same money moved by ACH costs single-digit dollars at FlexPoint and nothing at Alternative Payments, so the card-to-ACH mix moves the bill by more than the choice of vendor does.
Third, two of the four cannot be modeled at all from public sources.
Where is surcharging legal, and what does it cap at?
Surcharging is the only line on this page that moves the card cost to zero rather than reducing it, which is why it dominates the economics for an MSP with heavy card volume. It also puts a new line in front of your client, so read the agreement before switching it on.
- The card networks. A surcharge may never exceed your own cost of acceptance, and each network sets a ceiling above that: Visa caps a US credit card surcharge at 3% and Mastercard at 4%, so a merchant taking both is bound by the lower figure. The networks also require advance notice, commonly 30 days, to them and to your acquirer before you begin.
- Federal debit rules. Debit and prepaid card transactions cannot be surcharged in the United States at all, whatever your state permits. A platform that cannot tell a debit card from a credit card at authorization cannot surcharge safely.
- State law. A small number of US states and territories still prohibit credit card surcharging outright, Connecticut, Massachusetts and Puerto Rico among them, and several others regulate how the price has to be displayed rather than banning the practice. That list has moved repeatedly through litigation, so confirm the position for every state you bill into rather than only for the state you sit in.
Canada is a separate regime again. Surcharging has been permitted since October 2022 under the card network settlements, capped at 2.4%, and Quebec's Consumer Protection Act prohibits it for consumer transactions, which is one of several reasons the Canadian products in this comparison are reduced.
A surcharge adds a percentage to the card price. A cash discount reduces a single posted price for customers who do not use a card.
Dual pricing posts both prices side by side. They are regulated and disclosed differently.
On the four here, FlexPoint applies the surcharge per transaction rather than as a flat toggle. Alternative Payments permits surcharging where state law allows and never on debit.
ConnectBooster does not document its position. Paidnice documents no surcharging function at all. None of that is legal advice; confirm with your own counsel before you enable it.
Which PSA writes the payment back, and how fast
On a payments page the PSA question is about the return leg: how quickly the payment shows against the invoice, in the ledger and in the PSA.
- ConnectWise PSA. Alternative Payments, FlexPoint and ConnectBooster all connect natively, so the payment posts back into the system that raised the invoice. This is the one PSA every gateway here supports.
- Datto Autotask. The same three natives.
- HaloPSA and SuperOps. Alternative Payments and FlexPoint only. ConnectBooster documents neither.
- Kaseya BMS. ConnectBooster alone. No tool here documents a Syncro connector.
- QuickBooks Desktop. Alternative Payments, FlexPoint and ConnectBooster. Paidnice has no QuickBooks Desktop connector.
- Sage Intacct, NetSuite and Dynamics. Alternative Payments carries them as standard, FlexPoint puts them above the entry tier, and Paidnice reaches them on its Custom plan as a build.
Paidnice takes the other route and connects to no PSA at all, because the PSA has already written the invoice into QuickBooks Online or Xero. On a payments page that costs you the PSA write-back.
Settlement timing is the least published figure in this whole category. FlexPoint prints a Same-Day ACH allowance on every tier, which is the only settlement-speed commitment any vendor here makes in public. The other three state none, so ask for funding times in writing and ask what happens to them on a weekend.
How long is the contract, and how do you exit?
Alternative Payments does not print a term at all. FlexPoint says it has no long-term contracts; its Order Form sets the term.
ConnectBooster is quote-only, and Kaseya's agreements have historically auto-renewed for the greater of the expiring term or three years, so assume a multi-year ask and read the order form before the demo rather than after it.
Alternative Payments bills once. FlexPoint prints its subscription and its ACH rate, with Interchange+ leaving the card margin unstated until the first statement.
The exit question that actually matters on a gateway is the stored mandate. Autopay enrolments and stored cards live with the processor rather than with the software, so changing vendor usually means asking every client who has ever set up autopay to set it up again. Get the answer in writing before you sign, not when you leave.
Tools without a numbered entry
Two names on most MSP shortlists carry no numbered entry, because neither publishes a price, a rating or documented capabilities.
WisePay is part of the ConnectWise family and processes card and ACH inside the ConnectWise suite with ledger syncing, which is its whole appeal for a shop standardized on ConnectWise. Its pricing, contract terms and portal customization are not documented.
Benji Pays is an automated payments and billing portal aimed at smaller MSPs and marketed on a flat monthly fee. The fee, the PSA coverage and the reconciliation behavior are not documented.
Stripe and QuickBooks Payments belong in a different row again. Neither was built for MSP billing and neither publishes a PSA integration, so both are rails rather than shortlist entries. Paidnice uses Stripe as one of its rails and adds the enforcement on top.
Which payment gateway for MSPs fits your use case?
Start from what costs you most.
| Use case | Start with | Why | Watch out |
|---|---|---|---|
| Pricing the whole monthly bill before a sales call | Alternative Payments | Subscription, card, AMEX, ACH and dispute fees all published, from US$199 a month | Contract term not published; North America only |
| A large ACH book on HaloPSA or SuperOps | FlexPoint | ACH from $0.50 a transaction on Growth and per-state surcharging | Card margin not published |
| Already buying Kaseya 365 Ops, or running Kaseya BMS | ConnectBooster | Bundled client portal with native Kaseya BMS write-back | Quoted price across three separate invoices |
| A gateway is chosen, but invoices still go unpaid | Paidnice | Late fees, interest and reminders on the QuickBooks Online or Xero ledger, from £49 (US$69) a month | Moves no money; no card surcharging |
Questions MSPs ask about payment costs
What is the best payment gateway for MSPs?
Alternative Payments is the best fit on published cost, because it is the only vendor here that prints a subscription, a card rate, an AMEX rate, an ACH cost and a dispute fee, so the monthly total can be calculated before a call: from US$199 a month up to $50,000 of processing.
Alternative Payments documents no late-fee or interest engine, so consider Paidnice for the chasing around it.
Where ACH volume is the bulk of the book, FlexPoint publishes $1.00 and $0.50 a transaction on Starter and Growth, subscriptions from $249 a month and the surcharging logic to recover the card cost.
Do MSP payment tools integrate with ConnectWise, Autotask and HaloPSA?
Alternative Payments and FlexPoint connect natively to ConnectWise, Autotask, HaloPSA and SuperOps. ConnectBooster connects to ConnectWise, Autotask and Kaseya BMS, and has no HaloPSA or SuperOps connector. Paidnice takes a different route: because the PSA already syncs finished invoices into QuickBooks Online or Xero, it reads from the ledger and needs no PSA connector.
How much do MSP payment tools cost?
Alternative Payments publishes US$199 a month up to $50,000 of processing and $499 up to $100,000, with cards at 2.9% + $0.30, AMEX at 3.5% + $0.30, no ACH fees on the pricing page and a $25 card dispute cost. FlexPoint publishes $249 a month for Starter and $550 for Growth, ACH at $1.00 or $0.50 per transaction on Starter and Growth and cards at 3.0% or Interchange+ with the margin unstated.
ConnectBooster publishes no price at all and bills through three separate invoices. Paidnice publishes £49 (US$69) a month, separate from whatever processor moves the money.
Which MSP payment tool applies late fees automatically?
None of the three gateways. FlexPoint syncs whatever QuickBooks already calculated rather than computing anything, and Alternative Payments and ConnectBooster document no fee or interest function at all. Paidnice computes one and posts it to the ledger.
Do I need a separate collections tool if my gateway sends reminders?
A gateway reminder tells the client the invoice is open. It does not apply the fee your agreement allows, escalate by client group, run statements on a schedule or post anything to the ledger.
What happens to my payment tool if I change PSA?
A tool with its own PSA connector has to support the new one, and if it does not, the tool moves with the PSA. A tool that reads from the accounting system is untouched by the migration, because the invoice data lands in the same place whichever PSA produced it.
Related MSP guides
Buyer's guide
Best accounts receivable software (by business type)
Compared by business size and accounting system, with a recommendation matrix.
MSPs
Best AR software for MSPs
Accounts receivable tools that fit MSP billing and PSAs.
Comparison
Best AR automation software
Six AR automation tools compared on features and price.
Data & research
28 accounts receivable statistics for 2026
Late payments, DSO and the measured impact of automation, fully sourced.
Sources
7 sources, checked by Julie Turnbridge on November 3, 2026
- Xero App Store apps.xero.com/app/paidnice
- G2 g2.com/products/alternative-finance-alternative-payments/...
- G2 g2.com/products/flexpoint-flexpoint/reviews
- G2 g2.com/products/connectbooster/reviews
- Capterra capterra.com/p/254868/Paidnice
- Capterra capterra.com/p/10024207/FlexPoint
- Capterra capterra.com/p/192910/ConnectBooster

