Chaser vs Paidnice turns on the grain of the late fee, since both raise one on their own. Choose Paidnice if you run Xero or QuickBooks Online and want a fee policy per customer group, priced by invoice volume from £49 (US$69) a month. Choose Chaser for Creditsafe checks, letters and calls under one set of fee rules, from £199.
Chaser runs four calculation types under a single set of rules and adds Creditsafe credit checking, posted letters and automated calls, from £199 a month. Paidnice runs a separate fee and interest policy under each customer group and posts the charge to the ledger in Xero or QuickBooks Online, from £49 (US$69) a month.
Both charge, so the argument is about how many different rules can be true at the same time, what happens to an invoice that is half paid or sitting on a plan, and which meter the bill runs on: Chaser reads your company turnover, Paidnice reads your invoice count.
What does credit control software do?
Credit control software works the invoices a business has already raised. It reads the open invoices in the ledger, decides who to contact and when, and takes the next step. Paidnice and Chaser both sit in this category.
Between them, the two products on this page cover these jobs:
- Reminders by email and SMS on a set schedule
- Statements, monthly on a fixed day in Chaser and on any schedule in Paidnice
- Late fees and interest, including a Bank of England base rate calculation in both
- Payment plans (on Pro in Paidnice) and a customer payment portal
- Escalation, to a collections partner in Chaser and to manual task workflows in Paidnice
The ledger stays the system of record: invoices, payments and customer records remain in Xero, QuickBooks Online or another accounting system, and the software reads them. Neither product recovers the debt itself, as an agency would, and both stop before an account is written off.
Credit data is where the two differ: Chaser includes a bureau check. Chaser has Creditsafe credit checking in the same tool as its chasing. Paidnice runs native credit checks from each customer's payment behaviour, and Creditsafe bureau checks through the API on the Custom plan.
Where it sits: between the ledger and the customer. Paidnice is native to Xero and QuickBooks Online. Chaser connects to those two and to Sage, NetSuite, Dynamics 365 Business Central, AccountsIQ and SAP, and sends reminders from your own Gmail or Outlook mailbox.
What is the difference between Paidnice and Chaser?
Chaser is the larger, longer-established tool with credit checking and every chasing channel, from £199 a month. Paidnice is the cheaper enforcement tool with a fee policy per customer group, from £49 (US$69).
Chaser has traded since 2014, holds 4.98 from 374 Xero App Store reviews and bundles Creditsafe credit checking, email, SMS, posted letters and automated calls behind one login, with an entry tier priced for turnover to £4m. It is the established choice for a business with a named credit controller.
Paidnice runs on Xero and QuickBooks Online on every plan (newer ledgers such as Rillet, Campfire and Odoo are available through its closed testing program), holds 5.0 from 84 Xero App Store reviews, and its distinguishing feature is the grain of the charge: an invoice late fee and a statement interest policy per customer group, posted to the ledger. Entry is £49 a month on the UK price table.
They are priced and built for different desks. Choose Paidnice if you run Xero or QuickBooks Online and want a different late fee or interest policy for each customer group, priced by invoice volume. Choose Chaser if you want Creditsafe credit checks, posted letters and automated calls behind one login on a turnover-priced plan.
How do the late fee rules differ between Paidnice and Chaser?
Chaser’s fee is one set of rules for the account, applied to every debtor or to selected debtors, and Paidnice’s fee is a property of a customer group, so one ledger can hold several groups at once, each at its own rate.
A single rule is fine while every customer is the same kind of customer. Few ledgers are like that.
A trade account on 30-day terms, a retail account paying on receipt and an account in dispute all sit in the same aged debtors report, and a 2% charge applied to all three is either too blunt for the first or unusable for the last.
Chaser offers four calculation types, one of them indexed to the Bank of England base rate and recalculated daily, and applies whichever you pick across the whole account.
Paidnice attaches the policy to a customer group instead, so the wholesale group, the retail group and the disputed-accounts group each carry their own rate, and an invoice late fee and a statement interest charge can both run on the same group.
The arithmetic is identical in both products, so it is set out once here and used again in the configuration section. On $12,000 overdue for 30 days, a 2% invoice late fee is $240.00 and statement interest at 12% a year is $118.36, so $358.36 is added to the ledger.
How do Paidnice and Chaser compare?
Paidnice and Chaser both apply a charge themselves, both take payment and both run a customer portal. What separates them is the grain of the fee, the ledgers each reaches, credit data, and what the pricing is metered on.
 |
 |
|
|---|---|---|
| Best for | Xero or QuickBooks Online ledgers needing a fee per customer group | Screening customers, then chasing by email, SMS, letter and call |
| Revenue fit | Any size up to 50,000 invoices a year | Compact under £4m, Core from £4m, Complete to £100m |
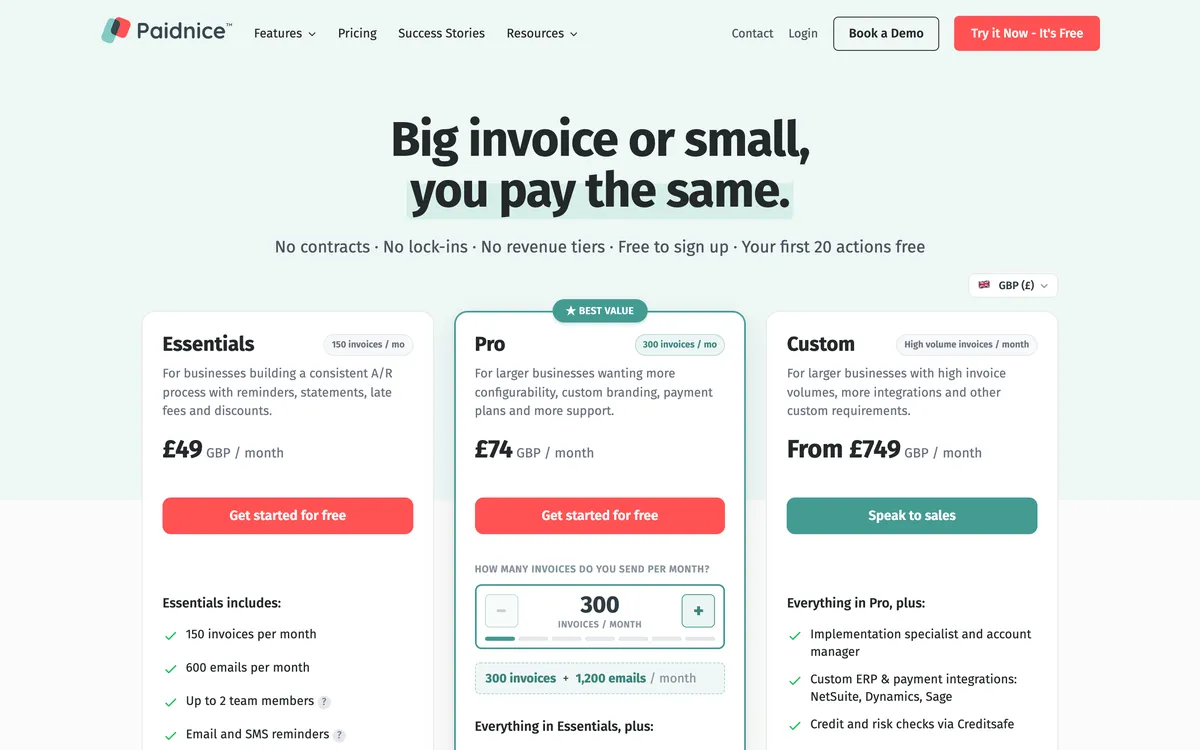
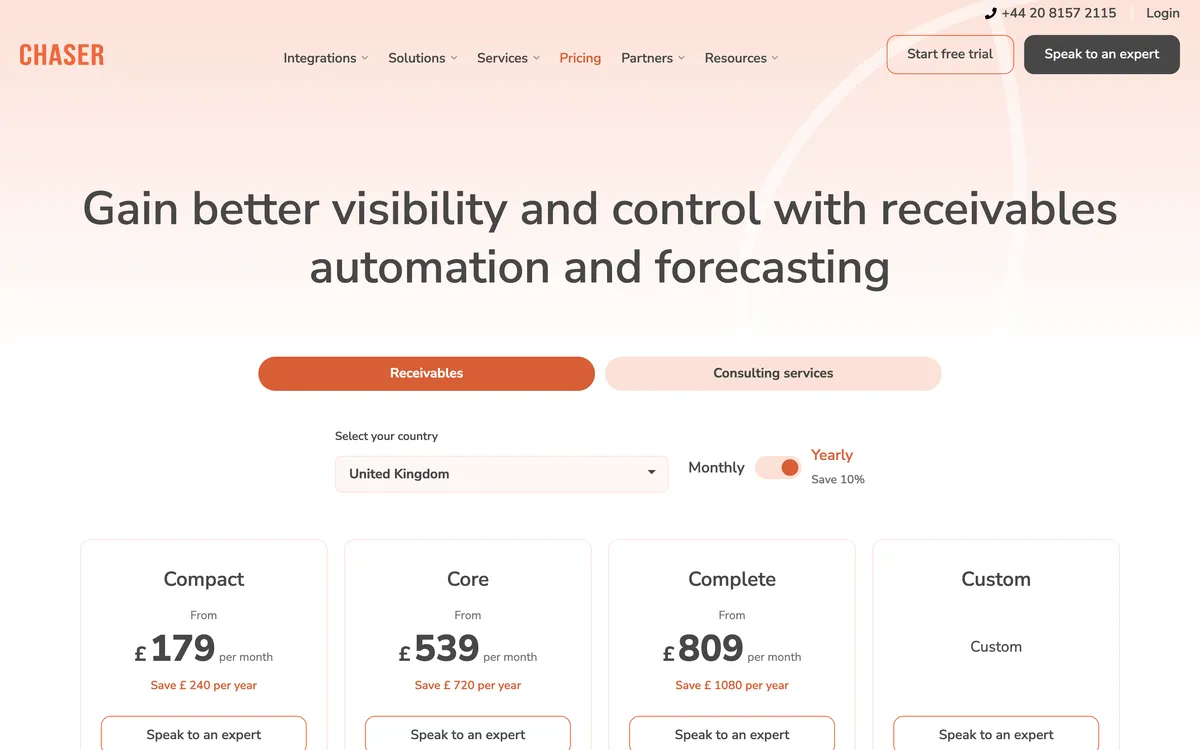
| From (monthly) | £49 (US$69) | £199 |
| Priced on | Invoice volume, no per-seat fee | Company annual revenue |
| Ledger integrations | Xero and QuickBooks Online on every plan; newer ledgers such as Rillet, Campfire and Odoo on every plan through closed testing. Sage Accounting, NetSuite, Sage Intacct, MYOB, Dynamics 365 Business Central and other ERPs on the Custom plan | Xero, QuickBooks, Sage 50, Sage 200, Sage Intacct, Sage Business Cloud Accounting, NetSuite, Dynamics 365 Business Central, AccountsIQ, SAP |
| Late fee grain | Yes (per customer group) | Yes (one set of rules for the account) |
| Chasing channels | Email from your own authenticated domain on Pro, SMS metered at £0.05, in-app calls made by a person, recorded and transcribed | Email from your own mailbox, SMS, posted letters, automated calls, all credit-metered |
| Statements | Yes (any schedule, consolidated parent accounts) | Yes (monthly, fixed day) |
| Payment plans | Yes, on Pro (deposits, instalments, auto-pay) | Yes (chased on the invoice due date) |
| Portal | Yes | Yes |
| Credit checks | Yes: native checks from payment behaviour, plus Creditsafe via API on the Custom plan | Yes (Creditsafe) |
| AI | Advanced Reads customer replies, drafts answers and follow-up actions (like PO updates) for your approval; MCP server for Claude, ChatGPT and other agents | |
| Rated (source, count) | 5.0 (84, Xero App Store) | 4.98 (374, Xero App Store) |
“Not documented” means the vendor does not document the capability. “None found” means no evidence either way. Prices are the vendor’s published from-price. Check current pricing with the vendor.
How do you set up a 2% wholesale fee and no retail fee in each product?
One policy, written down before either product is opened: 2% on invoices to trade accounts once they are 14 days overdue, nothing on retail, and nothing at all on an account already paying by instalments.
In Chaser
You pick one of the four calculation types, set the rate at 2% and apply the rules to selected debtors: the trade accounts in, the retail accounts out.
Every selected debtor gets the same rate, because there is no second set of rules for another group. The one clause Chaser satisfies for free is the third, because it raises no fee at all on payment-plan invoices. If you want the fee to land as a line item on the ledger, that sync works on Xero and not on QuickBooks.
In Paidnice
You build the trade group, attach a percentage policy at 2% with a 14-day trigger, and leave the retail group with no fee policy on it. A second policy, statement interest on the whole overdue balance, can sit on the same trade group.
Accounts on a payment plan come off the fee policy while the reminder ladder keeps running, and a single disputed invoice is excluded by its reference without moving the customer out of the group. The charge is raised as a Draft or an Approved invoice on the ledger.
Now run the policy over a mixed month of 40 overdue invoices, 20 trade and 20 retail, each at $12,000 and 30 days late.
Both produce 20 charges of $240.00 and 20 of nothing, so $4,800 lands where the policy said it should: Chaser through its selected debtors, Paidnice through its two groups.
The difference shows when the retail accounts need a rate of their own, say 1%: Paidnice attaches a second policy to the retail group, while Chaser has one set of rules and one rate.
What happens to a part-paid invoice, and to one on a plan?
A part-paid invoice or one on a plan is where the late fee settings of Paidnice and Chaser stop behaving alike, and neither behaviour is documented on the pricing page.
Chaser’s help says a late fee cannot be added or updated after a part payment when written to Xero, and Chaser raises none on an invoice sitting on a payment plan. A customer who pays £2,000 of a £10,000 invoice on the due date can put the remaining £8,000 out of reach of an added or updated fee for as long as it stays overdue.
Chaser splits an invoice into instalments from weekly through to yearly, but the chasing still follows the original invoice due date rather than the instalment dates, and its own documentation advises chasing the instalments manually. Plans are not available on the trial, on the Custom tier or alongside Chaser Care.
Paidnice computes statement interest on the overdue balance rather than the invoice face value, so the part payment reduces the charge instead of removing it, and the balance is netted against any credit on the account.
A plan is a deliberate exclusion rather than a side effect of the fee model: the account comes off the fee policy and stays on the reminders, with deposits, instalments and auto-pay running through Stripe or Pinch Payments.
Chaser’s help says a late fee cannot be added or updated after a part payment when written to Xero. Paidnice reads the unpaid balance as the thing being charged for and keeps going. Choose the behaviour that matches your customers.
Chaser vs Paidnice: enforcement, credit data and price (1:47)
Video chapters and transcript
- 0:00 Short answer
- 0:31 Fit, in alphabetical order
- 0:50 What each tool does best
- 1:14 Limits and price, as the page states them
Chaser versus Paidnice. Which one fits your business? Both tools raise a late fee on their own, and both publish a price.
Chaser runs four calculation types under a single account-wide rule, and adds Creditsafe credit checking, posted letters and automated calls. Paidnice runs a separate fee and interest policy for each customer group, and posts the charge to the ledger in Xero or QuickBooks Online. The differences are the grain of the fee, the credit data, and what the price is based on.
Choose Chaser if you want Creditsafe credit checks, posted letters and automated calls behind one login, on a plan priced by company turnover. Choose Paidnice if you run Xero or QuickBooks Online and want a different late fee or interest policy for each customer group, priced by invoice volume. Chaser has traded since 2014, and holds four point nine eight from three hundred and seventy-four Xero App Store reviews.
It combines credit checking with email, SMS, letters and automated calls. Paidnice holds five point zero from eighty-three Xero App Store reviews. Its strength is the grain of the charge: an invoice late fee and a statement interest policy on each customer group.
Chaser's late fee is a single account-wide setting, and its tiers step with company turnover. It starts at one hundred and ninety-nine pounds a month excluding VAT. Paidnice has no credit bureau, and no posted letters or automated calls, so its escalation ends at email, SMS and a task. It starts at sixty-nine dollars a month, and its tiers step with invoice count.
What does each tool cost at £500k, £4m and £10m?
Chaser meters its price on company annual revenue and Paidnice meters on how many invoices you raise in a month. The two curves cross, and where they cross depends on your average invoice size rather than your turnover.
At £500k. Chaser is £199 a month on Compact, the same £199 it charges a business nearly eight times larger, because Compact covers everything under £4m.
Paidnice at that size is usually Essentials at £49 (US$69) for 150 invoices a month, or £49 (US$69) on the US price table. Chaser costs roughly four times as much here, and the difference buys credit checking, posted letters and automated calls.
Just under £4m. Chaser is still £199, which is the same price at any turnover in its band and the point at which a turnover meter works in the buyer’s favour. From £4m a team is on Core from £599. Paidnice has moved with the invoice count by then, to Pro from £74 at 300 invoices or £129 at 600.
This is the crossing point, and invoice size decides which side you land on: a consultancy just under £4m raising 200 large invoices a month pays Chaser more, and a distributor just under £4m raising 2,000 small ones pays Paidnice more.
Just under £10m. Chaser is on Core at £599, which adds unlimited users, templates and schedules, 600 credits, multi-entity and call recording, and from £10m on Complete at £899 covering to £100m.
Paidnice steps only when the invoices do, reaching £599 at 4,000 a month, with Custom from £749 quoted for an ERP connection at any volume. A business just under £10m raising 200 invoices a month pays Chaser £599 and Paidnice £74 (US$99) for the same twelve months of work.
Two extras belong in the same budget line. Chaser’s AR forecast is £9 a month on top and the Cash flow plan is a separate £29 a month subscription, extra templates or schedules £5, and every chasing channel and credit check is metered.
Paidnice meters SMS at £0.05 and charges £19 a month for each further Xero or QuickBooks Online organisation, and bills from a fixed local price table rather than an FX conversion.
Neither vendor pays to be here. Both prices come from the vendors’ own pricing pages. Check current pricing with the vendor before you budget on it.
Paidnice
Paidnice is a reminder, late fee and interest tool for Xero or QuickBooks Online ledgers that hold more than one kind of customer, up to 50,000 invoices a year, from £49 (US$69) a month.
Who should choose Paidnice?
Choose Paidnice if you already know which accounts you are willing to charge and which you are not, and want both answers running at once instead of picking one for the whole ledger.
- Fits
- Businesses on Xero and QuickBooks Online of any size up to $50m a year, or 50,000 invoices a year, with or without a credit controller
- Regions
- United States, United Kingdom, Australia, New Zealand, Canada, South Africa
- Entry cost
- £49 (US$69) a month on Essentials, covering 150 invoices, 600 emails and up to 2 team members; £49 (US$69) and A$99 in local price tables, not converted; Pro from £74 (US$99) a month with unlimited users and no per-seat fee; Custom from £749/mo.
- Rated
- 5.0 from 84 Xero App Store reviews; 4.9 from 14 on Capterra · Xero App Store listing
- Awards
- Xero Global Small Business App of the Year 2025 and NZ Small Business App of the Year 2026
- Runs on
- Xero, QuickBooks Online, Stripe, Pinch Payments, CloudDepot, HubSpot, Pipedrive, Zapier. Newer ledgers such as Rillet, Campfire, Digits, DualEntry, Puzzle, Accounting Seed and Odoo on every plan through closed testing. Sage Accounting, NetSuite, Sage Intacct, MYOB, Dynamics 365 Business Central and other ERPs on the Custom plan
- Late fees and interest
- Yes. Flat, percentage and compounding charges, with a Bank of England base rate toggle for UK invoices, raised on the ledger as Draft or Approved. Policies sit under customer groups, so several run at once
- Does best
- Two charge types on the same customer group, an invoice late fee and a statement interest charge, both posted to the ledger
Where Chaser holds one fee rule for the account, Paidnice holds a policy per customer group, so a wholesale group, a retail group and a disputed-accounts group each run their own rate at the same time.
Two charge types are available on any one group: an invoice late fee per overdue invoice, and a statement interest charge on the whole overdue balance.
Around that runs the ordinary ladder, email and SMS (from your own authenticated domain on Pro), statements on any schedule including consolidated parent and child accounts, prompt payment discounts, payment plans on Pro, a customer payment portal and escalation through manual task workflows.
The charge is raised on the ledger as a posted invoice, Draft or Approved, which is the mechanism that matters: only a posted document enters the customer’s own payables, their aged payables report and their next payment run.
Statement interest recalculates at the moment the statement sends rather than at the last policy run, so the figure the customer opens is accurate that morning, and it is netted against any credit on the account. Compounding is on by default; simple interest is the deliberate choice.
For UK invoices the rate can track the Bank of England base rate, applying the correct base rate for each period an invoice spans rather than the rate that happens to be current when the charge fires.
Paidnice uses AI to read inbound replies, log payment promises and draft the answer; a person approves each draft before it sends, unless you pre-approved that action type. Customers can query an invoice or promise to pay from the portal, and SMS and email replies land in Paidnice. On Pro and Custom plans its MCP server connects Claude, ChatGPT or any agent with a custom connector, and one connection covers every organisation. Further Xero or QuickBooks Online organisations are added at £19 per entity a month.
Limitations with Paidnice. Posted letters are on Pro and up, on request. Calls are made by a person from inside Paidnice, recorded and transcribed.
Its native connectors are Xero and QuickBooks Online on every plan. Newer ledgers such as Rillet, Campfire, Digits, DualEntry, Puzzle, Accounting Seed and Odoo are available on every plan through Paidnice’s closed testing program. Sage Accounting, NetSuite, Sage Intacct, MYOB, Dynamics 365 Business Central and other cloud ERPs connect on the Custom plan; desktop ledgers such as Sage 50 and Sage 200 are not supported.
The entry tier covers two team members. Payment plans and sending from your own domain start on Pro. Chaser has the larger verified review base, 4.98 from 374 against 5.0 from 84.
Best suited for: Xero or QuickBooks Online businesses that want a different late fee or interest policy for each customer group, priced by invoice volume. The drawback is that Sage Accounting and other ERPs need the Custom plan.
Chaser
Chaser is a credit control tool with a Creditsafe bureau file and every chasing channel behind one login, from £199 a month for turnover under £4m.
Who should choose Chaser?
Choose Chaser if you would rather screen a customer before extending terms than argue with them afterwards, and want the screening, the email, the SMS, the posted letter and the call all metered on one bill.
- Fits
- Businesses with a named credit controller; Compact is priced for turnover under £4m, Core from £4m, and the tiers run to £100m
- Regions
- UK-registered, trading since 2014, sells worldwide. Automated calls are not available in New Zealand
- Entry cost
- £199/mo on Compact for turnover under £4m with 4 users; Core £599/mo under £10m; Complete £899/mo above that; Chaser Care from £899/mo, bundled with the software. Chaser offers a free trial (10 days on the Xero listing) or a conversation with an expert.
- Rated
- 4.98 from 374 Xero App Store reviews; 4.3 from 71 on G2; 4.9 from 45 on Capterra · Xero App Store listing
- Awards
- Finalist, UK Small Business App Partner of the Year, Xero Awards 2023
- Runs on
- Xero, QuickBooks, Sage 50, Sage 200, Sage Intacct, Sage Business Cloud Accounting, NetSuite, Dynamics 365 Business Central, AccountsIQ, SAP, HubSpot, Gmail, Outlook, CSV
- Late fees and interest
- Yes. Four calculation types including a Bank of England base rate type, recalculated daily, but one set of rules for the account, applied to every debtor or to selected debtors, and no fee is raised on payment-plan invoices; Chaser’s help says a late fee cannot be added or updated after a part payment when written to Xero
- Does best
- Creditsafe credit checking and monitoring in the same tool as email, SMS, letter and automated-call chasing
Chaser has traded since 2014 and holds the larger verified review base of the two, 4.98 from 374 Xero App Store reviews.
Reminders leave from the team’s own Gmail or Outlook mailbox, so replies land where the controller already works, and SMS, posted letters, one-way automated calls, a payer portal and an integrated handover to a collections partner sit behind the same login.
Every channel is metered by credit, which means a difficult month costs more than a quiet one: SMS at £0.05 to £0.07, letters at £1.25 to £1.50 a credit, calls at £0.08 a credit-minute.
The Creditsafe report is the part Paidnice offers only on its Custom plan, through the API. Creditsafe supplies a credit score with a recommended limit, the customer’s own payment score, credit event history, and Companies House filing and director data, with continuous monitoring on top.
Checks cost 1 credit for the UK and Ireland and 4 elsewhere, so careful screening is a line on the bill rather than a free habit. Credit checks are sold by credit on any plan, and they need Chaser billing, not Xero App Store billing; monitoring is not offered in Australia.
Chaser Care runs the chasing as a managed service from £899 a month, sold as bundles at £899, £1,599 and £2,099 that carry the software and call hours together, and there is a white-label build for accounting firms.
Chaser offers a free trial (10 days on the Xero listing) or a conversation with an expert; there is no minimum term, and yearly billing takes 10% off.
Limitations with Chaser. The late fee is one set of rules for the account, so every debtor it covers gets the same rate, and Chaser documents no way to give a second group a rate of its own.
Chaser’s help says a late fee cannot be added or updated after a part payment when written to Xero, and none is raised on an invoice sitting on a payment plan. The line-item sync of the fee into the ledger works on Xero and not on QuickBooks. Statements go monthly only, on a fixed day, with recipients and senders not customisable.
Compact caps the team at four users, at £10 a month for each one beyond that. The tiers step on company turnover rather than invoice volume, so growth alone moves the bill. Reviewers report that a reply to a chasing email cannot be answered from inside the tool.
Best suited for: UK businesses with a named credit controller who want Creditsafe checks, posted letters and automated calls on one bill. The drawback is one set of late fee rules for the account and a price that steps with company turnover rather than invoice volume.
Which suits a small Xero business, Chaser or Paidnice?
Under £2m of turnover the two prices sit roughly four to one apart, and the choice turns on whether you need a credit bureau or a per-customer fee.
Chaser’s Compact tier is £199 a month whether you turn over £300k or just under £4m, because the meter is company turnover. A business at £1m raising 80 invoices a month pays the same as one just under £4m raising 400.
Paidnice on the same ledger is £49 (US$69) on Essentials for 150 invoices and two team members, or £74 (US$99) on Pro 300 with unlimited users.
What the extra £150 a month buys is the Creditsafe file, posted letters and automated calls. A small business that extends terms to new trade accounts without screening them is the buyer for that.
A small business whose problem is good customers paying late has no use for the bureau and every use for a charge that lands in the customer’s payables.
Should you prevent the debt with credit checks or price it with a fee?
Chaser leads with a bureau credit check, a decision you make before the invoice exists, and Paidnice leads with a fee, a consequence that attaches after it goes unpaid. One does not replace the other.
Screening reduces the number of accounts that can go bad. Chaser’s in-app Creditsafe report gives a score with a recommended limit, the customer’s payment score, credit event history and Companies House filing and director data, monitored continuously.
If the pattern you keep hitting is a customer who was never good for the money, that is the half of the problem worth buying.
A posted charge changes what lateness costs a customer who is already late. It arrives in their payables, ages on their own aged payables report, and can be waived deliberately, in writing, in exchange for payment today, which is a negotiating position a reminder does not give you.
If the pattern you keep hitting is a good customer who pays everyone else first, that is the half worth buying.
Neither product is an external recovery agency. Chaser hands an unpaid invoice to a collections partner from inside the tool, on success fees that step down with the size of the debt. Paidnice escalates through manual task workflows inside your own ledger and can route escalation to any collection agency, solicitor or partner. Both stop before an account is written off.
How do the Paidnice and Chaser Xero reviews compare?
Chaser holds 4.98 from 374 Xero App Store reviews. Paidnice holds 5.0 from 84, all of them five-star. Chaser has the larger and older review base, Paidnice the perfect score.
On the Xero App Store Chaser has been listed since May 2015 and sits at 4.98 from 374 reviews. Paidnice has been listed since December 2021 and sits at 5.0 from 84, 100% five-star.
Both are listed under Debtor management. A review base four and a half times larger, listed six years longer, is the more reliable signal, and it is Chaser’s.
Off the Xero store, Chaser holds 4.3 from 71 on G2 and 4.9 from 45 on Capterra. Paidnice holds 4.9 from 14 on Capterra and 4.7 from 29 on Trustpilot.
The negatives are specific: a Chaser reviewer on Capterra wrote that replies to chasing emails cannot be answered inside the tool; a Paidnice reviewer on Capterra called setup “still a bit clunky and not intuitive enough”, and another asked for bulk removal of late fees.
Which product applies UK statutory interest to which invoice?
Chaser is a UK vendor and both products document a Bank of England base rate calculation, so the statutory question carries more weight on this pairing than on any other in the category.
Under the Late Payment of Commercial Debts (Interest) Act 1998 a UK business can charge 8% a year above the Bank of England base rate on an overdue B2B invoice, plus a fixed sum of £40, £70 or £100 by size of debt.
The entitlement exists whether or not your terms mention it, and the base rate moves, so check the current figure on GOV.UK before you invoice for it.
Chaser runs the base rate type as one set of rules, recalculated daily and applied across the account.
Paidnice runs it as a policy under a customer group, applying the correct base rate for each period an invoice spans, so an invoice that stayed overdue across a rate change is charged at both rates rather than at whichever one happens to be current when the charge fires.
Statutory interest is the one case where one set of rules for the account is a reasonable fit, because the entitlement is the same for every B2B customer you have. It stops fitting the moment you want a commercial rate on some accounts and only the statutory minimum on others, which is the same grain problem the configuration section above walks through.
On $12,000 overdue for 30 days, a 2% invoice late fee is $240.00 and statement interest at 12% a year is $118.36, so $358.36 is added to the ledger.
The invoice late fee is a percentage of the overdue invoice. Statement interest is the balance multiplied by the annual rate, apportioned over the days it was late. Chaser applies one such rule across the account; Paidnice can run a different one per customer group, and both charge types on the same group.
How do Paidnice and Chaser compare in New Zealand?
Paidnice prints a New Zealand dollar price and won Xero’s NZ Small Business App of the Year 2026. Chaser prices in UK pounds, from £199 a month on Compact, and does not offer automated calls in New Zealand.
Paidnice bills from a fixed New Zealand dollar price table, excluding GST. Chaser prices in UK pounds, from £199 a month on Compact for revenue under £4m, and Chaser’s automated calls are not available in New Zealand, which removes one of the channels the price pays for.
| Tier | Paidnice (NZ$ a month, excluding GST) | Chaser (£ a month) |
|---|---|---|
| Entry | NZ$109 Essentials, 150 invoices, 2 team members | £199 Compact, revenue under £4m, 4 users |
| Second tier | NZ$149 Pro 300, unlimited users | £599 Core, revenue under £10m, unlimited users |
| Third tier | NZ$289 Pro 600 | £899 Complete |
| Further Xero organisation | NZ$49 per organisation a month | Multi-entity from Core |
The enforcement context is different too. New Zealand invoices were paid in 24.1 days on average and 4.7 days late, on Xero’s latest Small Business Insights data. Where a charge and a reminder ladder fail, the Disputes Tribunal hears claims to $60,000 from 24 January 2026, with a $468 filing fee on the top band.
The Limitation Act 2010 gives six years to bring the claim. Both products stop before that step: Chaser hands over to a collections partner, Paidnice can route escalation to any collection agency, solicitor or partner.
Chaser’s UK statutory interest calculation has no New Zealand equivalent, so the rate you can charge is the one your terms state. Paidnice’s per-group flat, percentage or compounding policy fits that, and it posts the charge to the Xero organisation as a Draft or Approved invoice.
Which credit control software fits your use case?
Start from the job you need done first. The ledger you run and the channels you need settle most of these rows before price does.
| Use case | Start with | Why |
|---|---|---|
| Screening new trade accounts before you extend terms | Chaser | Creditsafe credit checking sits in the same tool; Paidnice runs native checks from payment behaviour, plus Creditsafe via API on the Custom plan. |
| Trade, retail and disputed accounts on one Xero or QuickBooks Online ledger | Paidnice | A separate fee and interest policy runs under each customer group. |
| Reminders and statements only, no late fees | Paidnice | Statements go on any schedule from £49 (US$69) a month; Chaser sends them monthly on a fixed day. |
| Ledger on Sage 50 or Sage 200 | Chaser | Chaser connects to both; Paidnice does not serve either. |
| Posted letters and automated calls as standard channels | Chaser | Paidnice posts letters on Pro and up, on request, and records calls made by a person. |
| A New Zealand business that wants a local price | Paidnice | Paidnice starts at NZ$109 a month; Chaser starts at £199 and has no automated calls in New Zealand. |
What do buyers ask when they have shortlisted these two?
The questions that come up once a UK credit team has narrowed it to this pair and has to write the difference down for whoever signs the budget.
Can Chaser charge one rate to trade customers and another to retail?
Chaser has no documented way to charge one rate to trade customers and another to retail. Chaser’s late fee is one set of rules for the account, applied to every debtor or to selected debtors, so every debtor it covers gets the same rate. It can leave retail out, but it documents no way to give retail a rate of its own.
Paidnice attaches the policy to a customer group, so a wholesale group at 2% and a retail group at 1% run at the same time on the same ledger.
What happens to the fee when a customer pays half the invoice?
Chaser's help says a late fee cannot be added or updated after a part payment when written to Xero, so the remaining balance can be out of reach of the fee until it is settled. Paidnice calculates statement interest on the overdue balance rather than the invoice face value, so the part payment reduces the charge rather than cancelling it, and interest is netted against any credit on the account.
Which one applies UK statutory interest correctly across a base rate change?
Paidnice and Chaser both document a Bank of England base rate calculation. Chaser recalculates its fee daily. Paidnice applies the correct base rate for each period the invoice spans, so an invoice that stayed overdue through a rate change is charged at both rates.
At what size does Chaser stop being the more expensive option?
Chaser stops being the more expensive option at a size that depends on invoice count rather than turnover.
Chaser is £199 a month at any revenue under £4m, so just under £4m with a high invoice volume it can be the cheaper of the two, while Paidnice has stepped to £129 at 600 invoices a month. From £4m Chaser is £599 and from £10m £899, while Paidnice may still be on £74 (US$99).
Do I keep credit checking if I choose Paidnice?
Yes. Paidnice runs native credit checks from each customer's payment behaviour, and Creditsafe bureau checks through the API on the Custom plan. On Essentials and Pro there is no bureau score or recommended limit. Posted letters are on Pro and up, on request. Calls are made by a person from inside Paidnice, recorded and transcribed.
Does either one sync the fee into Xero as a line item?
Chaser’s line-item sync of the fee is Xero only and does not work on QuickBooks. Paidnice raises the charge as a separate Draft or Approved invoice on either ledger, which is what puts it into the customer’s own payables rather than onto the original document.
Does either tool replace an external recovery agency?
Neither collects the debt itself. Chaser hands an unpaid invoice to a collections partner from inside the product, on success fees that step down with the size of the debt. Paidnice escalates through manual task workflows and can route escalation to any collection agency, solicitor or partner.
Related comparisons for a UK credit team
Alternatives
Best Chaser alternatives
Six Chaser alternatives on enforcement, price and verified reviews.
Buyer's guide
Best accounts receivable software
The pillar guide, compared by business size and accounting system.
Credit control
Best credit control software UK
Six tools compared on statutory interest grain and published price.
Buyer's guide
Credit control software for Xero
Where it fits, what it costs, and how to choose for a Xero account.
Sources
9 sources, checked by Julie Turnbridge on November 3, 2026
- Xero App Store apps.xero.com/app/paidnice
- Capterra capterra.com/p/254868/Paidnice
- Xero App Store apps.xero.com/uk/app/chaser
- G2 g2.com/products/chaser/reviews
- Capterra capterra.com/p/157101/CHASER/reviews
- Trustpilot uk.trustpilot.com/review/paidnice.com
- Late Payment of Commercial Debts (Interest) Act 1998 legislation.gov.uk/ukpga/1998/20/contents
- Bank of England base rate bankofengland.co.uk/monetary-policy/the-interest-rate-ban...
- GOV.UK gov.uk/late-commercial-payments-interest-debt-recovery/ch...

