The best accounts receivable software for wholesale and distribution in 2026 is Paidnice, for a distributor on Xero or QuickBooks Online that wants a different late fee rule running on each trade group, from £49 (US$69) a month. ezyCollect, Chaser, Quadient AR and Versapay complete the five, compared on late fee enforcement, published entry price and verified reviews.
| Tool | Best for | ||||
|---|---|---|---|---|---|
| Best for | Late fee rules per trade group on Xero or QuickBooks Online | Australian and New Zealand buyer credit screening | Creditsafe limits and posted letters | Remittance matching for groups on an ERP | Shared dispute and payment portal in North America |
| Paidnice | A distributor on Xero or QuickBooks Online that wants a different late fee rule running on each trade group | ||||
| ezyCollect | An Australian or New Zealand distributor on MYOB, Pronto Xi or SAP Business One that scores a buyer before granting terms | ||||
| Chaser | A team with a credit controller that wants a Creditsafe limit and posted letters in the same tool as the chasing | ||||
| Quadient AR | A distribution group on NetSuite, Sage Intacct or SAP whose bottleneck is matching remittances to open invoices | ||||
| Versapay | A North American distributor on an ERP that wants trade buyers disputing and paying in a shared portal |
TreviPay sells embedded net terms to dealer networks, and publishes no pricing, feature detail or review score that could be verified, so it is named here rather than compared.
The Xero Small Business Insights figures for the latest quarter put a number on that wait: 29.7 days to be paid on average, and 25.6 in California.
Those sit either side of a 29.1-day national average that has lengthened from 27.5 a year earlier, with settlement running 8.3 days past due.
What is accounts receivable software for wholesale and distribution, and what is it not?
Accounts receivable software for wholesale and distribution works the trade invoices already on your ledger. It reads Xero, QuickBooks Online or the ERP, chases what is overdue across hundreds of trade accounts and stops the chase when the payment lands.
- Reminders by email and SMS, and on Chaser posted letters, set per trade group on some tools.
- Statements, including consolidated parent and child statements for a buying group on Paidnice.
- Late fees and interest on overdue trade invoices. Paidnice and Chaser raise one; ezyCollect, Quadient AR and Versapay do not document one.
- Credit scores and limits before terms are granted, on ezyCollect, Chaser and Quadient AR, and on Paidnice: native checks from payment behavior on every plan, plus Creditsafe via API on the Custom plan.
- Payment plans and a buyer portal.
It is not the ERP or the order screen. Every tool here sits downstream of the sales order, so a stop-supply decision is still enforced in your ERP or on your order entry screen.
It is not trade credit insurance. Insurance pays a claim after a covered buyer fails, while the software works the solvent buyer who settles at 52 days on Net 30. It is not a collection agency either, though ezyCollect can refer an account to a collections partner.
A late fee is optional, and outside the UK the trading agreement has to carry the rate.
How this list was put together
This list helps a wholesaler or distributor chase hundreds of trade accounts on Xero, QuickBooks Online or an ERP.
| What we checked | Where the evidence came from |
|---|---|
| A late fee rule per trade group | Vendor help pages on fees and interest |
| Consolidated statements for a buying group | Vendor feature pages |
| Credit checks on trade accounts | Vendor product pages for Creditsafe, Experian and credit scorecards |
| Payment plans and a portal | Vendor feature pages |
| Published from-price | The vendor's pricing page, and the last reported price where it is now hidden |
| Rating and review count | The Xero App Store, including the Australian store, or G2 |
Wholesale and distribution AR software compared: the table
 |
 |
 |
 |
 |
|
|---|---|---|---|---|---|
| Revenue fit | Any size up to $50m a year, or 50,000 invoices a year | Not published (plans sized by debtor count, 200 to 3,000) | Compact under £4m, Core from £4m, Complete to £100m | Not published | Not published |
| From (monthly) | US$69 | A$275 a month for ezyStart, setup from A$900 (last published; current prices hidden and must be requested) | £199 | Not published | Not published |
| Ledger integrations | Xero, QuickBooks Online and newer ledgers such as Rillet and Campfire (closed testing) on every plan; Sage Accounting and other ERPs on Custom | Xero, MYOB AccountRight, Exo, Essentials and Acumatica, NetSuite, Dynamics, Sage 300, Sage Intacct, SAP Business One, Pronto Xi, Attaché, JCurve; QuickBooks logo on homepage, no connector page | Xero, QuickBooks, Sage 50, Sage 200, Sage Intacct, Sage Business Cloud Accounting, NetSuite, Dynamics 365 Business Central, AccountsIQ, SAP | NetSuite, Sage Intacct, Sage 300 and X3, Dynamics, SAP, Acumatica, Xero, QuickBooks, Zuora | NetSuite, Sage Intacct, Dynamics |
| Late fee grain | Yes (per customer group) | None found | Yes (one set of late-fee rules, across the account or for selected debtors, not tied to schedules) | None found | Not documented |
| Statements | Yes (any schedule, parent and child consolidated) | Yes (monthly) | Yes (monthly, fixed day) | Yes | Not documented |
| Payment plans | Yes (on Pro) | Yes (must be enabled by support) | Yes (chasing follows the invoice due date) | Limited (a single invoice cannot be split) | Not documented |
| Portal | Yes | Yes | Yes | Yes | Yes |
| Credit checks | Yes: native checks from payment behavior, plus Creditsafe via API on the Custom plan | Yes (Experian data, risk groups) | Yes (Creditsafe) | Yes (credit applications, scorecards, limits) | Not documented |
| AI | Advanced Reads customer replies, drafts answers and follow-up actions (like PO updates) for your approval; MCP server for Claude, ChatGPT and other agents | Basic an AI email template generator as a paid add-on | Advanced Reads inbound AR emails and prepares suggested actions for a person to approve; payment prediction, prioritisation and a cash assistant | Basic AI cash matching and an assistant | |
| Rated (source, count) | 5.0 (84, Xero App Store) | 4.9 (35, Xero App Store AU) | 4.98 (374, Xero App Store) | 4.4 (156, G2) | Not documented |
The five tools in five checked facts
- Two of the five print a monthly price: Paidnice from £49 (US$69) and Chaser from £199. ezyCollect, Quadient AR and Versapay do not publish one.
- Each published price grows with something different: invoice volume (Paidnice) and revenue band (Chaser). ezyCollect uses active debtors, without a printed figure.
- Two of the five apply a late fee themselves: Paidnice (per customer group) and Chaser (one set of rules).
- Three of the five connect to both Xero and QuickBooks Online. ezyCollect shows a QuickBooks logo on its homepage but no connector page. Versapay connects to neither.
- AI that handles collections work or customer replies: Paidnice. AI that scores or predicts only: ezyCollect, Quadient AR and Versapay.
We checked each tool's own pricing, integration and help pages on October 26, 2026. "None found" in the data means the vendor's pages do not show the feature.
Where a cell reads "Not published" the vendor prints no price at all, and where it reads "None found" nothing in either direction could be found. Every price is the from-price the vendor itself printed, in its own currency, never converted.
1. Paidnice, best for Xero or QuickBooks Online
Best for: Distributors on Xero or QuickBooks Online.
Any size up to $50m a year, or 50,000 invoices a year
What is Paidnice best for?
For a wholesaler on Xero or QuickBooks Online that wants a different late fee and reminder rule running on each trade group at the same time, without a credit controller setting them manually.
- Fits
- Distributors on Xero or QuickBooks Online of any size up to $50m a year, or 50,000 invoices a year, with or without a credit controller
- Regions
- United States, Canada, United Kingdom, Australia, New Zealand, South Africa
- Entry cost
- £49 (US$69) a month on Essentials, covering 150 invoices, 600 emails and up to 2 team members; Pro from £74 (US$99) a month with unlimited users and no per-seat fee. Payment plans and sending from your own domain start on Pro. Charged in your own currency from a local price table, not converted from US dollars. Check current pricing with the vendor
- Rated
- 5.0 from 84 Xero App Store reviews; 4.9 from 14 on Capterra
- Awards
- Xero Global Small Business App of the Year 2025 and NZ Small Business App of the Year 2026
- Runs on
- Xero, QuickBooks Online, Stripe, Pinch Payments, CloudDepot, HubSpot, Pipedrive, Zapier. Newer ledgers such as Rillet, Campfire, Digits, DualEntry, Puzzle, Accounting Seed and Odoo on every plan through the closed testing program. NetSuite, Sage Intacct, MYOB, Sage Accounting and Dynamics 365 Business Central on the Custom plan only
- Late fees and interest
- Yes. Two charge types on the same customer group, an invoice late fee and a statement interest charge against the whole overdue balance, both raised on the ledger as Draft or Approved. Compounding is on by default. Multiple policies run at once because policies sit under customer groups
- Does best
- A separate late fee policy per trade group, so a buying group, a national account and a disputed-accounts group each run a different rule at the same time
What Paidnice adds to Xero or QuickBooks Online is the charging rather than the invoicing. Reminder sequences, statement schedules, installment plans and a payer portal all hang off customer groups, and the late fee policy hangs off the same group, so the rule governing a buying group is set once and then runs.
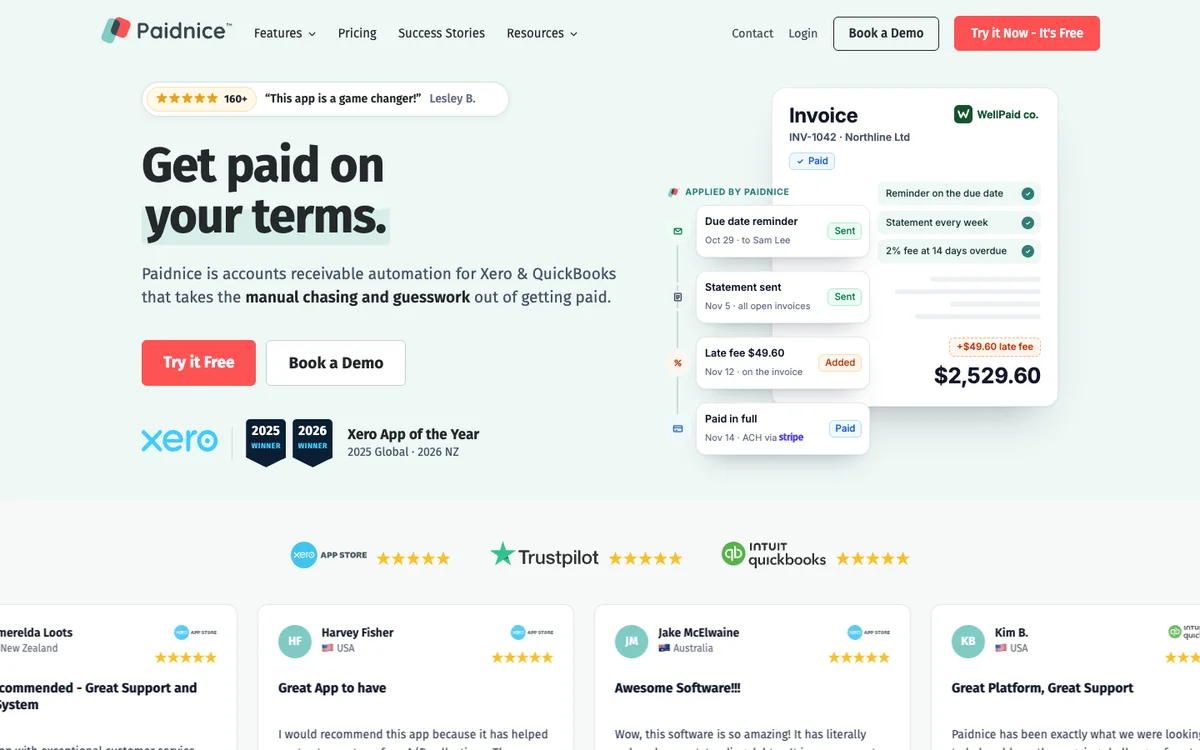
Email and SMS leave from your own authenticated domain, which matters when the reader is an accounts payable clerk paying two hundred suppliers and sorting the inbox by sender.
Two mechanics earn their place on a trade ledger specifically. Consolidated parent and child statements settle the way a buying group settles, one head office account rather than forty branch invoices arriving separately.
And the Adjust for Credit setting computes the charge on the balance after credits, so the credit note raised for a short shipment shrinks the fee instead of leaving a controller to explain on the phone why it did not.
Statement interest is recalculated at the moment the statement leaves rather than at the last policy run, so the figure the buyer opens is the figure that morning.
An invoice reference filter lifts one disputed line out of a policy without moving the account or switching the policy off, which is the working state of any distributor with returns in flight.
Limitations with Paidnice. Xero and QuickBooks Online are on every plan. Newer ledgers such as Rillet, Campfire, Digits, DualEntry, Puzzle, Accounting Seed and Odoo are available on every plan through Paidnice's closed testing program. NetSuite, Sage Intacct, MYOB, Sage Accounting and Dynamics 365 Business Central connect on the Custom plan, and other ERPs, SAP Business One among them, connect as a Custom-plan build.
Essentials stops at 150 invoices and two team members, a ceiling a busy trade ledger clears inside a month.
2. ezyCollect, best for ANZ trade credit screening
Best for: Australian and New Zealand distributors that screen trade credit before granting terms.
What is ezyCollect best for?
For an Australian or New Zealand wholesaler on MYOB, Pronto Xi or SAP Business One that wants a risk score on a buyer, then chasing, demand letters and collections referral in the same platform.
- Fits
- Receivables teams in Australia and New Zealand. Plans are sized by debtor count, 200 debtors on the entry tier up to 3,000. No revenue band published
- Regions
- Australia and New Zealand core, with US ACH payments; part of Sidetrade since October 2025
- Entry cost
- A$275/mo on ezyStart with annual billing, about A$330 month to month, plus setup from A$900; ezyGrow A$950 and ezyScale A$2,350. Current prices are hidden and must be requested. Last published on ezyCollect's pricing page, seen on the Wayback Machine.
- Rated
- 4.9 from 35 Xero App Store AU reviews; 4.7 from 25 on G2; 4.9 from 12 on Capterra
- Awards
- None found
- Runs on
- Xero, MYOB AccountRight, Exo, Essentials and Acumatica, NetSuite, Dynamics, Sage 300, Sage Intacct, SAP Business One, Pronto Xi, Attaché, JCurve; QuickBooks logo on homepage, no connector page
- Late fees and interest
- None found. No late fee or interest function appears in the help center or the relaunch materials; card surcharging is the only charge mechanic documented
- Does best
- Credit Insights: a risk score on a trade buyer built from your own aged trial balance and terms plus Experian external data, grouped into risk bands. Credit Insights is a premium add-on at extra cost
- Customers
- Named on its website: Martec, Sheffield Group and CW Systems. Martec's case study reports overdue accounts cut from 27% to 5%.
ezyCollect works the customer rather than the invoice, which is the correct shape when one buyer holds forty open lines against a single accounts payable inbox. Statements go out monthly, installments split by subscription, fixed amount or fixed count, and the SimplyPaid portal takes card and direct debit.
Its integration list is the deepest here for Australian and New Zealand distribution, reaching MYOB Exo, Acumatica, Pronto Xi and Attaché as well as Xero.
The escalation ladder also stays inside the platform, through demand letters and referral to a collections partner, so an account that stops moving does not have to leave the tool to get harder treatment.
Limitations with ezyCollect. Nothing in the help center or the relaunch materials documents a late fee or an interest calculation, so charging for the wait is a person's job. Installments exist as a paid add-on, so check the add-on price before you plan arrangements on trade accounts.
As last published, the entry tier adds setup from A$900, holds you to 200 debtors and one workflow, and costs 20 percent more billed monthly than annually. A buyer that runs past the end of a workflow stops being followed up, which a long tail of trade accounts will do.
Mail, SMS and fax are metered, demand letters are charged one at a time, and a referred account runs at commission from 25 percent of what is recovered. Reviewers report quotes well above the advertised tier.
3. Chaser, best for bureau checks and letters
Best for: Distributors that want credit checking and letters in the same tool, up to £4m on the entry tier.
What is Chaser best for?
For a distribution finance team with a named credit controller that wants Creditsafe credit checks, email, SMS and posted letters running from one system.
- Fits
- Businesses with a named credit controller; Compact is priced for revenue under £4m, and the tiers run to £100m
- Regions
- UK-registered, trading since 2014, sells worldwide
- Entry cost
- £199/mo on Compact for turnover under £4m with 4 users; Core £599/mo under £10m; Complete £899/mo to £100m.
- Rated
- 4.98 from 374 Xero App Store reviews; 4.3 from 71 on G2; 4.9 from 45 on Capterra
- Awards
- Finalist, UK Small Business App Partner of the Year, Xero Awards 2023
- Runs on
- Xero, QuickBooks, Sage 50, Sage 200, Sage Intacct, Sage Business Cloud Accounting, NetSuite, Dynamics 365 Business Central, AccountsIQ, SAP, HubSpot, Gmail, Outlook
- Late fees and interest
- Yes. Four calculation types including a Bank of England base rate type, recalculated daily, but one set of late-fee rules, across the account or for selected debtors, not tied to schedules, with no documented way to run different rules per group. No fee is raised on payment-plan invoices, and Chaser's help says a late fee cannot be added or updated after a part payment when written to Xero
- Does best
- Creditsafe credit checking and monitoring in the same tool as email, SMS and letter chasing
- Customers
- Named on its website: Gipsy Hill Brewery, Pact Coffee and Minor Figures.
Chaser has traded since 2014 and sends from the team's own Gmail or Outlook mailbox, with SMS, posted letters, a payer portal and partner collections layered on.
The posted letter is worth more in distribution than in most sectors: a buyer that has stopped replying to email will still open an envelope addressed to the registered office, and a warehouse credit controller usually knows exactly which accounts those are.
The in-app credit report comes from Creditsafe, carrying a score, a recommended limit, the buyer's payment score, credit event history, and Companies House filing and director data, with monitoring alongside, which covers the UK, USA and Canada but not Australia. Chaser credit checks need Chaser billing, not Xero App Store billing, and are sold by credit on any plan.
For a distributor the recommended limit is the only figure on that report that changes a decision, because it is the one that says how much stock goes out on terms.
Limitations with Chaser. One set of late-fee rules, across the account or for selected debtors, not tied to schedules, with no documented way to run different rules per group, so the buying group and the cash-terms account are charged the same way if both are covered. No fee is raised on a payment-plan invoice, and Chaser's help says a late fee cannot be added or updated after a part payment when written to Xero.
Installments split weekly through to yearly, but the chasing follows the original due date rather than the installment dates, and Chaser's own documentation says to chase the installments manually. Statements are monthly, on a fixed day. Compact holds the team to four.
Letters, SMS, calls and credit checks all draw metered credits above the plan allowance. And the entry price is tiered on company turnover rather than invoice volume, the wrong metric for a high-revenue, thin-margin wholesaler.
4. Quadient AR, best for remittance matching
Best for: Distribution groups that need cash application at remittance volume, quote only.
What is Quadient AR best for?
For a distribution group on NetSuite, Sage Intacct or SAP where the bottleneck is matching remittances to hundreds of open invoices rather than sending reminders.
- Fits
- Upper mid-market and enterprise distributors. No revenue band published
- Regions
- Sold globally as the accounts receivable pillar of Quadient's digital suite; formerly YayPay, founded 2015 in New York and acquired by Quadient in July 2020
- Entry cost
- Not published. Quadient quotes by demand. Capterra lists a starting price of $500 per feature per month, and third-party estimates last seen put implementation from $5,000. None of those figures are vendor-published.
- Rated
- 4.4 from 156 G2 reviews; 4.5 from 33 on Capterra
- Awards
- IDC MarketScape Leader, December 2024; SPARK Matrix Leader, June 2026
- Runs on
- NetSuite, Sage Intacct, Sage 300 and X3, Dynamics, SAP, Acumatica, Xero, QuickBooks, Zuora, Salesforce
- Late fees and interest
- None found. No native late fee or interest module appears in the help documentation
- Does best
- Cash application, with remittance association and auto-allocation, plus machine-learning payment date predictions running at 83 to 94 percent accuracy
Quadient AR is a rules engine sitting over a distribution ledger. Triggers fire on customer-level events, a balance threshold crossed, a buyer reaching 90 percent of its credit limit, a score change, and on invoice-level events, a partial payment landing in the ERP, a dispute opening, a promise to pay broken.
The credit-limit trigger is the one a distributor buys it for, because it is the event that should stop the next order rather than start the next reminder.
Credit application forms, scorecards and a disputes module sit next to it, and cash application allocates against remittance advice instead of leaving a clerk to match one deposit to eleven invoices. Payment date predictions order the collections list.
Limitations with Quadient AR. No late fee or interest module is documented, so the charge goes back to the ERP. A single invoice cannot be split into installments in the portal, and an arrangement means a support ticket, which is slow when a national account asks to stage a large order.
Sending runs through one shared receivables mailbox, with no per-specialist mailboxes and no distribution lists, so a team that splits the ledger by territory cannot split the sending. Write-back to the ERP covers NetSuite and Sage Intacct only, is off by default, and abandons delivery attempts after seven days.
No price is published at any tier, and reviewers return to payment failures and support response times.
5. Versapay, best for distributors on NetSuite
Best for: North American distributors on NetSuite, Sage Intacct or Dynamics.
No price published
What is Versapay best for?
For a North American distributor that wants trade buyers viewing, disputing and paying invoices in a shared portal instead of by email.
- Fits
- United States and Canadian mid-market distributors already on an ERP. No revenue band published
- Regions
- United States and Canada
- Entry cost
- Not published. Versapay prints no figures anywhere in its public materials
- Rated
- 4.1 from 101 G2 reviews; 4.4 from 30 on Capterra
- Awards
- None found
- Runs on
- NetSuite, Sage Intacct, Dynamics. No Xero or QuickBooks Online connector
- Late fees and interest
- Not documented. Nothing the vendor publishes covers late fees, interest or payment plans
- Does best
- Collaborative accounts receivable: a shared buyer-facing portal where a trade customer views the invoice, raises the dispute and pays, with the conversation attached to the invoice
- Customers
- Named on its website: TireHub, Wurth Canada and Carter Lumber. Wurth Canada's case study reports time on accounts receivable cut by 75%.
Versapay puts receivables automation and business-to-business payments in the same product, and it keeps a wholesale distribution page alongside manufacturing and professional services.
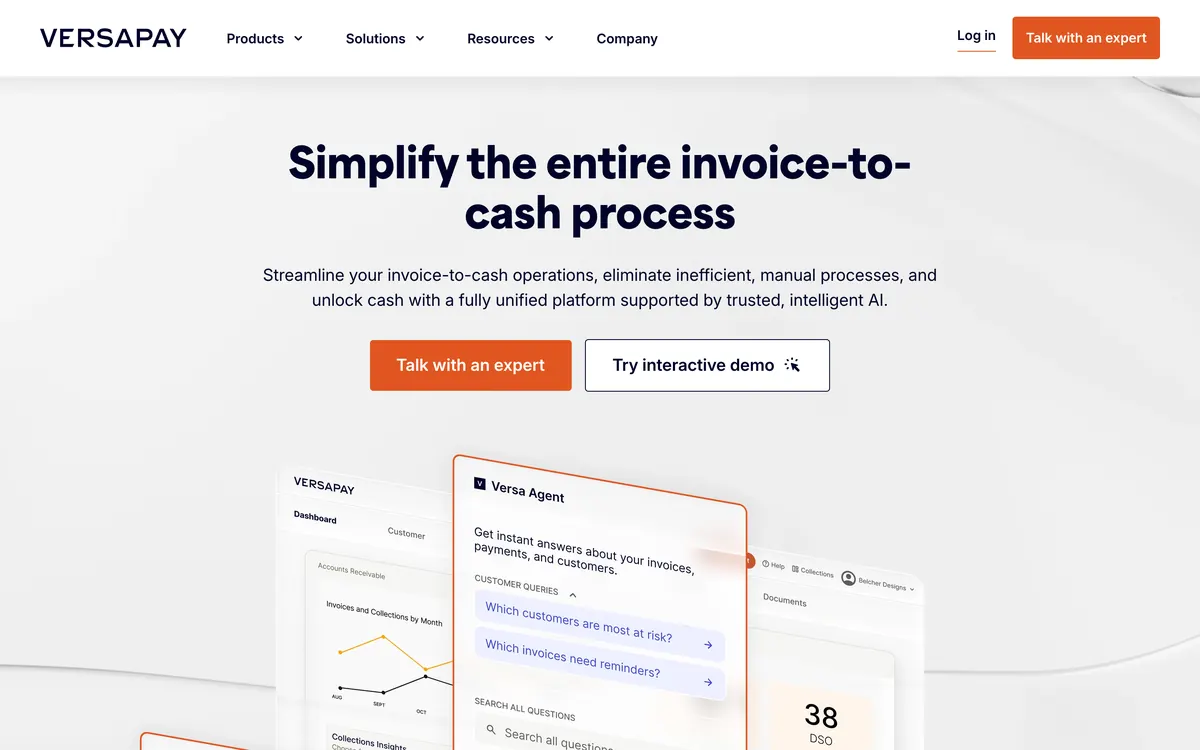
The portal is the whole argument. A short-shipment dispute that normally consumes three email threads and a phone call instead sits against the invoice, with both sides reading the same record. For a distributor whose deductions and claims are the real reason invoices age, that is the part to evaluate.
Limitations with Versapay. There is no Xero or QuickBooks Online connector at all, which removes it from consideration for any distributor on either ledger.
It publishes no price and the feature inventory is not documented, so two of the five criteria cannot be scored for it. Nothing it publishes describes a late fee, an interest calculation or an installment schedule.
Stop-supply, credit limits and the order that ships anyway
In distribution the receivable decision and the supply decision are the same decision. The question a credit controller carries to a sales manager is about the next order rather than the fourth reminder: does it go on the truck while the last one is unpaid?
A wholesaler holding a 6 percent net margin has to sell roughly seventeen more pallets to replace the profit on one that is never paid for, so the cheapest recovery available anywhere on the ledger is the order that was held.
Three of the five reach into that decision, and they reach different distances. ezyCollect builds Credit Insights from your own aged trial balance and the terms you granted, adds Experian bureau data, and sorts the ledger into risk groups.
What the software changes is whether the person keying the order knows the account is at 92 percent of its limit that morning, rather than at the aged trial balance review three weeks later.
Where AR software stops and trade credit insurance starts
Receivables software works your own ledger. It chases what has already been invoiced, raises the charge, issues the statement and takes the payment. Trade credit insurance does none of that: it pays a claim after a covered buyer fails, and charges a premium in the meantime. Most distributors carry both, against different halves of the same exposure.
A wholesaler extending terms across several hundred accounts, raising a high volume of thin-margin invoices, finances that gap continuously, order by order, and no policy reimburses a day of it.
What a distribution buyer should be checking:
- Grain on the enforcement. One rule per customer group rather than one rule for the whole ledger, because a buying group, a national account and a fortnight-old trade account were never on the same terms.
- A number before the terms are set. A bureau score with a recommended limit turns the exposure into a decision somebody made rather than a figure somebody discovered.
Putting a figure on the pallets you are financing
Annual sales over 365 is one day of sales. That figure multiplied by your days sales outstanding is the cash standing out in the ledger at any moment.
Take days off the DSO and you release exactly that many days of sales, once, as cash you do not have to borrow.
A $12,000,000 distributor at 45 days DSO has $1,479,452 out on the road. Ten days forward returns $328,767 and settles DSO at 35 days.
Which tools can charge interest on a trade account without losing it?
Two of the five compute the charge themselves. Paidnice attaches a policy to a customer group and posts the result to the ledger. Chaser offers four calculation types behind one set of late-fee rules. No interest mechanic is documented for ezyCollect or Quadient AR, and Versapay does not document its handling.
Chaser applies one set of late-fee rules, across the account or for selected debtors and not tied to schedules, with no documented way to run different rules per group, so terms negotiated separately with a buying group, a national account and a fortnight-old cash customer are enforced identically, and no fee is raised at all on an invoice that is part paid or on a plan.
Paidnice hangs its policies under customer groups, so those three run three rules simultaneously, with an invoice-level fee and a statement-level interest charge available on the same group and the calculation taken net of credits on the account.
Losing the account is the real reason distributors leave the fee switched off. A charge landing with no warning on a twelve-year buying relationship reads as a change of terms.
A charge written into the trading agreement, appearing on the statement every month it is earned, and waived in writing when the buyer rings, reads as a policy.
Shipping into the United Kingdom moves the charge from contract to statute.
The Late Payment of Commercial Debts (Interest) Act 1998 entitles a supplier to interest on an overdue business-to-business invoice at 8 percent a year over the Bank of England base rate, with a fixed sum of £40, £70 or £100 on top according to the size of the debt.
The base rate moves several times a year, so an invoice left long enough spans two or three of them and the correct figure is prorated across each period rather than taken at whatever the rate is today. Check the current one on GOV.UK before you invoice for it.
EDI, buyer portals and the remittance that never matches
A distributor selling into grocery, hardware or industrial chains is paid by a portal, on a payment run, in one deposit covering fourteen invoices, with a deduction against two of them.
An order arriving over EDI still lands in the ledger as an invoice, so every tool here tracks and chases it the way it tracks anything else.
None of the five reads Coupa, SAP Ariba or a grocery supplier portal, so the status the buyer can see, approved, or held for a missing purchase order line, or rejected on a price mismatch, is invisible to the tool sending the reminder. The reminder says overdue while the portal says queued for the 25th.
The one mechanism that helps is remittance parsing: reading the advice attached to a lump payment and allocating it across the open items. Quadient AR does this as a dedicated cash application module with auto-allocation against remittance advice.
None of the other tools here does. Paidnice, Chaser and ezyCollect read what the ledger says has been paid, so a bulk deposit stays a bulk deposit until somebody splits it, and every invoice inside it keeps looking overdue until they do.
The deduction is the part worth being deliberate about. A short payment against a claim, a shortage, a rebate accrual or a damaged pallet is a dispute rather than arrears.
Whichever tool you pick, the disputed line has to be lifted out of the sequence before it escalates: Paidnice does that with an invoice reference filter, Quadient AR with a disputes module, and on Chaser it means moving the account.
Terms by buyer type: buying group, national account, cash customer
Revenue is the wrong axis for a distributor, because two wholesalers of identical size can hold completely different books.
- Buying groups and head office accounts. Settlement is consolidated, so the statement decides more than the reminder does. Paidnice is the tool here that sends a parent and child statement on a schedule you set; Chaser sends one monthly, on a fixed day.
- National accounts on their own paper. The buyer sets the terms, pays through a portal and deducts for claims. Quadient AR and Versapay are built for that shape and neither prints a price, so the evaluation is a demonstration and a quote rather than a signup.
- The long tail of trade accounts. Hundreds of small buyers, thin margins, no credit controller. Paidnice at £49 (US$69) a month is the only entry price here a business of that size signs off without a meeting, and ezyCollect's 200-debtor entry tier is the first constraint to check if you are in Australia or New Zealand.
- New and cash-terms customers. This is a screening decision rather than a chasing decision. ezyCollect's Credit Insights or Chaser's Creditsafe report is what you are buying, and the chasing arrives with it.
The ERP question, and what it removes from your shortlist
A wholesaler that has already moved to Pronto Xi, SAP Business One or MYOB Exo has a shorter shortlist than one still on Xero. The enforcement tools are built on the small-business ledgers, and the ERP tools are the ones that print no price.
- Still on Xero or QuickBooks Online. The widest field on this page: Paidnice, Chaser and Quadient AR connect, and ezyCollect shows a QuickBooks logo on its homepage but no connector page. Versapay connects to neither, which settles it.
- MYOB, Pronto Xi, Attaché or SAP Business One. ezyCollect lists a connector for each of them. Paidnice reaches any ERP through a Custom-plan implementation, so consider Paidnice for the chasing and late fees around them.
- NetSuite or Sage Intacct. Quadient AR and Versapay, with Chaser connecting as well. Paidnice reaches both on its Custom plan only, as a build rather than a standard connector, so treat it as a project.
- Dynamics 365 or SAP. Quadient AR and Chaser, plus Versapay on Dynamics. Nothing at this end of the list publishes a price.
What this costs a distributor, per warehouse
The metric matters more than the headline, and on this page the metric is debtor count. ezyCollect prices in debtor bands starting at 200, which is the binding constraint on a distributor with a long tail of trade accounts and the usual reason the advertised entry price is not the price quoted.
Paidnice prices on invoice volume, flat, with unlimited users above the entry plan. Chaser prices on company turnover, which for a high-revenue, thin-margin wholesaler is the worst of the three, because it lands you in a tier built for a business making several times your gross profit.
The metered lines are where a distribution budget moves. ezyCollect charges A$49 plus GST for each demand letter and takes commission from 25 percent on a referred account. Chaser meters letters, SMS, calls and credit checks against a plan allowance, and a wholesaler running letters across a long tail will pass that allowance.
Per warehouse is the comparison that survives a group. A second site adds invoices and adds debtors, and usually adds no revenue-tier jump, so a volume-priced tool costs a little more, a debtor-priced tool costs a lot more, and a turnover-priced tool costs the same until the year the group total crosses a line.
Which accounts receivable software for wholesale and distribution fits your use case?
| Use case | Start with | Watch out |
|---|---|---|
| Buying groups that settle on one head office statement | Paidnice | Essentials stops at 150 invoices |
| Long tail of small trade accounts with no credit controller | Paidnice | Xero and QuickBooks Online on every plan; ERPs on Custom |
| Screening new buyers in Australia or New Zealand | ezyCollect | No late fees; 200-debtor entry tier |
| Creditsafe limit before stock goes out on terms | Chaser | Metered credits for letters, SMS and checks |
| Matching lump remittances to open invoices on NetSuite or SAP | Quadient AR | No published price and no late fee module |
| National accounts disputing through a portal in North America | Versapay | No Xero or QuickBooks Online connector |
Questions distributors ask
What is the best accounts receivable software for wholesale and distribution?
On Xero or QuickBooks Online, Paidnice, because each trade group carries its own late fee and interest policy and the charge is posted to the ledger, from £49 (US$69) a month.
If the bureau score is the reason you are buying, Chaser at £199 a month, or ezyCollect at A$275 a month for ezyStart (last published; current prices hidden and must be requested) in Australia and New Zealand.
Which of these tools apply late fees and interest automatically?
Two of them: Paidnice attaches the policy to a customer group, carries an invoice fee and a statement interest charge on that same group, and posts the result to the ledger as Draft or Approved.
Chaser has four calculation types recalculated daily behind one set of late-fee rules, raises no fee on payment-plan invoices, and its help says a late fee cannot be added or updated after a part payment when written to Xero. ezyCollect and Quadient AR document no interest function, and Versapay does not document its handling.
Why do distributors need credit screening in an AR tool?
Because a buyer that looked creditworthy at onboarding can slide quietly, and on distribution margins one default wipes out the profit on a long run of good orders.
ezyCollect scores a buyer from your own aged trial balance plus Experian data, Chaser supplies a Creditsafe report with a recommended limit and continuous monitoring, and Quadient AR can trigger a workflow when a buyer passes 90 percent of its credit limit.
How much does accounts receivable software cost for a distribution business?
Essentials on Paidnice is £49 (US$69) a month for 150 invoices and two users, and Pro runs from £74 (US$99) with unlimited users. ezyCollect is A$275 a month for ezyStart (last published; current prices hidden and must be requested) billed annually, roughly A$330 month to month, plus setup from A$900. Last published on ezyCollect's pricing page, seen on the Wayback Machine.
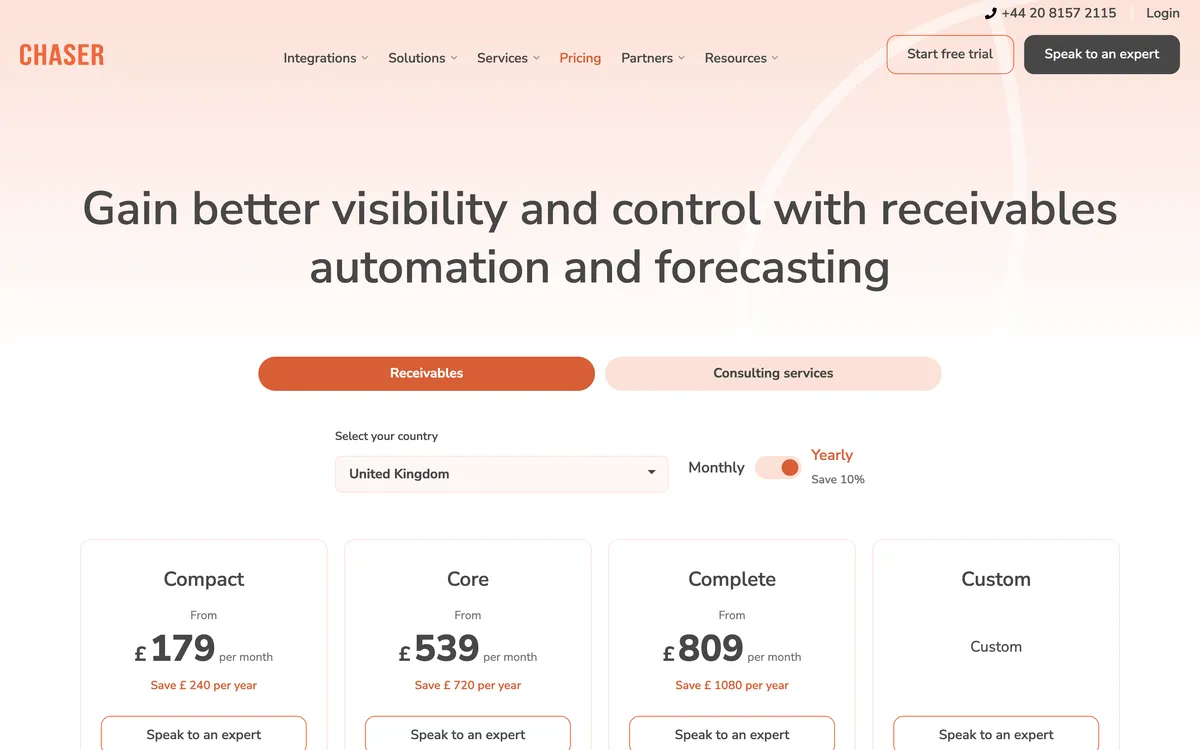
Chaser Compact is £199 a month for revenue under £4m. Above £4m a team is on Core from £599, and Complete is £899, while neither Quadient AR nor Versapay publishes a price.
Does this software work with EDI and large buyer portals?
The chasing runs off the ledger, so an invoice raised over EDI or through a buyer portal is tracked and chased exactly like any other. The return path is where they differ.
None of the five reads the buyer's portal, so approval status stays invisible; Versapay and Quadient AR answer that with portals of their own for large accounts, while Paidnice and Chaser leave the existing Xero or QuickBooks Online workflow alone and chase from it.
How much difference does automating collections actually make?
Paidnice reports that its customers have half as many late invoices in the first 30 days. Put that against a $12,000,000 distributor: ten days off DSO returns about $328,767 once, which on distribution margins beats the profit on the extra volume needed to raise the same figure.
To compare the same tools for any business type, read the best credit control software guide, which sets out six tools by size, ledger and price.
Related reading for distributors
Buyer's guide
Best accounts receivable software (by business type)
The pillar guide: pick by size and accounting system, with a recommendation matrix.
Construction
Best AR software for construction & trades
Chase retainage and slow general contractors, and enforce your terms.
Alternatives
Best Chaser alternatives
Six Chaser alternatives on enforcement, price and reviews.
Property
Best AR software for property management
Automate rent late fees and recurring tenant statements.
Sources
17 sources, checked by Julie Turnbridge on November 3, 2026
- Xero Small Business Insights xero.com/us/resources/small-business-insights
- Xero App Store apps.xero.com/app/paidnice
- Capterra capterra.com/p/254868/Paidnice
- Wayback Machine web.archive.org/web/20240617113004/https://ezycollect.io/...
- Xero App Store apps.xero.com/au/app/ezycollect
- G2 g2.com/products/ezycollect/reviews
- Capterra capterra.com/p/135729/ezyCollect/reviews
- Xero App Store apps.xero.com/uk/app/chaser
- G2 g2.com/products/chaser/reviews
- Capterra capterra.com/p/157101/CHASER/reviews
- G2 g2.com/products/quadient-accounts-receivable-by-yaypay/re...
- Capterra capterra.com/p/213360/YayPay
- G2 g2.com/products/versapay/reviews
- Capterra capterra.com/p/164271/VersaPay-ARC
- Late Payment of Commercial Debts (Interest) Act 1998 legislation.gov.uk/ukpga/1998/20/contents
- Bank of England base rate bankofengland.co.uk/monetary-policy/the-interest-rate-ban...
- GOV.UK gov.uk/late-commercial-payments-interest-debt-recovery/ch...

