The five best ezyCollect alternatives for 2026 are Paidnice, CreditorWatch Collect, Chaser, Upflow and Invoiced, compared on whether the tool applies late fees and interest itself and at what grain. Published entry prices from A$99 a month.
| Tool | Best for |
|---|---|
| Paidnice | Xero and QuickBooks Online businesses that want the late fee applied to the invoice |
| CreditorWatch Collect | Australian teams that want overdue accounts called |
| Chaser | Teams that want bureau credit checking and letters in the same tool, priced by company turnover |
What accounts receivable software is (and what it is not)
Accounts receivable software chases the invoices your ledger already holds. It reads open invoices from Xero, QuickBooks Online or MYOB and works them through the reminder and escalation steps you set, until the customer pays.
On the tools in this guide, that work covers:
- Reminder workflows by email and SMS, with letters or calls on some tools
- Customer statements on a schedule
- Interest and late fees, on the three tools that raise them
- A payment portal, plus payment plans or recurring direct debit
- Credit screening, demand letters and referral to a collections agency
It is not your ledger. Xero, QuickBooks Online or MYOB holds the invoice and the payment. A tool that raises an interest charge should post it back to that ledger as an invoice, where the customer’s accounts clerk has to schedule it.
It is not a credit bureau. Experian and CreditorWatch supply the credit data, and a tool either bundles that data or leaves it as a subscription of your own.
It is not a collections agency or a lender. The agency referral on ezyCollect and CreditorWatch Collect hands the debt to a third party on commission, and a finance provider that settles the invoice sells a different product.
It does not set your interest rate either. In Australia and New Zealand the rate comes from your signed terms of trade, and the software applies it. Reminders and statements alone are a full use case, and interest is optional.
How this list was put together
This list helps an Australian or New Zealand business leaving ezyCollect find a tool that applies late fees and interest itself.
| What we checked | Where the evidence came from |
|---|---|
| Late fee grain | Vendor help pages on fees and interest |
| Ledger integrations, including MYOB | Vendor integration pages |
| Statements, payment plans and a portal | Vendor feature pages |
| Credit checks | Vendor product pages |
| Published from-price | The vendor's pricing page, with "Not published" where there is none |
| Rating and review count | The Xero App Store or G2 |
How long do Australian and New Zealand customers take to pay, and is there a statutory rate?
The figure that matters more on this page is a legal one: there is no Australian or New Zealand equivalent of the United Kingdom’s Late Payment of Commercial Debts (Interest) Act, so no statutory rate exists for anybody to fall back on.
On Xero Small Business Insights data for June 2026, the wait to be paid in Australia is 20.3 days against 24.6 a year earlier, and the average invoice now settles 4.3 days past due rather than 7.0. The manufacturing and hospitality figures are from the same month, and what separates them is trading terms rather than software.
That absence changes what you are shopping for. A British business choosing credit control software is choosing whether the tool can apply a rate the law has already set. An Australian or New Zealand business is choosing whether the tool can apply the rates its own customers agreed to, and those are not all the same rate.
What lets you charge interest on an overdue invoice in Australia and New Zealand?
In Australia and New Zealand the right to charge interest on an overdue trade invoice comes from your contract rather than from a statute. Whatever your terms of trade and your signed credit application say is what you may charge.
Which puts the document ahead of the software, and the document is worth checking first, because most of the arguments a customer makes about a late fee turn out to be arguments about paperwork rather than about the amount. Four things a term has to do to be worth invoking:
- State the rate, and state what it is a rate of. A percentage per annum, applied to the overdue balance, accruing daily from the due date. A term that says interest may be charged without naming a number is a term you will end up negotiating.
- Live in the document the customer signed. A credit application or a signed terms of trade carries more weight than a line printed on the invoice, because the invoice arrives after the agreement rather than forming it.
- Cover recovery costs separately. There is no fixed statutory sum here as there is in Britain, so if you want the cost of chasing back, the term has to say so on its own account.
- Match what you actually do. A rate you have never charged anybody is harder to enforce on the one customer you finally decide to charge it to.
A business that has been trading for a decade is trading on several generations of terms at once: customers signed in 2016 on one rate, customers signed since the last review on another, a handful on negotiated terms written into a supply agreement, and a group in dispute you would not charge at all.
A tool carrying one interest setting can serve exactly one of those groups correctly. That is why grain, rather than the mere presence of a fee feature, is what this page compares.
Which ezyCollect alternatives suit an ANZ receivables team?
Paidnice, Chaser and Invoiced are the three of the five that document a late fee or interest charge, and Paidnice and Invoiced can run more than one schedule at a time.
CreditorWatch Collect is the closest Australian like-for-like on chasing and escalation, and it puts people on the phone. Upflow and Invoiced sit above the small business band and neither lists a MYOB connector.
 |
 |
 |
 |
 |
|
|---|---|---|---|---|---|
| Best for | Interest per customer group, on Xero or QuickBooks Online | Australian teams that want overdue accounts called | Creditsafe checks and letters in one tool | Collections metrics for larger, ledger-agnostic finance teams | United States invoice-to-cash on a mid-market ERP |
| Revenue fit | Priced by monthly invoice volume, from 150 invoices | Not published (tiered by debtor count) | Compact under £4m, Core from £4m, Complete to £100m | Gross invoice value tiers, up to $10m through above $100m | Not published |
| From (monthly) | A$99 | Not published | £199 | Not published | Not published |
| Ledger integrations | Xero, QuickBooks Online and newer ledgers such as Rillet and Campfire (closed testing) on every plan; MYOB, Sage Accounting and other ERPs on Custom | Xero, MYOB, QuickBooks (NetSuite and Dynamics 365 on the Custom plan) | Xero, QuickBooks, Sage, NetSuite, Dynamics 365 Business Central | Xero, QuickBooks Online, NetSuite, Sage Intacct, Stripe Billing, Chargebee, Zuora | NetSuite, Sage Intacct, Dynamics 365 Finance, Xero, QuickBooks Online |
| Late fee grain | Yes (per customer group) | None found | Yes (one set of rules for the account) | No (via your ERP only) | Yes (schedules by customer group) |
| Statements | Yes (any schedule) | Yes | Yes (monthly, fixed day) | Portal PDF statement, no scheduled send | Not documented |
| Payment plans | Yes (on Pro) | Partial (AutoPay recurring direct debit, no instalment plans) | Yes | No | Not documented |
| Portal | Yes | Yes | Yes | Yes | Yes |
| Credit checks | Yes: native checks from payment behaviour, plus Creditsafe via API on the Custom plan | Yes (parent payment scores, not bureau data inside Collect) | Yes (Creditsafe) | Yes (light scoring) | None found |
| AI | Advanced Reads customer replies, drafts answers and follow-up actions (like PO updates) for your approval; MCP server for Claude, ChatGPT and other agents | Basic AI account summaries (Debtor Intelligence); risk ranking is rule-based | Advanced Collections and cash application agents, from suggest-only to autonomous (Collections Agent from Scale, Cash Application Agent from Accelerate) | Advanced Agentic AI (Assist, Automate, Advise) and CashMatch AI matching | |
| Rated (source, count) | 5.0 (84, Xero App Store) | 4.9 (91, Xero App Store) | 4.98 (374, Xero App Store) | 4.8 (235, G2) | 4.7 (149, Capterra) |
"Not documented" means the vendor does not document the capability. "Not published" means the vendor does not print a price. "None found" means no evidence either way. Prices are the vendor's published from-price.
The six tools in five checked facts
- Two of the six print a monthly price: Paidnice from A$99 and Chaser from £199. ezyCollect, CreditorWatch Collect, Upflow and Invoiced quote.
- The two published prices grow with different things: invoice volume (Paidnice) and revenue band (Chaser).
- Three of the six apply a late fee themselves: Paidnice (per customer group), Invoiced (schedules by customer group) and Chaser (one set of rules).
- All six connect to Xero. Five of the six connect to QuickBooks Online; ezyCollect shows a QuickBooks logo on its homepage but no connector page.
- AI that handles collections work or customer replies: Paidnice, Upflow and Invoiced. AI that does not handle replies: ezyCollect (email templates) and CreditorWatch Collect (account summaries).
We checked each tool's own pricing, integration and help pages. "None found" in the data means the vendor's pages do not show the feature.
1. Paidnice, best for late fees and reminders
Best for: Xero and QuickBooks Online businesses that want the fee applied as well as the reminder sent.
What is Paidnice best for?
For a business on Xero or QuickBooks Online that wants a late fee and an interest charge raised on the customer's ledger, at a price it can read off a page.
- Fits
- Small and mid-sized businesses on Xero or QuickBooks Online. Priced by monthly invoice volume rather than by revenue band, from 150 invoices on the entry tier up to 4,000 and above on Custom
- Regions
- Australia, New Zealand, United Kingdom, United States, Canada, South Africa
- Entry cost
- A$99/mo on Essentials, covering 150 invoices, 600 emails and up to 2 team members; Pro from A$139/mo with unlimited users and no per-seat fee. Prices come from a fixed local price table rather than a conversion, so the same tier is US$69, £49 or NZ$109. Extra Xero or QuickBooks organisations are a multi-entity add-on from A$39 each a month
- Rated
- 5.0 from 84 Xero App Store reviews; 4.9 from 14 on Capterra
- Awards
- Xero Global Small Business App of the Year 2025 and NZ Small Business App of the Year 2026
- Runs on
- Xero, QuickBooks Online, Stripe, Pinch Payments, HubSpot, Pipedrive, Zapier. Newer ledgers such as Rillet, Campfire, Digits, DualEntry, Puzzle, Accounting Seed and Odoo are available on every plan through Paidnice's closed testing program. NetSuite, Sage Intacct, MYOB and Dynamics 365 Business Central on the Custom plan only
- Late fees and interest
- Yes. Two charge types run on the same customer group, an invoice late fee and a statement interest charge, both posted to the ledger as Draft or Approved. Compounding is on by default and the charge is calculated on the balance net of any credit on the account
- Does best
- Statement interest recalculated at the moment the statement sends rather than at the last policy run, so the figure the customer opens is accurate that morning
Paidnice is the enforcement layer on top of Xero and QuickBooks Online: reminder sequences per customer group, statements on the schedule you set including consolidated parent accounts, payment plans through Stripe and Pinch on Pro, and a customer payment portal. Reminders send by email and SMS from your own authenticated domain on Pro and above.
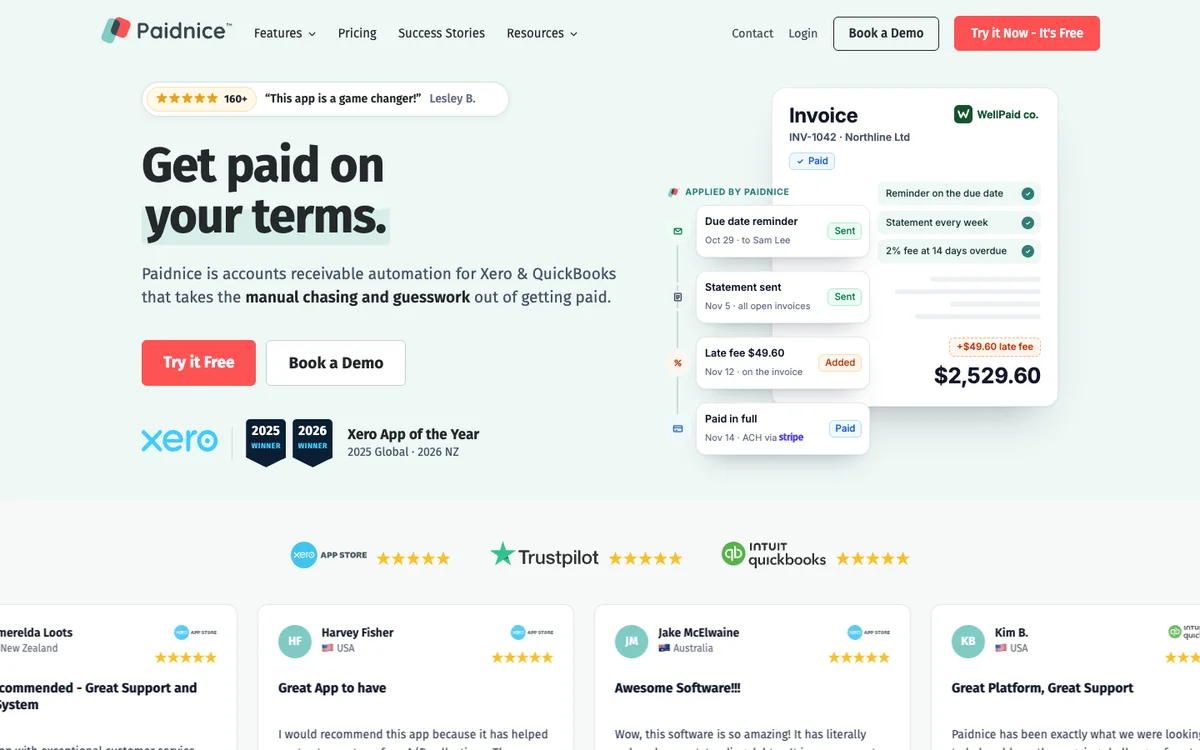
Policies sit under customer groups, which is what lets a business trading on several generations of signed terms run several rates at once: the accounts on the 2016 credit application, the accounts on the current one, and the ones on a negotiated supply agreement.
A single disputed invoice can be lifted out of a policy by its reference without moving the customer or switching the policy off. The vendor reports customers halving their average days to payment within a month of turning it on.
According to Paidnice, its AI handles the inbound side: it reads each reply and drafts the answer, and a person approves each drafted reply before it sends.
Limitations with Paidnice. MYOB is the sharpest constraint. It sits on the Custom plan as a build rather than a standard connector, where ezyCollect ships AccountRight, Exo, Essentials and Acumatica connectors as standard, so an AccountRight business has a conversation to have before anything else.
Native to Xero and QuickBooks Online otherwise. Essentials holds 150 invoices, 600 emails and two team members.
2. CreditorWatch Collect, best for account calling
Best for: Australian teams that want overdue accounts called as well as emailed.
What is CreditorWatch Collect best for?
For an Australian business that wants a calling queue and, if it wants, the vendor's own AR specialists making those calls through the paid Call Assist add-on.
- Fits
- Australian and New Zealand businesses on Xero, MYOB or QuickBooks. Tiering has run by debtor count rather than revenue, and the trial covers up to 50 debtors
- Regions
- Australia and New Zealand, with one-click escalation to debt collection and legal in Australia, New Zealand, the United Kingdom and the United States
- Entry cost
- Not published. Sales-led: a 14-day trial up to 50 debtors, then a custom quote with an account manager. CreditorWatch Collect's last published listing price was from A$175 a month, on Capterra. Current prices are hidden and must be requested. Call Assist human calling is a paid add-on at A$195, A$495 or A$795 a month.
- Rated
- 4.9 from 91 Xero App Store reviews, many of them written before the March 2023 rebrand from Debtor Daddy; 4.5 from 13 on Capterra
- Awards
- None found
- Runs on
- Xero, MYOB, QuickBooks, Zapier. Outlook, Slack, HubSpot and Salesforce appear through listings rather than native connectors
- Late fees and interest
- None found. No late fee, interest or surcharge function appears on the features page, in the help centre, in the FAQ or in third-party feature lists
- Does best
- The Call Console, a queue that fills itself with the accounts due a call, with quick response tags, expected payment dates and notes pushed back to Xero
CreditorWatch Collect is the former Debtor Daddy, founded in Christchurch in 2012, acquired by the credit bureau CreditorWatch in October 2022 and rebranded in March 2023. It sells as the third pillar of the parent's onboard, manage and collect suite, which is how most of its new customers arrive.
The human layer is the genuine difference. Call Assist, a paid add-on, puts trained local AR specialists on the phone on rules you set, with calls triggered from a workflow and every outcome logged: Assist at A$195 a month (20 calls included), Plus at A$495 (150) and Ultimate at A$795 (400).
Escalation to a collections agency or a lawyer is a click, charged on commission against what is recovered.
Limitations with CreditorWatch Collect. No late fee or interest anywhere in the product, so the gap that sends teams away from ezyCollect is still there. The Xero sync runs on a 24-hour cycle with a manual trigger available, so a payment banked this morning can still draw a chase.
Review velocity has been close to zero since 2022, and there is no public API beyond Zapier.
3. Chaser, best for bureau checks and letters
Best for: Teams that want credit checking and letters in the same tool, priced by company turnover.
What is Chaser best for?
For a finance team with a named credit controller that wants email, SMS, letters and Creditsafe credit checks running from one system.
- Fits
- Businesses with a named credit controller. Chaser Compact is £199 a month for revenue under £4m. Above £4m a team is on Core from £599, and Complete runs to £100m
- Regions
- UK-registered, trading since 2014, sells worldwide. Automated calls are not available in New Zealand
- Entry cost
- £199/mo on Compact for revenue under £4m with 4 users; Core £599/mo under £10m; Complete £899/mo to £100m. Yearly billing is £179, £539 and £809 a month.
- Rated
- 4.98 from 374 Xero App Store reviews; 4.3 from 71 on G2; 4.9 from 45 on Capterra
- Awards
- Finalist, UK Small Business App Partner of the Year, Xero Awards 2023
- Runs on
- Xero, QuickBooks, Sage 50, Sage 200, Sage Intacct, Sage Business Cloud Accounting, NetSuite, Dynamics 365 Business Central, AccountsIQ, SAP, HubSpot, Gmail, Outlook
- Late fees and interest
- Yes. Four calculation types, recalculated daily, but one set of late-fee rules, across the account or for selected debtors, not tied to schedules, with no documented way to run different rules per group, and no fee is raised on payment-plan invoices. Chaser's help says a late fee cannot be added or updated after a part payment when written to Xero
- Does best
- Creditsafe credit checking and monitoring in the same tool as email, SMS and letter chasing
- Customers
- Named on its website: Pact Coffee, Huttie and TaxAssist. Huttie's case study reports £15,000 of old debt recovered.
Chaser has the widest ledger list in this comparison and is the only alternative here that pairs a fee engine with a credit bureau. Reminders leave from the team's own Gmail or Outlook mailbox on every plan, with SMS, physical letters, a payer portal and integrated collections behind them.
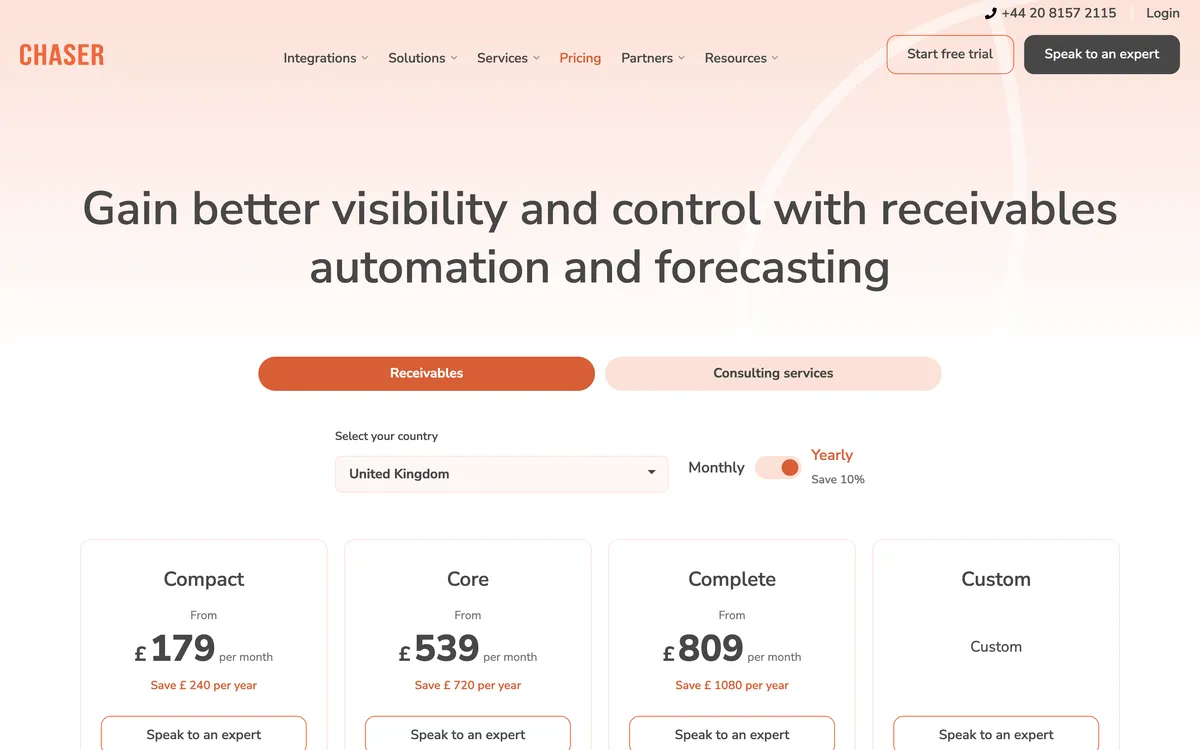
Its credit report comes from Creditsafe and carries a score with a recommended limit, the customer's payment score, credit event history and filing and director data, with monitoring over the top.
Read from Australia, two of those facts come with qualifications. Creditsafe reads a British company register, so its value on a domestic trade buyer is not what it is on a UK one, and the one-way automated calls are unavailable in New Zealand.
Limitations with Chaser. There is no MYOB connector. Creditsafe checks are not available to Xero App Store subscribers unless they move to Chaser billing, and monitoring does not cover Australia. Pricing steps with company turnover rather than usage, from £199 a month under £4m.
The late fee runs as one set of late-fee rules, across the account or for selected debtors, not tied to schedules, with no documented way to run different rules per group, and it raises nothing on a payment-plan invoice. Chaser's help says a late fee cannot be added or updated after a part payment when written to Xero. Statements are monthly, on a fixed day. Compact holds four users.
4. Upflow, best for reporting without MYOB data
Best for: Finance teams that want collections reporting and do not need MYOB, local credit data or a published price.
What is Upflow best for?
For a larger, ledger-agnostic finance team whose question is where the cash is stuck rather than what to charge the customer who is sitting on it.
- Fits
- B2B finance teams that manage by metric, quoted in five tiers by gross invoice value, from up to $10m on Starter to above $100m on Enterprise
- Regions
- New York head office, Paris origin, customers in 30-plus countries
- Entry cost
- Not published. Upflow prints no figures and quotes five tiers by gross invoice value; Upflow offers a free Discover dashboard tier and a 14-day free trial on its Xero App Store listing; its pricing page lists no trial. Upflow’s last published prices were $440 a month for Grow and $880 for Scale.
- Rated
- 4.8 from 235 G2 reviews; 4.5 from 15 on Capterra; 5.0 from a single review on the Xero App Store, too small a base to read as a quality signal
- Awards
- None found
- Runs on
- Xero, QuickBooks Online, NetSuite, Sage Intacct, Stripe Billing, Chargebee, Zuora
- Late fees and interest
- No, via your ERP only. Upflow's own documentation points the job back to the ERP and there is no native computation
- Does best
- Collections analytics, with countback DSO against best possible DSO, collection effectiveness and an at-risk rate above 90 days
- Customers
- Named on its website: Lattice, Vercel and Front. Lattice's case study reports 99% collection with one person in AR.
Upflow is a measurement product rather than a collections one, and on an Australian page it is a size and market mismatch that the entry should say plainly: pricing by gross invoice value aimed at scaling software companies, no MYOB connector, and no local credit data.
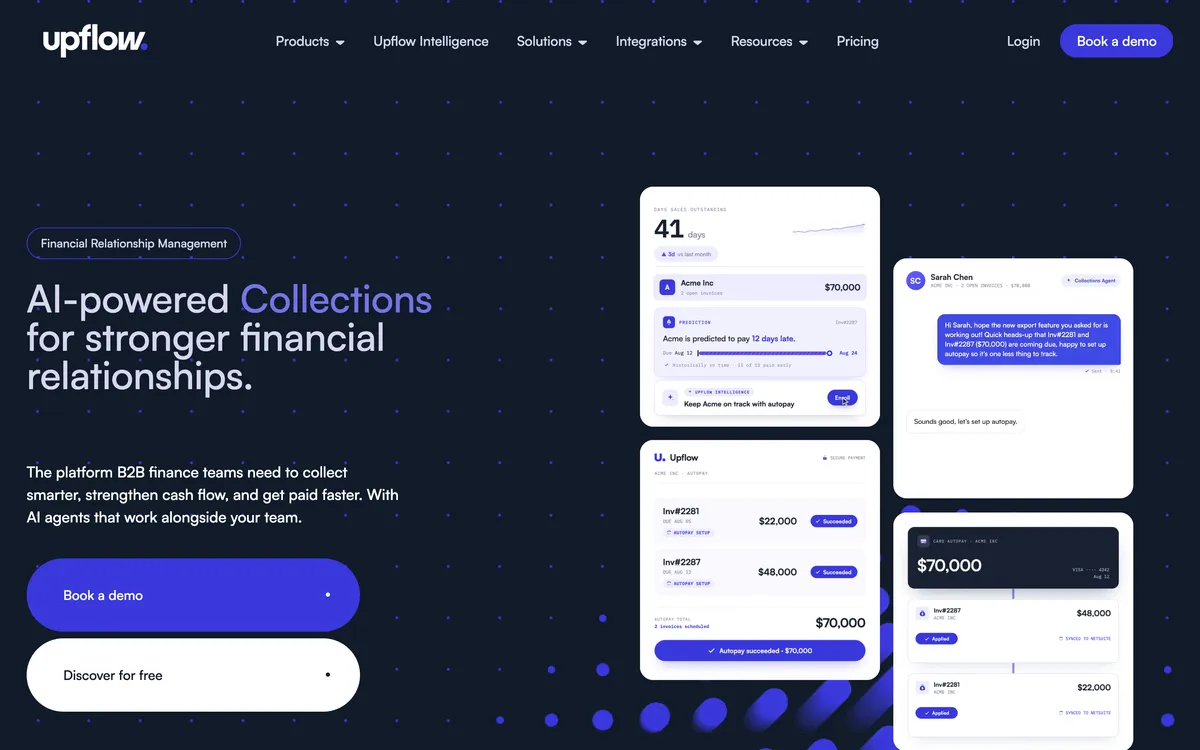
Limitations with Upflow. No native late fees, so fees go back to your ERP. No payment plans, only customer-initiated part payments and promises to pay. Automatic actions fire once a day, on business days only.
Sending through your own SMTP disables open and click tracking, and the QuickBooks link polls every five minutes with payments landing in Undeposited Funds for manual reconciliation. There is no MYOB connector, and its last published price ($440 a month for Grow) is now hidden, so request a quote.
5. Invoiced, best for US invoice-to-cash on ERPs
Best for: United States invoice-to-cash on a mid-market ERP, with no published price.
What is Invoiced best for?
For a United States billing operation on NetSuite, Sage Intacct or Microsoft Dynamics that wants the whole invoice-to-cash cycle in one platform.
- Fits
- United States mid-market and enterprise billing operations. No revenue band published, and the positioning has moved upmarket since the Flywire acquisition
- Regions
- United States focus, part of Flywire
- Entry cost
- Not published. No figure appears in the vendor's public materials, so get a written quote before committing.
- Rated
- 4.7 from 149 reviews on Capterra; 4.5 from 418 reviews on G2
- Awards
- None found
- Runs on
- NetSuite, Sage Intacct, Microsoft Dynamics, Workday, Xero, QuickBooks Online and QuickBooks Desktop
- Late fees and interest
- Yes. A flat or percentage fee with a grace period, raised as a separate invoice line, with multiple schedules assignable to customer groups and a per-invoice waiver. No fee on payment-plan invoices
- Does best
- Breadth of the invoice-to-cash cycle on a mid-market ERP, with eight maintained integration pages and a documented late fee use case
- Customers
- Named on its website: WebPT, iWave and Apartment Life. Apartment Life's case study reports overdue accounts cut by 50%.
Invoiced is a United States invoice-to-cash platform, now part of Flywire, that sells to controllers and AR managers on mid-market ERPs. It keeps Xero and QuickBooks integration pages live, but the product marketing, the persona pages and the gated research all point at a larger buyer than the one running ezyCollect today.
Limitations with Invoiced. No published price, so you are buying on a demo. No Australian ERP coverage, so an MYOB business is ruled out before the conversation starts. Late fees are documented on a use-case page, with schedules assignable to customer groups.
Credit data in this market: Experian, CreditorWatch and the PPSR
Credit Insights is built on Experian data. CreditorWatch Collect belongs to CreditorWatch, which is a bureau in its own right. Neither Paidnice nor Chaser carries an Australian or New Zealand bureau, so leaving ezyCollect usually means deciding where the credit data goes.
Three options:
- Keep a bureau subscription of your own. The screening becomes a line item you buy directly, dearer per report and cheaper overall if you were paying for scores you never used.
- Move to CreditorWatch Collect and keep it bundled. The parent is a bureau, though the adverse-data monitoring sits outside the Collect product, so check what the subscription includes.
- Move the control upstream, into the credit application. A signed application with trade references, a director guarantee where the exposure justifies one, and a stated limit does more work than a score checked once at onboarding and never looked at again.
The Personal Property Securities Register is routinely misread. A purchase money security interest, registered correctly and on time under retention of title terms, gives a supplier of goods a priority claim over the goods it supplied if the customer fails.
It secures nothing on a service, a fee, an interest charge or goods already consumed or on-sold.
What ezyCollect does, and where an alternative fits
ezyCollect is Australian order-to-cash software: invoice delivery, customer-level reminder workflows, statements, payment plans, a payment portal, Experian-backed credit screening and referral to a collections partner. It applies no late fee and no interest anywhere in the product.
Founded in Sydney in 2014, it was acquired by Sidetrade in October 2025 for around €37m with an earn-out running to 2028. It is rated 4.9 from 35 reviews on the Xero App Store, 4.7 from 25 on G2 and 4.9 from 12 on Capterra.
- No late fee or interest. The function is absent from the entire help centre and from the relaunch messaging. Card surcharging is the only charge the product raises.
- Cost that is not the headline. ezyCollect's last published prices were A$275 a month for ezyStart, with a setup fee from A$900. Current prices are hidden and must be requested. Last published on ezyCollect's pricing page, seen on the Wayback Machine. Prices are on a 12-month plan, monthly billing adds 20%, and mail, SMS, fax, demand letters at A$49 each and an A$90 a month payment gateway fee sit on top.
- Debtor-count pricing. The entry tier covers 200 debtors and three users. Growth in customer count, not in invoice value, is what moves you up a tier.
How do you charge interest without a statutory rate?
Three of these five raise a charge themselves. Paidnice runs a policy per customer group; Invoiced assigns fee schedules to customer groups; Chaser runs one set of rules with four calculation types.
With no statutory rate in this market, the rate is whatever your terms say, and the software's job is to apply it accurately and consistently. Two things it has to get right.
The arithmetic, which is the balance multiplied by the annual rate and apportioned across the days it ran late. And the boundaries, which is the harder half: which customers each rate applies to.
Different customers signed different terms
Chaser: one set of late-fee rules
- Four calculation types, recalculated daily
- One set of rules, across the account or for selected debtors
- Nothing raised on plan invoices
- No late fee added or updated after a part payment written to Xero
- Written back to Xero as a line item only
Paidnice: one setting per customer group
- As many rates as you have signed sets of terms
- A charge per overdue invoice and one against the balance
- Compounding on by default, figured net of credits
- Posted into the ledger as a Draft or Approved invoice
Wherever the rate comes from, it only becomes a consequence when it is posted into the ledger you invoice from. A charge that lives inside a chasing tool is a note about your customer in your own system.
A charge raised as an invoice in the ledger you actually bill from, whether that is Xero, QuickBooks Online or MYOB, arrives in their payables and their payment run as a line their accounts clerk has to schedule.
How do instalments work on an ANZ ledger?
Paidnice and Chaser schedule instalments against an open balance, and CreditorWatch Collect offers AutoPay recurring direct debit instead. Upflow takes customer-initiated part payments instead, and nothing could be verified for Invoiced. ezyCollect has plans too, sold as a paid add-on.
Two questions separate them, and neither appears on a feature grid. Who can create a plan, and what chases it afterwards.
Chaser splits an invoice weekly through to yearly, but the follow-up keeps tracking the original due date rather than the instalment dates, and its own documentation tells you to chase the instalments manually.
It also raises no late fee at all on an invoice that is on a plan, so on a plan-heavy ledger the fee policy quietly stops applying.
Paidnice runs deposits, instalments and auto-pay through Stripe and Pinch on Pro with the policy engine still live behind the plan. Upflow records a promise to pay and takes ad-hoc part payments, which is an intention rather than a schedule.
Keep the plan and the funding separate in your own head. An instalment plan leaves the receivable and the credit risk with you and only moves the dates. A finance provider settles the invoice and carries the risk itself, which is a different product at a different price.
What does ezyCollect cost once setup and letter fees are added?
Two of the five publish a price: Paidnice at A$99 a month and Chaser at £199. CreditorWatch Collect, Upflow and Invoiced publish nothing and quote on a call.
Read the unit before the figure, because no two of these charge for the same thing. ezyCollect and CreditorWatch Collect price by debtor count, so winning more customers moves you up a tier whatever those customers are worth to you.
Chaser prices by company turnover, so the bill steps when the business grows rather than when the chasing does. Paidnice prices by monthly invoice volume.
Then the extras, which on an ezyCollect subscription are half the story. ezyCollect's last published prices were A$275 a month for ezyStart, with a setup fee from A$900. Current prices are hidden and must be requested. Last published on ezyCollect's pricing page, seen on the Wayback Machine. Prices are on a 12-month plan; billed monthly, ezyStart is about A$330.
Mail, SMS and fax are charged on top, in-app demand letters cost A$49 each plus GST, the payment gateway costs A$90 plus GST a month, and card processing is 1.75% plus A$0.30. A collections referral is charged from 25% of what is recovered.
What a first year actually costs
At A$275 a month with an A$900 setup fee and 6 demand letters at A$49 each, the first year costs A$4,494.
One band this page does not cover: businesses collecting high volumes of low-value debts on behalf of other businesses. That is a different market with specialist platforms such as iCollect, and no published price or independent review base could be verified for it, so nothing from that tier appears above.
What ledger you run: Xero, MYOB, and the rest
Every tool here connects to Xero and QuickBooks Online, so those two lines decide nothing. MYOB is where the list gets short, and for a business running AccountRight or Exo that single row settles more than the rest of the feature grid put together.
- Xero. All five connect. CreditorWatch Collect syncs on a 24-hour cycle. Chaser's help centre says its Xero sync runs once a day and before reminders; its Xero listing says hourly. The others are closer to real time.
- QuickBooks Online. All five connect. Upflow polls every five minutes and lands payments in Undeposited Funds for manual reconciliation.
- MYOB. CreditorWatch Collect connects natively. Paidnice reaches MYOB on its Custom plan only, as a build rather than a standard connector, so it is a scoping conversation rather than a signup. Chaser, Upflow and Invoiced do not list MYOB at all.
- NetSuite, Sage Intacct and Dynamics 365. Chaser, Upflow and Invoiced. CreditorWatch Collect lists NetSuite and Dynamics 365 on its Custom plan. Paidnice reaches these on its Custom plan only.
Which ezyCollect alternative fits your use case?
Start from your ledger and from what you are leaving ezyCollect for.
| Use case | Start with | Why |
|---|---|---|
| Xero or QuickBooks Online, with customers on several sets of signed terms | Paidnice | A separate interest rate per customer group, from A$99 a month |
| MYOB AccountRight or Exo | CreditorWatch Collect | The only tool here with a native MYOB connector |
| Overdue accounts called by a person | CreditorWatch Collect | Call Assist from A$195 a month, with 20 calls included |
| Credit checks and letters in one tool | Chaser | Creditsafe reports and posted letters from £199 a month, with no MYOB connector |
| A larger team that wants collections metrics | Upflow | The clearest metrics here, with no MYOB, no local credit data and no printed price |
| A United States billing operation on NetSuite or Sage Intacct | Invoiced | Billing, collections and payments together, with no published price |
Questions from ANZ finance teams
What is the best ezyCollect alternative?
Paidnice is the best ezyCollect alternative for a business on Xero or QuickBooks Online that wants late fees and interest applied as a policy per customer group and posted to the ledger, from A$99 a month.
For a team that wants overdue accounts called by a person, CreditorWatch Collect. For bureau credit checking and letters in one tool, Chaser, from £199 a month. Upflow and Invoiced fit larger analytics-led and mid-market ERP teams.
Why do teams look for an ezyCollect alternative?
Three reasons recur: no late fee or interest anywhere in the product, an entry tier last published at A$275 a month with a setup fee from A$900 and mail, SMS, fax and A$49 demand letters charged on top, and pricing by debtor count rather than by what you invoice.
Which ezyCollect alternative is cheapest?
Paidnice publishes A$99 a month with no setup fee, covering 150 invoices, 600 emails and up to two team members. Chaser publishes £199 a month on Compact for revenue under £4m. CreditorWatch Collect, Upflow and Invoiced publish nothing, so the cheapest quoted option cannot be established without a call.
Which alternative fits best for credit risk?
CreditorWatch Collect is the closest match to ezyCollect's Experian screening, since its parent is a credit bureau, though the bureau's adverse-data monitoring sits outside the Collect product itself. Chaser carries Creditsafe reports, scores and monitoring inside the tool. Paidnice runs native credit checks from each customer's payment behaviour, and Creditsafe bureau checks through the API on the Custom plan.
Do these alternatives integrate with MYOB?
CreditorWatch Collect connects to MYOB natively. Paidnice reaches MYOB on its Custom plan only, as a build. Chaser, Upflow and Invoiced do not list a MYOB connector. If you run AccountRight or Exo, check this before anything else.
Does ezyCollect charge late fees or interest?
No. No late fee, interest or surcharge function appears in its help centre or in its July 2026 relaunch messaging. Card surcharging is the only charge the product raises, and demand letters are billed to you at A$49 each plus GST rather than charged to the customer.
To see where this tool sits in the wider market, the credit control software guide compares six tools on price, free trial, ledger and limits.
More for Australian and New Zealand teams
Buyer's guide
Best accounts receivable software
The pillar guide: pick by size and accounting system, with a recommendation matrix.
Head to head
Paidnice compared with ezyCollect
The two products side by side on enforcement, pricing and bureau credit data.
Head to head
ezyCollect compared with Chaser
Debtor-count pricing against turnover pricing, and what each one charges for.
Free tool
AR turnover ratio calculator
Score your collection speed against your industry benchmark.
Sources
15 sources, checked by Julie Turnbridge on November 3, 2026
- Xero Small Business Insights xero.com/au/resources/small-business-insights
- Xero App Store apps.xero.com/uk/app/paidnice
- Capterra capterra.co.uk/software/254868/paidnice
- Xero App Store apps.xero.com/au/app/creditorwatch-collect/reviews
- Capterra capterra.com/p/144647/Debtor-Daddy
- Xero App Store apps.xero.com/uk/app/chaser
- G2 g2.com/products/chaser/reviews
- Capterra capterra.com/p/157101/CHASER
- G2 g2.com/products/upflow-upflow/reviews
- Capterra capterra.com/p/193097/Upflow
- Xero App Store apps.xero.com/us/app/upflow
- Xero App Store apps.xero.com/au/app/ezycollect/reviews
- G2 g2.com/products/ezycollect/reviews
- Capterra capterra.com/p/135729/ezyCollect
- Wayback Machine web.archive.org/web/20240617113004/https://ezycollect.io/...

