The five best Kolleno alternatives in 2026 are Paidnice, Chaser, Upflow, Satago and ezyCollect, compared on whether the tool applies late fees and interest itself and at what grain. Published entry prices start at £49 (US$69) a month, against $650 per user.
| Tool | Best for |
|---|---|
| Paidnice | Teams that want late fees and interest applied per customer group, any size up to $50m a year, or 50,000 invoices a year |
| Chaser | Teams that want bureau credit checks in the same tool as the chasing, under £4m on the entry tier |
| Upflow | Finance teams that manage collections by metric |
On Xero's latest US small business data, small businesses waited 29.7 days for payment and the average invoice still settled 8.6 days after it was due.
What accounts receivable software is (and what it is not)
Accounts receivable software works the open invoices in your ledger. It reads them from Xero, QuickBooks Online or an ERP, chases them on a schedule you set, and records what happens until each one is paid.
Across Kolleno and the five tools below, that work covers:
- Reminder workflows by email, with SMS, letters or call tasks on some tools
- Customer statements, and a portal for viewing and paying invoices
- Late fees and interest, on the three tools that raise them
- Payment plans that split an invoice into dated payments
- Credit checks, and escalation to demand letters or an agency
- Cash application, in full on Kolleno and in lighter forms on Upflow and ezyCollect
It is not your ledger. Xero, QuickBooks Online or NetSuite still holds the invoice and the payment. Where a tool raises a charge, it posts that charge back to the ledger as an invoice.
It is not bank reconciliation by default. Most tools here mark an invoice paid when the ledger says so. Matching bank files and remittances is a separate capability, and only Kolleno carries it in full.
It is not invoice finance or a debt collection agency. Satago sells finance beside its software, and ezyCollect refers a debt to a partner agency, but both are services separate from the chasing.
Late fees, credit checks and cash application are layers you add when your ledger needs them.
How this list was put together
This list helps a team weighing Kolleno find a tool that acts on overdue invoices at a price that is not set per seat.
| What we checked | Where the evidence came from |
|---|---|
| Late fee grain | Vendor help pages on fees and interest |
| Cash application and reconciliation | Vendor product pages |
| Published from-price | The vendor's pricing page, and the last reported price where it is now hidden |
| Statements, payment plans and a portal | Vendor feature pages |
| Credit checks | Vendor product pages |
| Rating and review count | The Xero App Store, including the Australian store, or G2 |
What is Kolleno for, and what does it cost per seat?
Kolleno is an order-to-cash platform whose center of gravity is reconciliation, sold per user in turnover bands: BusinessPay at $650 a month per user, $545 on annual billing, and Business Plus at $1,245 per user for turnover from £1m to £100m.
Our own arithmetic from the published rates: one user is $650 a month, or $6,540 a year on annual billing.
Three users is $1,950 a month, which is $23,400 a year billed monthly or $19,620 billed annually. Five is $3,250 a month, $32,700 a year billed annually. That is before a single reminder has gone out, and integrations, customisations and add-ons are noted as extra on top.
Add a person to the collections desk and the software bill moves with the payroll.
What the money buys is real. Reminders run as trigger-based workflows with conditional branches, run-hour restrictions and automatic escalation, over a branded portal carrying saved payment methods, credit notes and disputes.
Kolleno lists AI agent support from Business Plus as insights, a copilot drafting messages for review, and an agent that works a collections policy on its own, with fully automated agent runs and AP portal features billed separately by token use. It holds 4.9 from 117 G2 reviews, 5.0 from 18 Xero App Store reviews and 5.0 from 8 on Capterra.
- The bill scales with people rather than invoices. A collections desk that grows to handle more volume pays twice for the same growth, once in salary and once in licences.
- Nothing charges for being late.
- Finding things, and reporting on them. G2 reviewers report difficulty locating features in the interface and ask for reporting that is more robust and more customizable. The SMS and call allowances start at 100 each on BusinessPay and rise to 600 each on Enterprise Plus. Kolleno's pricing page does not say which actions a workflow can hold.
What does Kolleno do that none of the alternatives replace?
Cash application is Kolleno’s real product, and none of the five alternatives below matches it.
- Remittance parsing. Remittance advice arriving by email is read and turned into suggested matches, instead of being opened by a person and typed into a ledger.
- Bank files over SFTP. BAI2 and BAI2-CSV, NACHA and ISO 20022, pulled on a connection to the bank rather than downloaded and imported manually.
- Match scoring. One payment against many invoices, partial settlements, and credit notes offset against open items, each proposed with a confidence rather than left sitting as an unallocated receipt.
- Foreign exchange and bank fees. Differences and charges handled as part of the match, including multi-currency journal entries written straight into NetSuite.
Upflow comes closest, with rules-driven cash application and suggested matches on a similar ledger and ERP list, and it still carries no bank-file ingestion and no NetSuite journal entries. Paidnice, Chaser, Satago and ezyCollect do not compete on this axis at all: they mark an invoice paid when the ledger says it is paid, and the chasing follows.
You can replace the chasing, and add the fee policy Kolleno never had, for a fraction of $650 a seat.
Where does reconciliation go if you leave Kolleno?
Three places, in ascending order of how much cash you are matching: the ledger’s own bank rules, your bank’s file feed into a dedicated engine, or a split stack that leaves reconciliation where it is and moves the chasing out.
A customer pays $18,400 against three open invoices of $9,200, $6,300 and $4,100, and sends no remittance advice.
The residual could be a short payment on the largest invoice, a settlement of the first two plus part of the third, or a deduction nobody has told you about yet.
- Kolleno scores the candidate combinations, proposes the two-invoices-plus-a-partial split, and posts the allocation with the difference written where you tell it to write it.
- Upflow applies its rules, suggests a match, and a person confirms it.
- Paidnice, Chaser, Satago and ezyCollect do not attempt it. The receipt sits in the ledger until somebody allocates it there, and the chasing follows whatever the ledger then says.
Below roughly a few hundred receipts a month, that last row is an inconvenience rather than a crisis. Xero and QuickBooks Online both match receipts against invoices with bank rules, and a NetSuite customer is usually already paying for native cash application.
Above that, with unremitted payments, deductions and multi-currency settlement in the mix, manual matching stops scaling and the case for a dedicated engine returns whatever else you buy.
Which leaves the split stack, and it deserves pricing rather than dismissing. Keep a reconciliation tool for the cash, move the chasing and the fee policy to something flat-priced, and set the total against $650 times the number of people who would otherwise have needed a login.
Which Kolleno alternatives cover the chasing half?
 |  |  |  |  |  |
|
|---|---|---|---|---|---|---|
| Best for | The baseline: cash application and reconciliation, priced per seat | Late fees and interest per customer group, on Xero or QuickBooks Online | Creditsafe checks and four chasing channels at a published price | Reporting and ERP reach closest to Kolleno | Invoice finance beside the chasing, for UK businesses on Sage 50 | Australian and New Zealand trade credit with demand letters |
| Revenue fit | Under £1m on BusinessPay, tiers to £1bn and above | Any size up to $50m a year, or 50,000 invoices a year | Compact under £4m, Core from £4m, Complete to £100m | Gross invoice value tiers, up to $10m through above $100m | Not published | Not published; the entry tier is sized at 200 debtors |
| From (monthly) | $650 per user | US$69 | £199 | $440 for Grow (last published; now hidden, request a quote) | £45 (£25 inside Sage 50) | A$275, setup from A$900 (last published; current prices hidden and must be requested) |
| Ledger integrations | NetSuite, SAP, Sage Intacct, Business Central, Xero, QuickBooks Online | Xero, QuickBooks Online and newer ledgers such as Rillet and Campfire (closed testing) on every plan; Sage Accounting and other ERPs on Custom | Xero, QuickBooks, Sage, NetSuite, Dynamics 365 Business Central | Xero, QuickBooks Online, NetSuite, Sage Intacct, Stripe Billing, Chargebee, Zuora | Xero, Sage, Sage 50, QuickBooks, KashFlow, FreeAgent | Xero, MYOB, NetSuite, Sage 300, Sage Intacct, SAP Business One; QuickBooks logo on homepage, no connector page |
| Late fee grain | None found | Yes (per customer group) | Yes (one set of rules for the account) | No (via your ERP only) | Optional, added to reminder emails | None found |
| Statements | Yes (in the portal) | Yes (any schedule) | Yes (monthly, fixed day) | Portal PDF statement, no scheduled send | Yes | Yes (monthly) |
| Payment plans | Yes | Yes (on Pro) | Yes | No (part payments and promises to pay) | Not documented | Yes (enabled by support) |
| Portal | Yes | Yes | Yes | Yes | Not documented | Yes |
| Credit checks | Yes (AI scores, bureau integrations) | Yes: native checks from payment behavior, plus Creditsafe via API on the Custom plan | Yes (Creditsafe) | Yes (light scoring) | Yes (credit reports and limits) | Yes (Experian data) |
| AI | Advanced Insights, Copilot drafts and an autonomous Agent; AI agent support from Business Plus, fully automated agent runs and AP portal features billed separately by token use | Advanced Reads customer replies, drafts answers and follow-up actions (like PO updates) for your approval; MCP server for Claude, ChatGPT and other agents | Advanced Collections and cash application agents, from suggest-only to autonomous (Collections Agent from Scale, Cash Application Agent from Accelerate) | None No AI feature found | Basic an AI email template generator as a paid add-on | |
| Rated (source, count) | 4.9 (117, G2) | 5.0 (84, Xero App Store) | 4.98 (374, Xero App Store) | 4.8 (235, G2) | 4.93 (92, Xero App Store) | 4.9 (35, Xero App Store AU) |
"Not documented" means the vendor does not document the capability. "Not published" means the vendor does not print a price. "None found" means no evidence either way. Prices are the vendor’s published from-price.
The six tools in five checked facts
- Four of the six print a monthly price: Satago from £45, Paidnice from £49 (US$69), Chaser from £199 and Kolleno from US$650. Upflow and ezyCollect do not print a price.
- Each published price grows with something different: a flat tier (Satago), invoice volume (Paidnice), revenue band (Chaser) and users (Kolleno).
- Three of the six apply a late fee: Paidnice (per customer group), Chaser (one set of rules for the account or selected debtors) and Satago (optional, added to its reminder emails).
- Five of the six connect to both Xero and QuickBooks Online; ezyCollect shows a QuickBooks logo on its homepage but no connector page.
- AI that handles collections work or customer replies: Paidnice, Upflow and Kolleno. AI that scores or predicts only: ezyCollect. No AI in receivables: Satago.
We checked each tool's own pricing, integration and help pages. "None found" in the data means the vendor's pages do not show the feature.
1. Paidnice, best for customer-group late fees
Best for: Teams that want late fees and interest applied per customer group, any size up to $50m a year, or 50,000 invoices a year.
What is Paidnice best for?
For a business on Xero or QuickBooks Online that wants the chasing and a charge on the ledger for a fraction of a seat licence, and will put the reconciliation elsewhere.
- Fits
- Businesses on Xero and QuickBooks Online of any size up to $50m a year, or 50,000 invoices a year, with or without a credit controller
- Regions
- United States, United Kingdom, Australia, New Zealand, Canada, South Africa
- Entry cost
- £49 (US$69) a month on Essentials, covering 150 invoices, 600 emails and up to 2 team members; £49 (US$69) and A$99 in local price tables, not converted; Pro from £74 (US$99) a month with unlimited users and no per-seat fee
- Rated
- 5.0 from 84 Xero App Store reviews; 4.9 from 14 on Capterra · Xero App Store listing
- Awards
- Xero Global Small Business App of the Year 2025 and NZ Small Business App of the Year 2026
- Runs on
- Xero and QuickBooks Online on every plan. Newer ledgers such as Rillet, Campfire, Digits, DualEntry, Puzzle, Accounting Seed and Odoo are available on every plan through Paidnice's closed testing program. Stripe, Pinch Payments, CloudDepot, HubSpot, Pipedrive, Zapier. NetSuite, Sage Intacct, MYOB and Dynamics 365 Business Central connect on the Custom plan, as do Sage Accounting and other ERPs
- Late fees and interest
- Yes. Flat, percentage and compounding charges, with a Bank of England base rate toggle for UK invoices, raised on the ledger as Draft or Approved. Policies sit under customer groups, so several run at once
- Does best
- Two charge types on the same customer group, an invoice late fee and a statement interest charge, both posted to the ledger
Paidnice does one half of Kolleno’s job and makes no claim on the other.
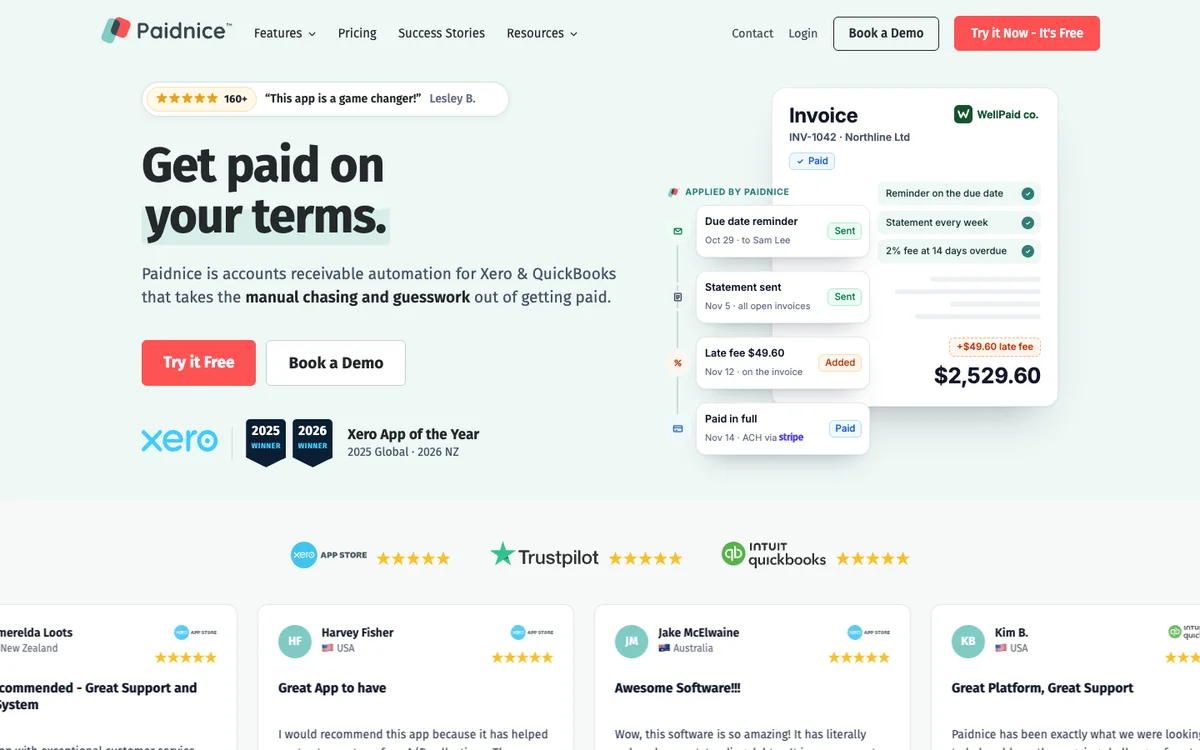
On the chasing side it reads every open invoice on Xero or QuickBooks Online against the policies you set, then runs reminder sequences and statements from your own authenticated domain by email and SMS, statements consolidated across parent and child contacts, payment plans, a customer payment portal and escalation through manual task workflows. Payment plans and sending from your own domain start on Pro. Essentials sends from outbound@paidnice.com.
What it adds that Kolleno has never documented is the charge. A late fee posts to the ledger as an invoice, Draft or Approved, so it reaches the customer’s payables and their payment run rather than sitting in your collections tool.
Statement interest is recalculated at the moment the statement sends instead of carrying forward from the last policy run, and it is figured on the balance after any credit on the account, with compounding on by default.
Paidnice says that when a reply comes in, its AI reads it and drafts the answer, and a person approves each drafted reply before it sends. Additional Xero or QuickBooks organisations arrive through a multi-entity add-on from US$29 each a month, which is a third unit, separate from seats and turnover bands.
Limitations with Paidnice. No cash application, no remittance parsing and no bank files, so the capability that justifies Kolleno’s price is absent.
It runs natively on Xero and QuickBooks Online and reaches NetSuite, Sage Intacct, MYOB and Dynamics 365 Business Central only as a Custom-plan build, which rules it out for a large part of Kolleno’s installed base.
Essentials holds two seats, 150 invoices and 600 emails.
2. Chaser, best for chasing plus credit bureau
Best for: The chasing half plus a credit bureau.
At a price a smaller team signs off, under £4m on the entry tier
What is Chaser best for?
For an order-to-cash team that will trade the reconciliation engine for a bureau, four channels of chasing and a printed price it does not pay per seat.
- Fits
- Businesses with a named credit controller; the entry tier is priced for turnover under £4m, and the tiers run to £100m
- Regions
- UK-registered, trading since 2014, sells worldwide. Automated calls are not available in New Zealand
- Entry cost
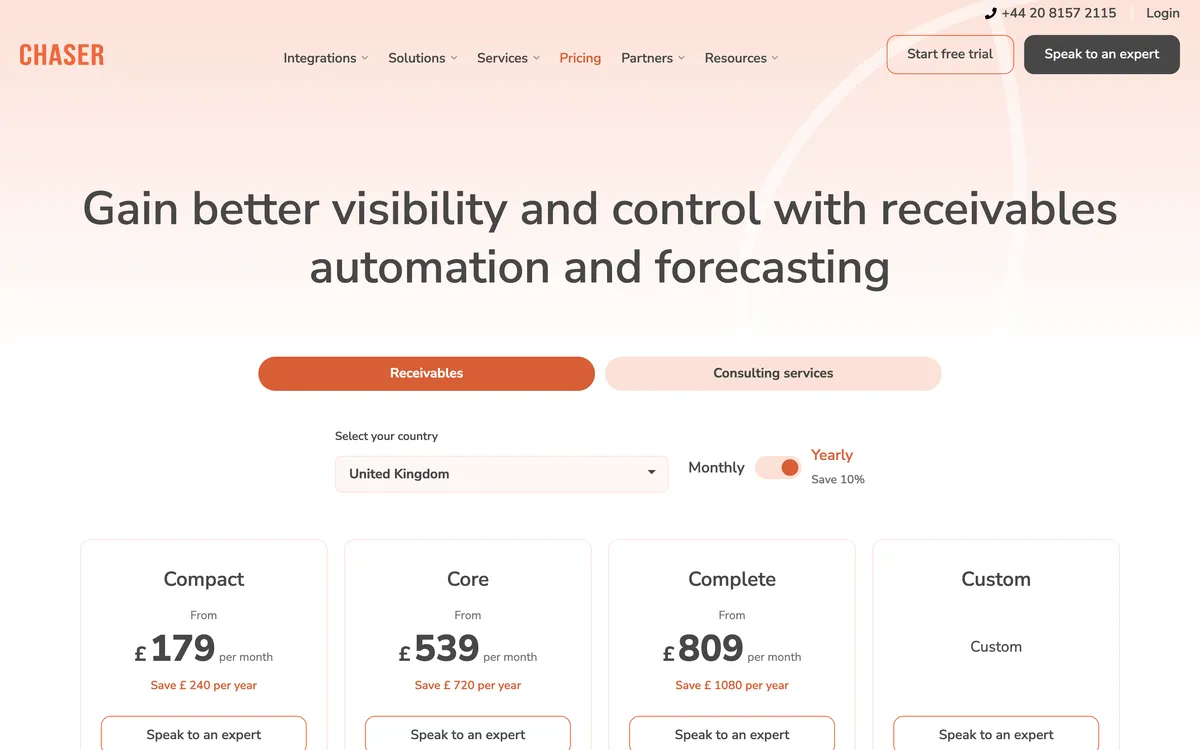
- £199/mo on Compact for turnover under £4m with 4 users; Core £599/mo under £10m; Complete £899/mo to £100m. Yearly billing is £179, £539 and £809 a month.
- Rated
- 4.98 from 374 Xero App Store reviews; 4.3 from 71 on G2; 4.9 from 45 on Capterra · Xero App Store listing
- Awards
- Finalist, UK Small Business App Partner of the Year, Xero Awards 2023
- Runs on
- Xero, QuickBooks, Sage 50, Sage 200, Sage Intacct, Sage Business Cloud Accounting, NetSuite, Dynamics 365 Business Central, AccountsIQ, SAP, HubSpot, Gmail, Outlook
- Late fees and interest
- Yes. Four calculation types including a Bank of England base rate type, recalculated daily, but one set of rules for the account, applied to every debtor or to selected debtors, and no fee is raised on payment-plan or partially paid invoices
- Does best
- Creditsafe credit checking and monitoring in the same tool as email, SMS and letter chasing
- Customers
- Named on its website: Pact Coffee, Huttie and TaxAssist. Huttie's case study reports £15,000 of old debt recovered.
Chaser answers the chasing half broadly, with the widest set of channels on this page: reminders from the team’s own Gmail or Outlook mailbox, SMS, posted letters, one-way automated calls, a payer portal and a collections referral through a partner network.
Every channel except email is metered by credit, so the running cost tracks how hard you chase rather than how many people log in.
The capability worth weighing against Kolleno’s AI scoring is the bureau. Its in-app credit report comes from Creditsafe, carrying a credit score with a recommended limit, the customer’s payment score, credit event history, and Companies House filing and director data, with continuous monitoring. Chaser credit checks need Chaser billing, not Xero App Store billing; monitoring is not offered in Australia.
That arrives as a published, priced product where Kolleno’s equivalent arrives through bureau integrations and a quote.
Limitations with Chaser. The late fee exists but runs as one set of rules for the account, applied to every debtor or to selected debtors, and raises nothing on payment-plan or partially paid invoices. Statements are monthly, on a fixed day. Compact holds four users.
Chaser prices by revenue band. There is no cash application layer of any kind. Reviewers report that a reply to a chasing email cannot be answered inside the tool.
3. Upflow, best for Kolleno-like reporting
Best for: Teams that want Kolleno-style reporting and ERP reach, quoted by gross invoice value tier.
What is Upflow best for?
For a team that used the dashboards every week and the bank-file ingestion once a quarter, and can live with rules-based matching instead of a reconciliation engine.
- Fits
- B2B finance teams that manage by metric, quoted in five tiers by gross invoice value, from up to $10m on Starter to above $100m on Enterprise
- Regions
- New York head office, Paris origin, customers in 30-plus countries
- Entry cost
- Not published. Upflow prints no figures and quotes five tiers by gross invoice value; Upflow offers a free Discover dashboard tier and a 14-day free trial on its Xero App Store listing; its pricing page lists no trial. Upflow's last published prices were $440 a month for Grow and $880 for Scale
- Rated
- 4.8 from 235 G2 reviews; 4.5 from 15 on Capterra · Xero App Store listing
- Awards
- Not published
- Runs on
- Xero, QuickBooks Online, NetSuite, Sage Intacct, Stripe Billing, Chargebee, Zuora
- Late fees and interest
- No, via your ERP only. Upflow’s own documentation points the job back to the ERP and there is no native computation
- Does best
- Collections analytics, with countback DSO against best possible DSO, collection effectiveness and an at-risk rate above 90 days
- Customers
- Named on its website: Lattice, Vercel and Front. Lattice's case study reports 99% collection with one person in AR.
Upflow is the nearest thing on this page to Kolleno itself: the same mid-market B2B buyer, the same reach past the small business ledgers into NetSuite and Sage Intacct, the same quote-on-request pricing.
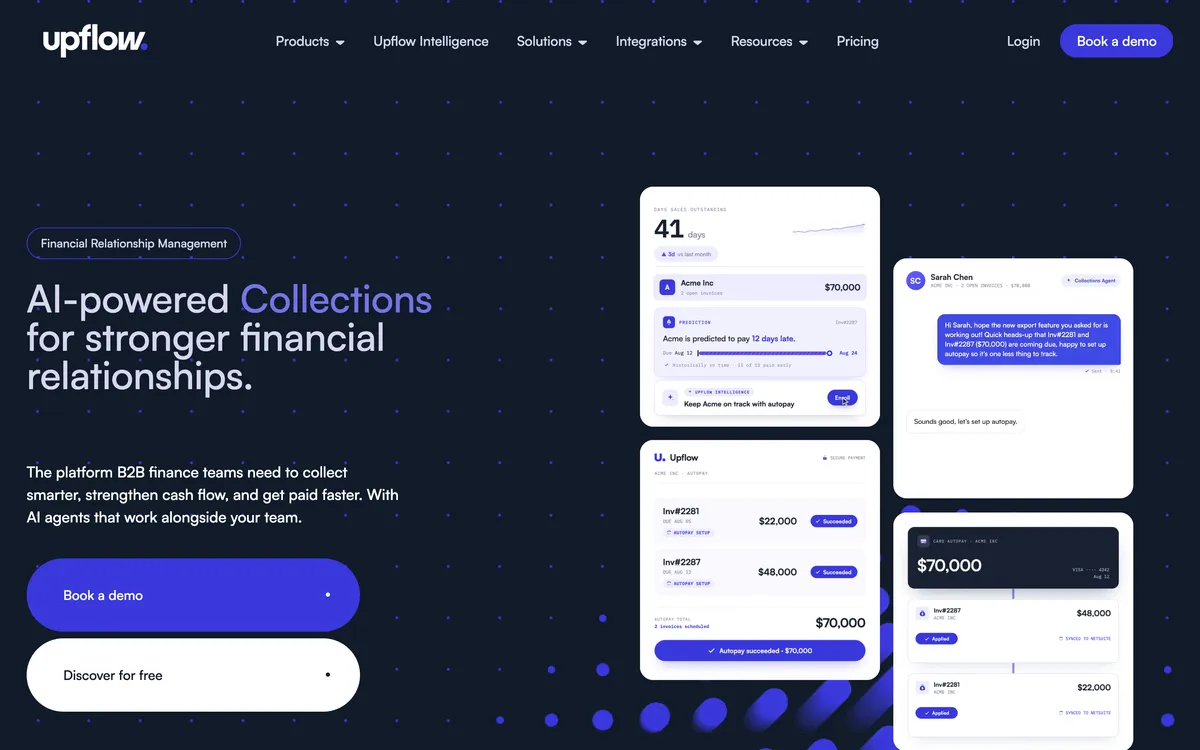
It is also one of two alternatives here with cash application, through rules and suggested matches (ezyCollect is the other), and the only one that reads Stripe Billing, Chargebee and Zuora as well as the ledger.
Its own center of gravity is measurement rather than matching: countback DSO set against best possible DSO, collection effectiveness, at-risk balances past 90 days and billing-cohort forecasting, on dashboards you can filter by workflow, country or account manager and have delivered by email.
Limitations with Upflow. The cash application is rules and suggestions rather than BAI2, NACHA and ISO 20022 files with NetSuite multi-currency journals, so the reconciliation gap narrows without closing.
No native late fees: the job goes back to your ERP, and a business on Xero or QuickBooks Online has no ERP to send it to. No installment schedules, only part payments and promises to pay, which is thinner than the plans you already run.
Automatic actions fire once a day on business days. Own-SMTP sending switches off open and click tracking, and the QuickBooks link polls every five minutes with payments landing in Undeposited Funds. Upflow's last published prices were $440 a month for Grow and $880 for Scale. Current prices are hidden and must be requested from Upflow.
4. Satago, best for UK invoice funding
Best for: A UK team that would rather fund the invoice than reconcile it faster, no revenue band published.
What is Satago best for?
For a United Kingdom business on Sage 50 or Xero whose cash problem is timing rather than matching, and that would take an advance over a faster allocation.
- Fits
- UK businesses in the Sage and Xero ecosystem. No revenue band published
- Regions
- United Kingdom only
- Entry cost
- £25/mo Standard and £45/mo Plus inside Sage 50, with Plus included on selected Sage 50 subscriptions; standalone £45/mo Basic, £80 Premium, £200 Platinum.
- Rated
- 4.93 from 92 Xero App Store reviews, UK listing
- Awards
- Not published
- Runs on
- Xero, Sage, Sage 50, QuickBooks, KashFlow, FreeAgent
- Late fees and interest
- Optional. Late fees are calculated in line with statutory limits and added to payment reminders once an invoice is overdue
- Does best
- Credit reports, customer credit scores and suggested credit limits bundled into the same subscription as the chasing, with invoice finance from the same provider
Satago is the cheapest published entry price on this page and the narrowest product on it: chasing and risk insight in the software, single and full invoice finance from the same provider. The Sage 50 embedded edition runs £25 a month on Standard, and Sage states that Plus comes with selected Sage 50 subscriptions without naming which ones.
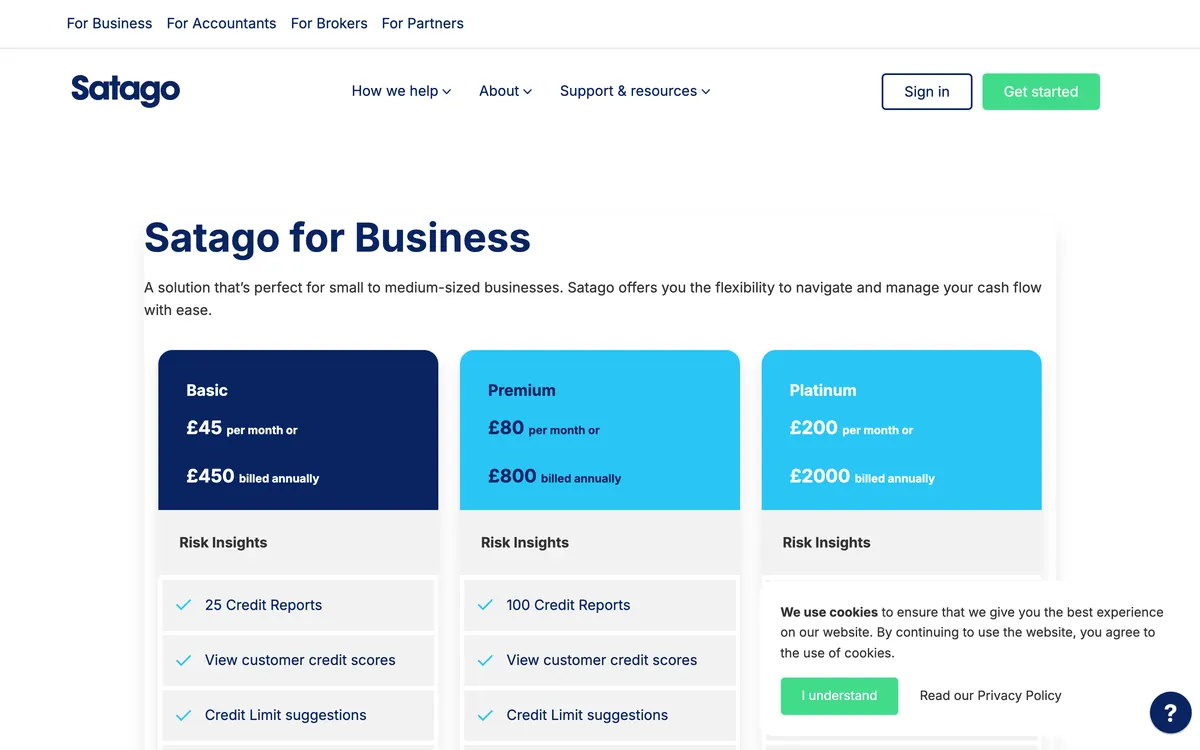
The bundle covers payment reminders, statements, customer grouping and scheduling, with three full credit reports a year on Standard and 25 on Plus, and no cash application of any kind.
What it adds instead is a funding line: rather than reconcile the payment faster, Satago will advance against the invoice before it arrives.
Limitations with Satago. No cash application, no bank files and a United Kingdom footprint only, which rules it out for the international operations Kolleno sells into. Basic caps you at 100 email reminders a month, and sending from your own inbox starts at the £80 Premium tier.
Satago's optional late fee is added to its reminder emails.
5. ezyCollect, best for Experian credit data
Best for: ANZ trade teams that want escalation and Experian data.
From a last-published A$275 a month plus a setup fee
What is ezyCollect best for?
For an Australian or New Zealand trade business that wants the escalation path, demand letters and an agency referral, in the platform that also chases.
- Fits
- Australian and New Zealand order-to-cash teams. No revenue band published; the entry tier is sized at 200 debtors, 3 users and 1 workflow
- Regions
- Australia and New Zealand core market, acquired by Sidetrade in October 2025, with ledger connectors reaching the United States
- Entry cost
- ezyCollect's last published prices were A$275 a month for ezyStart, with a setup fee from A$900. Current prices are hidden and must be requested. Last published on ezyCollect's pricing page, seen on the Wayback Machine. ezyGrow was A$950 and ezyScale A$2,350 on a 12-month plan, with monthly billing 20% higher. The payment gateway is A$90/mo and demand letters are A$49 each, quoted ex GST.
- Rated
- 4.9 from 35 Xero App Store reviews; 4.7 from 25 on G2; 4.9 from 12 on Capterra · Xero App Store listing
- Awards
- None found
- Runs on
- Xero, MYOB AccountRight, Exo, Essentials and Acumatica, NetSuite, Dynamics, Sage 300, Sage Intacct, SAP Business One, Pronto Xi, Attaché, JCurve; QuickBooks logo on homepage, no connector page
- Late fees and interest
- None found. Nothing in the help center or the July 2026 relaunch materials documents a late fee or interest calculation. Card surcharging is the only charge mechanic
- Does best
- Credit screening on Experian data, in-app demand letters and referral to a collections partner, in one platform
- Customers
- Named on its website: Feral Brewing, Hampers with Bite and Skillinvest. Feral Brewing's case study reports overdue accounts cut by over 50%.
ezyCollect is the Australian and New Zealand answer, and like Upflow it carries cash application, here automatic with ERP write-back.
The chasing works the customer rather than the invoice: overdues are consolidated into a single workflow of a pre-reminder and a set of follow-up steps (six in the help center's example) across email, SMS, post and call tasks, with live credit intelligence from Experian behind it.
Its distinctive layer is escalation rather than reconciliation. Credit Insights scores a trade buyer from your own aged trial balance and terms plus Experian data, in-app demand letters go out at A$49 each, and a referral to a partner collections agency is a button rather than a procurement exercise.
Sidetrade acquired the business in October 2025.
Limitations with ezyCollect. No late fee or interest anywhere in the product, so on enforcement it is no better than the platform you are leaving.
Its cash application is nothing like Kolleno’s: no bank-file formats and no match scoring are documented. Customers past the end of a workflow stop receiving automated follow-ups, and reminders consolidate per customer rather than per invoice.
The entry tier carries a A$900 setup fee and a A$90 monthly gateway fee with SMS, post and fax metered on top, and collections referral runs from 25% of what is recovered. The review base is thin and mostly predates 2024, and reviewers report quoted prices landing above the advertised figure.
Does Kolleno charge for late payment?
No feature page, help article or release note in Kolleno’s materials documents a late fee or an interest calculation. Three of the five alternatives do: Paidnice as a policy per customer group, Chaser as one set of rules with four calculation types. ezyCollect documents none, Satago adds an optional late fee to its reminder emails, and Upflow hands the job to your ERP.
Every other lever in Kolleno acts on your side of the relationship: the workflow fires, the portal opens, the agent drafts, the match posts.
A charge is the only lever that acts on the customer’s side, by changing what your invoice is worth to them relative to the others in their payment run.
Grain is what separates the two tools that do it. Chaser recalculates daily but applies one set of rules across the account or to selected debtors, not tied to schedules, and raises nothing on an invoice that is on a plan or has been part paid, which on a ledger of Kolleno’s size covers most of the negotiated and disputed accounts.
Paidnice hangs its policies under customer groups, so a group you would never charge, a group you always would, and a group in dispute each carry their own rule at once, with a per-invoice fee and a whole-balance interest charge running together.
Wherever the charge comes from, it counts only if it is posted to the ledger as an invoice. That is what puts it into the customer’s own payables, their aged payables report and their approval queue.
It is also negotiable on purpose. A charge that has been raised can be waived in writing in exchange for payment today, which is a conversation a credit controller can have. A charge the rule was never allowed to raise gives them nothing to trade.
How do Kolleno’s installment plans compare with the alternatives?
Kolleno splits an invoice weekly, monthly or bi-monthly and ties its automations to the schedule. Paidnice, Chaser and ezyCollect all schedule installments too. Upflow does not, and nothing could be verified for Satago.
Kolleno’s uneven totals are divided manually, and the plan itself carries no interest, no deposit and no approval step.
Paidnice runs deposits, installments and auto-pay through Stripe and Pinch with the policy engine still live behind the plan.
Chaser splits an invoice weekly through to yearly but keeps chasing the original invoice due date rather than the installment dates, and its own documentation advises chasing the installments manually, which is a step backwards from where you already are. ezyCollect sells Payment Plans as a paid add-on.
Upflow records a promise to pay and accepts an ad-hoc part payment, which is an intention rather than a schedule.
What does $650 a seat buy elsewhere?
Published entry prices for the five alternatives: Satago from £45 a month (£25 inside Sage 50), Paidnice £49 (US$69), Chaser £199, ezyCollect A$275 a month for ezyStart plus a setup fee from A$900 (last published; current prices are hidden and must be requested). Upflow's last published prices were $440 a month for Grow and $880 for Scale; current prices are hidden and must be requested. Check current pricing with the vendor.
Against that, the Paidnice tiers at £49 (US$69) and £74 (US$99) carry no per-seat fee above the entry plan, so the second and third person on the desk cost nothing in licences.
Chaser’s Compact tier holds four users inside its £199.
Kolleno matches payments to invoices (auto-reconciliation) on Enterprise only, by quote. BusinessPay at $650 per user a month does not include it. Xero and QuickBooks connect on BusinessPay and Business Plus; NetSuite and SAP start on Enterprise. The two sections above are the honest version of what dropping auto-reconciliation costs. And integrations, customisations and add-ons are noted as extra in its own materials, so any comparison should start from your quote rather than from the list price. Kolleno's terms of service set a default term of 24 months, renewing for 12 months, with 90 days' notice and non-refundable fees.
NetSuite, SAP and Sage Intacct: the band where this gets hard
Kolleno reaches NetSuite, SAP S/4HANA and Business One, Sage Intacct, Dynamics 365, Workday, Oracle JD Edwards, Epicor, Infor, Odoo and Zuora as well as Xero and QuickBooks Online.
- NetSuite. Upflow and Chaser connect; Paidnice reaches it only as a Custom-plan build. None of them writes multi-currency journal entries for FX differences and bank fees the way Kolleno does, so a NetSuite finance team gives up more here than anywhere.
- SAP. ezyCollect connects to SAP Business One and Chaser lists SAP. Nothing here reaches S/4HANA on the terms Kolleno does.
- Sage Intacct. Upflow and Chaser natively, ezyCollect through its ERP list, Paidnice on the Custom plan only.
- Xero and QuickBooks Online. Four of the five connect to both (ezyCollect shows a QuickBooks logo on its homepage but no connector page), and this is where the choice opens up rather than closes down.
- Sage 50 and Sage 200. Satago and Chaser. Neither Paidnice nor Upflow serves Sage 50 or Sage 200.
The rule that falls out of it: if your ledger is Xero or QuickBooks Online, every alternative here is available and the decision comes down to enforcement and price. If it is NetSuite, SAP or Sage Intacct, the shortlist is Upflow and Chaser, and the reconciliation question from earlier has to be answered before anything is signed.
Which Kolleno alternative fits your use case?
| Use case | Start with | Why |
|---|---|---|
| Xero or QuickBooks Online, and you want the chasing plus a late fee without seat pricing | Paidnice | No per-seat fee above the entry plan, from £49 (US$69) a month |
| Matching cash is the bottleneck and the chasing already works | Kolleno | Nothing here matches its bank files, remittance parsing and match scoring. Consider Paidnice for the chasing around it. |
| Keep the dashboards and the NetSuite or Sage Intacct reach | Upflow | Countback DSO and rules-based matching on a similar ERP list, quoted rather than priced |
| Credit checks before you extend terms | Chaser | Creditsafe reports and monitoring, from £199 with four users |
| A UK business on Sage 50 with a cash timing problem | Satago | £25 a month inside Sage 50, with invoice finance from the same provider |
| Australian or New Zealand trade customers | ezyCollect | Experian data, demand letters and an agency referral in one platform |
Questions from order-to-cash teams
What is the best Kolleno alternative in 2026?
Paidnice is the best Kolleno alternative for a team on Xero or QuickBooks Online that wants the chasing and a charge on the ledger without a seat licence, from £49 (US$69) a month. Chaser fits, from £199 a month, if the Creditsafe bureau matters more than the price.
Upflow is the closest on cash application, Satago pairs chasing with invoice finance, and ezyCollect fits Australian and New Zealand teams.
Why do teams look for a Kolleno alternative?
The recurring reasons are price and enforcement. BusinessPay is $650 per user a month, for turnover under £1m and without workflow automation, and no late fee or interest calculation is documented anywhere in Kolleno’s materials. G2 reviewers also report trouble finding features in the interface and ask for reporting that is more robust and more customizable.
Is there a cheaper alternative to Kolleno?
Yes. Kolleno publishes $650 per user a month, or $545 on annual billing, for turnover under £1m. Paidnice publishes £49 (US$69) a month and Satago from £45 a month (£25 inside Sage 50), and neither charges per seat on its entry tier.
Which Kolleno alternative charges late fees automatically?
Paidnice and Chaser apply late fees themselves, and Satago adds an optional fee to its reminder emails. Paidnice raises flat, percentage or compounding charges under a policy attached to a customer group, and writes the charge into the ledger as a Draft or Approved invoice.
Chaser computes four calculation types daily but applies the result as one set of rules, across the account or for selected debtors, and raises nothing where an invoice is on a plan or has been part paid.
How much does Kolleno cost?
Kolleno publishes per-user pricing: BusinessPay at $650 per user a month, or $545 on annual billing, for turnover under £1m, then Business Plus at $1,245 per user for turnover from £1m to £100m, with custom Enterprise tiers above that. Integrations, customizations and add-ons may cost extra. Check current pricing before you buy.
Do Kolleno alternatives integrate with Xero and QuickBooks?
All five reach at least one of them. Paidnice, Chaser and Upflow connect to both a Xero organisation and QuickBooks Online; ezyCollect connects to Xero and shows a QuickBooks logo on its homepage but no connector page; Satago covers Xero, Sage, Sage 50, QuickBooks, KashFlow and FreeAgent. What none of them reaches is the depth of Kolleno’s ERP list, so check your own system and edition before shortlisting anything.
Which alternative is closest to Kolleno on cash application?
Upflow, which automates cash application with rules and suggested matches on the same mid-market ledger and ERP list. None of the five matches Kolleno’s remittance parsing, bank-file support or NetSuite multi-currency journal entries, so a team buying purely on reconciliation depth should weigh what it gives up.
To see where this tool sits in the wider market, the credit control software guide compares six tools on price, free trial, ledger and limits.
Related guides for order-to-cash teams
Buyer's guide
Best accounts receivable software (by business type)
The pillar guide: pick by size and accounting system, with a recommendation matrix.
Alternatives
Best Upflow alternatives
Six Upflow alternatives on enforcement, price and reviews.
Alternatives
Best Chaser alternatives
Six Chaser alternatives on enforcement, price and reviews.
Comparison
Best AR automation software
The AR automation platforms compared on features and price.
Sources
16 sources, checked by Julie Turnbridge on November 3, 2026
- Xero Small Business Insights xero.com/us/resources/small-business-insights
- G2 g2.com/products/kolleno/reviews
- Xero App Store apps.xero.com/uk/app/kolleno
- Capterra capterra.com/p/227932/Kolleno
- Xero App Store apps.xero.com/app/paidnice
- Capterra capterra.com/p/254868/Paidnice
- Xero App Store apps.xero.com/uk/app/chaser
- G2 g2.com/products/chaser/reviews
- Capterra capterra.com/p/157101/CHASER/reviews
- G2 g2.com/products/upflow-upflow/reviews
- Capterra capterra.com/p/193097/Upflow
- Xero App Store listing apps.xero.com/us/app/upflow
- Wayback Machine web.archive.org/web/20240617113004/https://ezycollect.io/...
- Xero App Store apps.xero.com/au/app/ezycollect/reviews
- G2 g2.com/products/ezycollect/reviews
- Capterra capterra.com/p/135729/ezyCollect/reviews

